广告
加载中

天逸集团市场与生态负责人Danni Zeng:备战多渠道 跨境卖家的钱从哪来?

亿邦动力 2026-09-20 17:22
亿邦动力 2026/09/20 17:22

邦小白快读

EN
全文速览

本文为天逸集团市场与生态负责人Danni Zeng在跨境生态加速大会上分享的干货,核心讲解了跨境电商行业新增长周期下,卖家普遍面临的资金周转痛点,以及优化资金效率、选择合适融资服务的实用方法。

1. 当前跨境行业的现实经营压力:规模化卖家数量持续增长,据亚马逊官方披露,2025年前十个月年销售额超1000万美元的中国卖家数量同比增长近30%;但大促获客成本不断上升,平台回款周期拉长,企业前端投入增加、后端回款变慢,可调度现金空间被持续压缩,未来行业竞争不只是比拼卖货能力,更是资金经营效率的较量。

2. 需要避开的经营认知误区:销售额不等于现金流,跨境生意存在采购、备货、物流投入在前,平台订单妥投后还有资金预留结算期的天然时间差,很容易出现新一轮经营投入已启动、上轮销售回款未到账的现金紧张问题,资金效率本质是经营效率,并非财务部门的专属工作。

3. 选择资金服务的实用判断标准:不要等企业缺钱才考虑融资,要选择匹配自身经营周期的服务,重点考量资金稳定性、审批速度、产品期限、综合成本四个维度,优先选依托真实经营数据授信、流程灵活高效的方案。

本次分享为布局多渠道跨境经营的品牌商点明了行业竞争逻辑的变化,以及支撑品牌长期发展的资金管理方向。

1. 要准确把握当前跨境赛道的竞争趋势:规模化品牌卖家数量持续增长,大促节点获客成本持续走高,平台回款周期拉长,行业竞争已经从单一的流量、产品、供应链比拼,延伸到资金效率的综合较量。品牌不能只关注销售规模增长,必须同步搭建适配多渠道布局的资金支撑体系。

2. 品牌经营中要重点规避现金流错配风险:跨境多渠道布局下,采购、备货、物流、广告投入都发生在销售前端,不同平台的结算规则存在差异,比如亚马逊规则下订单妥投后还有7天资金预留期,很容易出现新品推广、多渠道备货、大促投流的投入节点与回款节点错位,导致现金流承压,打断增长节奏。

3. 品牌选择金融支撑服务的参考方向:要选择能匹配采购、备货、广告、回款全链路经营节奏的服务,优先考量资金稳定性、授信逻辑贴合品牌真实经营数据、审批速度适配大促及新品推广窗口、多币种结算灵活的方案,支撑新平台布局、新品放量等长期经营动作。

本次分享针对跨境卖家备战多渠道布局过程中的资金痛点,提示了核心经营风险,点明了现金流管理方法与适配的融资解决方案。

1. 需要警惕当前的经营压力与潜在风险:目前行业内规模化卖家数量持续上升,大促获客成本走高,平台回款周期拉长,前端投入增加、后端回款变慢会持续压缩可调度现金空间;尤其2025年3-4月中美贸易摩擦期间,曾出现部分银行和金融机构暂停电商融资业务的情况,依赖外部中介资金的卖家很容易在行业波动期遭遇资金断流风险。

2. 要纠正常见的经营认知偏差:销售额不等于现金流,跨境生意存在采购、生产、物流前置,平台结算滞后的天然时间差,资金效率本质是经营效率而非单纯的财务问题,如果库存积压时间过久、平台回款慢,哪怕产品竞争力、流量转化表现好,增长也会被现金流卡住。

3. 实操层面的资金解决方案参考:选择融资伙伴要重点对比资金稳定性、审批速度、期限匹配度、综合成本四个维度。目前天逸集团推出的跨境专属信贷服务“天逸电商宝”可覆盖多主体多币种需求,无需抵押物,依托经营数据授信最高可获2亿元融资,千万级拨款最快T+0到账,其中“天逸贸”保理类产品可解决长账期问题,“天逸贷”随借随还类产品可覆盖旺季备货、新品放量、新平台布局、库存周转需求。

本次分享为计划拓展跨境电商渠道的工厂点明了跨境经营的核心逻辑,以及开展跨境业务需要注意的现金流管理要点与可借助的支撑资源。

1. 要认清跨境业务的经营特点与资金要求:当前跨境赛道规模化卖家数量持续增长,据亚马逊数据,2025年前十个月平台上年销超千万美元的中国卖家同比增长近30%。工厂从传统供货模式转向跨境自主经营时,不能只参照销售额规划产能,要注意跨境生意存在采购、生产、物流投入在前,平台订单妥投后还有结算预留期的资金时间差,随着销售规模增长,备货、广告、物流、人力成本会同步提升,必须提前预留足够的现金流调度空间,避免因回款滞后影响正常生产节奏。

2. 工厂开展跨境业务可对接的支撑资源:目前适配跨境场景的金融服务不再只依赖抵押物、财务报表授信,企业可通过店铺销售、回款、库存等真实经营数据获得额度支持,其中面向B2B跨境的“天逸贸”保理产品可解决交付后账期过长的问题,面向B2C的“天逸贷”灵活信贷产品可支撑旺季备货、新品生产的资金需求,千万级资金最快T+0到账,能匹配跨境电商快节奏的经营窗口。

3. 选择资金合作方的提示:要优先选择自有资金稳定、熟悉跨境行业节奏的合作方,避免行业波动期外部资金收缩,影响生产经营的连续性。

本次分享清晰点明了当前跨境电商行业的发展趋势、跨境卖家的核心经营痛点,以及对应的金融服务优化方向,为跨境服务商打磨适配产品、提升服务能力提供了参考。

1. 要准确把握行业发展的核心趋势:当前跨境电商规模化卖家占比持续提升,大促获客成本持续走高,倒逼卖家更精细化地分配运营与广告预算,而平台回款周期拉长使得企业可调度现金空间被压缩,未来行业竞争维度已经从流量、产品、供应链延伸到资金效率,卖家对能切实提升经营效率的配套服务需求会持续增长。

2. 要精准捕捉客户的核心痛点:跨境经营存在采购、备货、物流、广告投入在前,平台结算回款在后的天然时间差,传统金融服务依赖财报、抵押物的授信逻辑,和跨境卖家以店铺销售、回款、库存数据为核心经营资产的特点存在错配,加上电商经营窗口期短,审批慢、额度不灵活的服务无法匹配卖家旺季备货、新品推广、新渠道布局的节奏;此外不少依赖外部资金的服务在行业波动期容易收缩,难以给卖家提供持续稳定的支持。

3. 解决方案的优化方向:优质的跨境金融服务需要打通卖家真实经营数据做授信评估,搭建线上化灵活流程,针对B2B长账期、B2C周转等不同场景设计匹配的产品,用自有资金保持服务稳定性,让资金方案适配卖家经营周期,天逸集团推出的“天逸电商宝”就是这类场景化服务的典型参考。

本次分享从资金服务生态的角度,点明了当前跨境卖家在平台经营中的核心痛点,为平台优化商家服务、完善生态建设、提升商家留存提供了方向参考。

1. 要明确平台上商家的经营变化与核心压力:目前平台上规模化卖家数量持续增长,据亚马逊披露数据,2025年前十个月平台上年销超千万美元的中国卖家同比增长近30%。随着商家规模提升,备货、广告、物流、人力成本同步上涨,而大促获客成本上升、平台回款周期拉长的现状,正在压缩商家的可调度现金流,商家的竞争已经从单纯的卖货能力转向资金经营效率的综合比拼,现金流支撑不足会直接导致商家备货不足、广告投放跟不上,甚至因为资金链问题退出经营。

2. 要关注现有平台规则给商家带来的实际影响:比如平台设置的订单妥投后资金预留期规则,拉长了商家从采购付款到资金回笼的全周期,容易出现商家新一轮备货、投流已经启动,上一轮销售回款还未到账的错配问题,影响商家在大促、新品推广节点的经营动作。

3. 平台生态的优化方向:可以联动资质靠谱的资金服务商搭建适配平台商家的金融服务体系,依托商家在平台的真实销售、回款、库存数据做授信支撑,引入自有资金稳定、审批效率高、产品设计匹配商家账期与备货节奏的服务,帮助商家提升资金使用效率,尤其在贸易政策波动的阶段,保障商家经营连续性,提升平台生态稳定性。

本次分享呈现了中国跨境电商产业进入新增长周期的典型特征、发展中暴露的新问题,以及适配产业需求的金融服务创新模式,具备较高的产业研究参考价值。

1. 跨境产业发展的新动向:当前跨境电商已经进入效率竞争阶段,规模化卖家群体快速扩容,据亚马逊官方数据,2025年前十个月平台上年销超千万美元的中国卖家同比增长近30%,行业竞争维度从早期的流量、产品、供应链比拼,延伸到资金效率的综合较量,资金效率本质是经营效率而非单纯的财务指标,是决定企业增长持续性的核心要素。

2. 产业发展中暴露的新问题:跨境经营链路存在天然的资金时间差,采购、生产、物流、广告投入前置,平台结算存在固定预留期,导致销售额与现金流不同步,企业规模增长时很容易出现现金流支撑不足的问题;而传统金融体系的授信逻辑依赖财报、抵押物,和跨境电商轻资产、经营数据线上化、经营窗口期短的特点存在明显的信用评价与信息结构错配,此外不少跨境融资服务依赖外部资金,在贸易政策波动时容易出现服务收缩,加剧企业经营风险。

3. 产业服务的创新商业模式:适配跨境场景的金融服务开始转向数据授信、自有资金支撑、场景化产品设计的模式,比如“天逸电商宝”通过打通商家经营数据搭建风控模型,以线上化流程提升审批效率,针对不同场景设计专属产品,让资金方案匹配企业经营周期,为解决传统服务错配问题提供了可参考的路径。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

This article summarizes key takeaways from a presentation by Danni Zeng, Head of Marketing and Ecosystem at Tianyi Group, delivered at the Cross-Border E-Commerce Ecosystem Acceleration Conference. Zeng outlines common working capital pain points facing cross-border e-commerce sellers in the industry’s new growth cycle, alongside practical guidance to improve capital efficiency and select appropriate financing solutions.

1. Current operational pressures in the cross-border sector: The number of scaled sellers continues to rise. Per official Amazon data, the count of Chinese sellers generating over $10 million in annual sales on the platform grew nearly 30% year-over-year in the first 10 months of 2025. At the same time, customer acquisition costs during major promotional events keep climbing, platform payout cycles are lengthening, and sellers face rising upfront investments paired with slower downstream cash collection, steadily squeezing available liquidity. Going forward, industry competition will hinge not only on sales capabilities, but also on the efficiency of capital management.

2. Common operational misconceptions to avoid: Top-line revenue does not equal cash flow. Cross-border commerce has an inherent time lag: spending on procurement, inventory, and logistics occurs upfront, while platforms retain a settlement reserve period even after orders are delivered. This structure easily creates cash crunches, where new rounds of operational spending are already underway before revenue from the previous sales cycle clears. Capital efficiency, at its core, reflects overall operational efficiency, rather than being a function reserved solely for finance teams.

3. Practical criteria for selecting capital services: Sellers should not wait until they face cash shortages to explore financing. Instead, they should select services aligned with their own operating cycles, evaluating four core dimensions: capital stability, approval speed, product tenor, and all-in cost. Priority should be given to solutions that underwrite credit based on real operational data and offer flexible, efficient processes.

This presentation clarifies shifting competitive dynamics in the cross-border e-commerce sector for brands operating across multiple sales channels, and outlines capital management priorities to support long-term brand growth.

1. Accurately assessing competition in the cross-border space: The population of scaled brand sellers continues to expand, customer acquisition costs during major promotional events keep rising, and platform payout cycles are growing longer. Industry competition has evolved beyond a narrow contest over traffic, products, and supply chains to become a comprehensive competition centered on capital efficiency. Brands cannot focus solely on top-line growth; they must simultaneously build capital support systems adapted to multi-channel operations.

2. Mitigating cash flow mismatch risks in brand operations: Under a multi-channel cross-border model, spending on procurement, inventory, logistics, and advertising all occurs before sales are realized, while settlement rules vary across platforms. For example, Amazon enforces a 7-day fund reserve period after order delivery. This structure can easily create misalignment between spending timelines for new product launches, multi-channel inventory replenishment, and promotional ad spend, and the timing of incoming revenue—putting pressure on cash flow and disrupting growth momentum.

3. Framework for selecting financial support services: Brands should prioritize services aligned with the full operational cycle spanning procurement, inventory, advertising, and revenue collection. Key evaluation criteria include capital stability, credit underwriting tied to the brand’s real operational data, approval speeds that fit promotional windows and new product launch timelines, and flexible multi-currency settlement capabilities to support long-term initiatives such as expansion onto new platforms and new product scaling.

This presentation addresses working capital pain points for cross-border sellers pursuing multi-channel expansion, highlights core operational risks, and outlines cash flow management practices and applicable financing solutions.

1. Watch for current operational pressures and latent risks: The number of scaled sellers in the industry continues to rise, promotional customer acquisition costs are climbing, and platform payout cycles are lengthening. Higher upfront spending paired with slower downstream revenue collection will continue to squeeze available liquidity. Notably, during the U.S.-China trade friction period in March–April 2025, some banks and financial institutions temporarily suspended e-commerce financing services, leaving sellers reliant on third-party intermediary capital exposed to sudden funding cut risks amid industry volatility.

2. Correcting common operational misperceptions: Top-line revenue does not equal cash flow. Cross-border commerce has an inherent time lag, with procurement, production, and logistics costs incurred upfront and platform settlements delayed. Capital efficiency is fundamentally a measure of operational efficiency, not purely a finance issue. If inventory remains tied up for too long or platform payouts are slow, growth will be constrained by cash flow gaps even for sellers with strong product competitiveness and traffic conversion performance.

3. Practical guidance for capital solutions: When selecting financing partners, sellers should compare four core dimensions: capital stability, approval speed, tenor alignment with operational needs, and all-in cost. Tianyi Group’s dedicated cross-border credit product, Tianyi E-Commerce Bao, covers multi-entity, multi-currency financing needs with no collateral required, offering credit lines of up to RMB 200 million underwritten by operational data, with seven-figure disbursements available as fast as T+0. Its Tianyi Mao factoring product addresses long account receivable cycles, while the Tianyi Dai flexible revolving credit product supports peak-season inventory stocking, new product scaling, new platform expansion, and inventory turnover needs.

This presentation outlines core cross-border e-commerce operating logic for manufacturers planning to expand into direct cross-border sales, along with key cash flow management considerations and available support resources for running cross-border operations.

1. Understanding operational characteristics and capital requirements of cross-border business: The number of scaled sellers on cross-border channels continues to grow. Per Amazon data, Chinese sellers generating over $10 million in annual sales on the platform grew nearly 30% year-over-year in the first 10 months of 2025. When shifting from a traditional supply model to operating cross-border sales directly, manufacturers cannot plan production capacity based solely on revenue projections. They must account for the inherent capital time lag in cross-border commerce: procurement, production, and logistics spending occurs upfront, and platforms apply a settlement reserve period after order delivery. As sales scale, costs for inventory, advertising, logistics, and labor will rise in tandem, so manufacturers must reserve sufficient cash flow headroom in advance to avoid production disruptions caused by delayed payouts.

2. Available support resources for factories launching cross-border operations: Cross-border tailored financial services no longer rely exclusively on collateral and financial statement-based underwriting. Businesses can access credit lines based on real operational data including store sales, receivables, and inventory levels. The B2B cross-border-focused Tianyi Mao factoring product addresses extended post-delivery payment cycles, while the B2C-focused Tianyi Dai flexible credit product supports funding needs for peak-season inventory and new product production. Seven-figure disbursements can arrive as fast as T+0, matching the fast-paced operational windows of cross-border e-commerce.

3. Considerations for selecting capital partners: Priority should be given to partners with stable proprietary capital and familiarity with cross-border industry rhythms, to avoid disruptions to production continuity caused by external capital contraction during periods of industry volatility.

This presentation clearly outlines current cross-border e-commerce industry trends, core operational pain points for sellers, and corresponding directions for optimizing financial services, providing a reference for cross-border service providers to refine tailored products and improve service capabilities.

1. Grasping core industry development trends: The share of scaled cross-border e-commerce sellers continues to rise, and growing promotional customer acquisition costs are forcing sellers to allocate operational and advertising budgets with greater precision. Lengthening platform payout cycles are squeezing corporate liquidity, and industry competition is expanding beyond traffic, products, and supply chains to encompass capital efficiency. Demand among sellers for supporting services that materially improve operational efficiency will continue to grow.

2. Accurately identifying core customer pain points: Cross-border operations have an inherent time lag, with procurement, inventory, logistics, and advertising spending occurring upfront and platform settlement revenue arriving later. The underwriting logic of traditional financial services, which relies on financial statements and collateral, is mismatched with the reality of cross-border sellers, whose core operating assets are store sales, receivables, and inventory data. Compounding this, e-commerce operational windows are short, meaning services with slow approval processes and inflexible credit lines cannot match the pace of sellers’ peak-season stocking, new product promotion, and new channel expansion efforts. In addition, many services reliant on external capital tend to scale back during industry volatility, making it difficult to provide consistent, stable support to sellers.

3. Directions for solution optimization: High-quality cross-border financial services need to integrate sellers’ real operational data for credit assessment, build streamlined digital processes, design targeted products for distinct scenarios such as B2B long payment cycles and B2C working capital turnover, and rely on proprietary capital to maintain service stability, so that financing solutions align with sellers’ operating cycles. Tianyi Group’s Tianyi E-Commerce Bao serves as a typical reference for this kind of scenario-tailored service.

From the perspective of the capital service ecosystem, this presentation identifies core pain points facing cross-border sellers operating on platforms, providing directional guidance for platforms to optimize merchant services, improve ecosystem development, and boost merchant retention.

1. Understanding evolving merchant operations and core pressures on platform: The population of scaled sellers continues to grow. Per official Amazon data, Chinese sellers generating over $10 million in annual sales on the platform grew nearly 30% year-over-year in the first 10 months of 2025. As merchant scale increases, costs for inventory, advertising, logistics, and labor rise in tandem. At the same time, rising promotional customer acquisition costs and lengthening platform payout cycles are squeezing merchants’ available cash flow. Merchant competition has shifted from pure sales capability to a comprehensive contest over capital management efficiency. Insufficient cash flow support directly leads to understocking, underfunded ad campaigns, and even merchant exit due to cash chain breakdowns.

2. Assessing the practical impact of existing platform rules on merchants: For example, fund reserve periods applied after order delivery extend merchants’ full cash conversion cycle from procurement payment to revenue collection. This easily creates mismatches where merchants begin new rounds of inventory replenishment and ad spending before revenue from the prior sales cycle arrives, undermining execution during major promotions and new product launch windows.

3. Directions for platform ecosystem optimization: Platforms can partner with well-qualified capital service providers to build financial service systems tailored to platform merchants, using merchants’ real on-platform sales, receivables, and inventory data to support credit underwriting. They should introduce services backed by stable proprietary capital, with fast approval processes and product structures aligned with merchants’ payment cycles and inventory rhythms, to help merchants improve capital efficiency, ensure operational continuity especially during periods of trade policy volatility, and strengthen the overall stability of the platform ecosystem.

This presentation outlines the defining characteristics of China’s cross-border e-commerce industry as it enters a new growth cycle, emerging issues exposed during development, and innovative financial service models adapted to industry needs, offering high reference value for industry research.

1. New trends in cross-border industry development: Cross-border e-commerce has entered an era of efficiency competition. The cohort of scaled sellers is expanding rapidly: per official Amazon data, Chinese sellers generating over $10 million in annual sales on the platform grew nearly 30% year-over-year in the first 10 months of 2025. Competition has evolved beyond early contests over traffic, products, and supply chains to become a comprehensive competition centered on capital efficiency. Capital efficiency, fundamentally a reflection of operational efficiency rather than a standalone financial metric, is a core determinant of sustained corporate growth.

2. Emerging issues exposed in industry development: The cross-border operational chain has an inherent capital time lag, with procurement, production, logistics, and advertising spending incurred upfront and fixed platform reserve periods delaying settlements, causing a disconnect between top-line revenue and cash flow. As businesses scale, this structure easily leads to insufficient cash flow support. Meanwhile, the traditional financial system’s underwriting logic, which relies on financial statements and collateral, creates clear mismatches in credit assessment and information structure with the asset-light, data-driven, fast-window operational characteristics of cross-border e-commerce. In addition, many cross-border financing services rely on external capital, making them prone to service contraction during trade policy volatility and exacerbating corporate operational risks.

3. Innovative business models for industry services: Cross-border-tailored financial services are shifting toward a model of data-based underwriting, proprietary capital support, and scenario-specific product design. For example, Tianyi E-Commerce Bao builds risk control models by integrating merchant operational data, uses digital processes to improve approval efficiency, and designs dedicated products for distinct scenarios, aligning financing solutions with corporate operating cycles and providing a replicable path to resolve the mismatch issues of traditional financial services.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

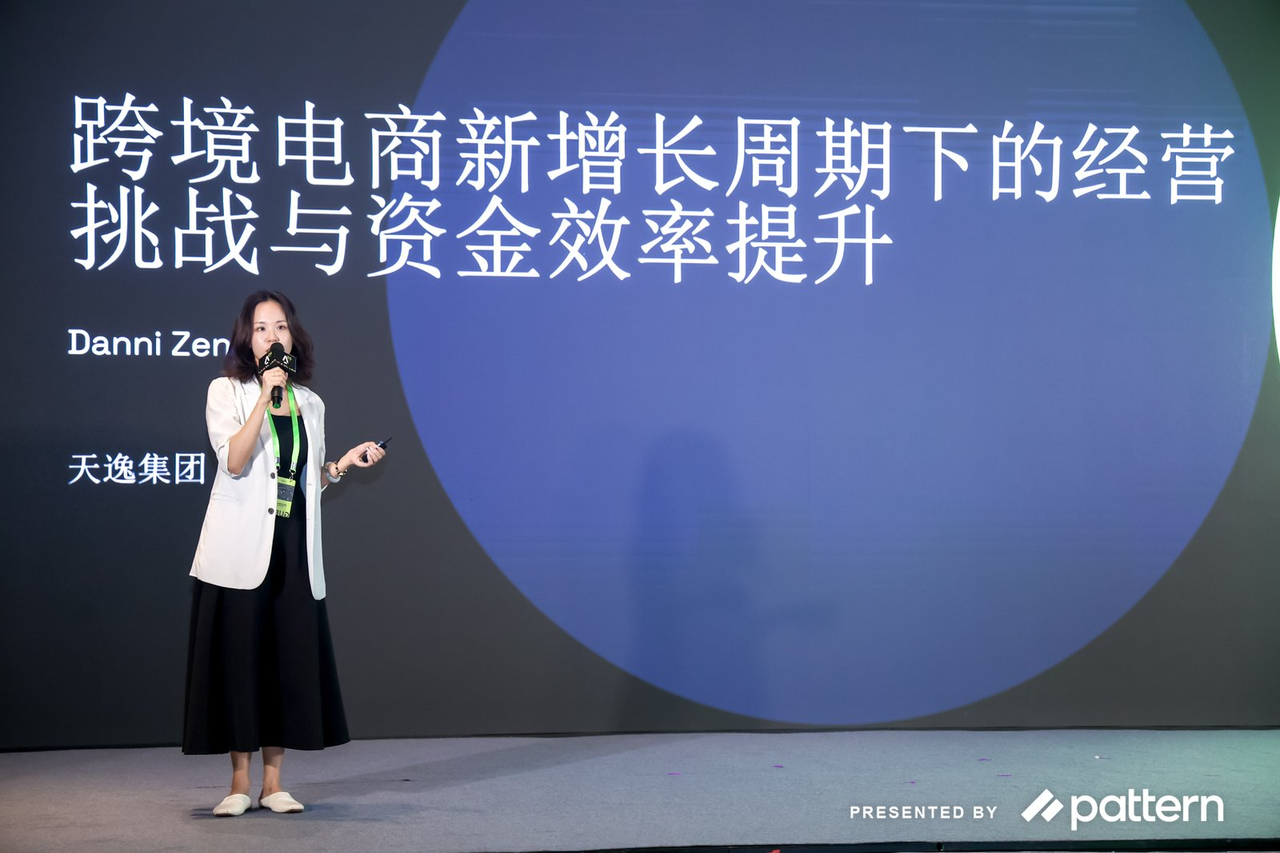
【亿邦原创】9月17日,在由Pattern栢藤主办、亿邦动力担任战略合作伙伴的“Accelerate26跨境生态加速大会·中国站”专题论坛二上,天逸集团市场与生态负责人Danni Zeng发表了题为《备战多渠道,钱从哪里来?》的演讲。

Danni Zeng指出,随着卖家规模扩大,企业面对的不再只是如何获得更多订单,还要解决如何支撑采购、备货、物流、广告及平台回款等整条经营链路的问题。

在她看来,规模化卖家数量增加、大促期间获客成本上升,以及平台回款节奏变化,正在共同压缩企业可以调度的现金空间。下一阶段的竞争,不只是在比谁更会卖货,也是在比谁能以更高的资金效率持续经营。

Danni Zeng表示,跨境企业的增长能力至少需要从流量、产品、供应链和资金效率四个方面衡量。资金效率并非财务部门的单独议题,其本质同样是经营效率。金融服务的价值也不应只体现在企业“缺钱”时提供资金,而应帮助企业协调采购、备货、广告投入和回款之间的时间差。

本文根据嘉宾现场演讲整理,在不影响原意的基础上有所删改。

以下为演讲实录:

01跨境电商新增长周期下的经营挑战与资金效率提升

跨境电商行业目前呈现出三点趋势:规模化卖家持续上升;大促获客成本走高,运营与广告预算分配更精细化;平台回款周期拉长,等待资金时间延长。

这就会导致,前端投入变大、后端回款变慢,企业可调度的现金空间被压缩。所以,接下来的竞争不只是比谁更会卖货,更是比谁能以更高效率持续经营。

根据亚马逊官方披露的数据,2025年前十个月,销售额超过1000万美元的中国卖家数量同比增长接近30%。这说明越来越多的卖家正在从中小规模进入更高体量级。

我们为什么要关注规模化卖家的增长?因为一家企业从一年几百万美元做到几千万美元时,面临的并不只是简单的销售增长。以前可能只需要备100万元的货,现在可能要备500万元甚至1000万元的货。与此同时,广告预算会变大,仓储、物流和人力成本也会随之增加。随着企业规模增长,经营的复杂程度也在提高。

这个时候,最容易被忽略的问题就是:现金流能不能支撑这样的增长?现在衡量一家跨境企业的增长能力,我认为至少要看四件事:流量、产品、供应链和资金效率。前三项大家已经非常熟悉。第四项“资金效率”,常常被认为只是财务部门的事情,但其实并不是。

有时企业的产品很好,广告效率也不错,但如果库存被压得太久,平台回款又比较慢,企业的增长同样会被卡住。因此,资金效率本质上也是经营效率。

02销售额不等于现金流,跨境生意存在天然的时间差

如果把一笔跨境生意拆开来看,就会发现资金存在一个天然的时间差。采购付款、生产备货和物流运输都发生在销售之前。订单完成以后,平台还要按照相应规则进行结算,资金才会真正回到企业账户。

以亚马逊的D+7政策为例,订单妥投后,相关资金还要经过七天预留期,才会转为可用余额。企业需要关注的不只是多等待了几天,更是从向供应商付款,到资金真正回到手中,整个经营周期占用了多长时间。

我们经常会遇到这样的情况:新一轮采购、备货和广告投入已经开始,上一轮销售产生的现金却还在路上。即使企业的销售额有所增长,也可能感觉现金越来越紧张。这正是销售额与现金流不同步带来的问题。

因此,我们理解的金融服务,不应该只在企业缺钱时才出现。更理想的方式,是提前看清企业的经营周期,在采购、备货、广告投入和平台回款之间,合理安排资金。融资本身不是目的。只有当它能够帮助企业接住订单、缩短等待时间并提高资金使用效率时,才具有真正的价值。

很多卖家可能会问,为什么传统融资方式有时跟不上跨境电商的经营节奏。原因在于,传统融资方式并不是天然围绕跨境电商场景设计的。传统授信可能更擅长评估财务报表、征信和抵押物,但对跨境卖家而言,真正具有价值的经营资产,往往更多体现在店铺销售、回款表现和库存周期等数据维度上。

同时,电商的经营窗口期非常短。如果审批速度和额度灵活度跟不上旺季节奏,即使资金最终获批,也可能已经错过了最需要使用的时间。这并不是说传统银行不好,而是传统金融体系与跨境电商之间,确实存在信用评价方式和信息结构的错配。

解决这种错配的关键,是让真实的经营数据进入授信判断。卖家授权后,系统可以同步店铺的销售和回款数据,再结合业务增长、库存、退货以及企业主体信用等信息,形成更贴近实际经营情况的评估。判断一家企业的经营质量,不能只看GMV,还要看经营是否稳定。对轻资产卖家来说,这意味着企业可以通过可验证的经营表现,获得与自身经营情况相匹配的资金支持。

03跨境专属信贷服务“天逸电商宝”:自有资金、线上流程、数据授信和场景化经验

基于这一思路,我们推出了“天逸电商宝”,希望针对跨境电商的具体经营场景,减少卖家的出口账期压力,提高整体经营效率。

目前,我们可以覆盖中国大陆、中国香港和部分海外主体,并支持人民币、离岸人民币、美元、日元等多币种需求。我们希望做到的是,让资金方案跟着企业的经营周期走,而不是让企业的经营周期迁就某一种固定的融资产品。

这套方案主要有三个特点:

第一,我们的业务使用自有资金,希望在资金来源和安排上保持相对稳定。

第二,产品使用方式比较灵活。我们支持多币种线上操作,不需要抵押物,主要根据企业的经营数据进行额度评估。据我们目前的实际业务情况,最高已经做到了2亿元人民币的融资。

第三,效率来自流程和数据。在资料完整、条件匹配的情况下,1000万元人民币以内的拨款最快可以实现T+0到账。也就是说,卖家上午确认所需额度和相关费用后,资金最快当天下午就可以到账。

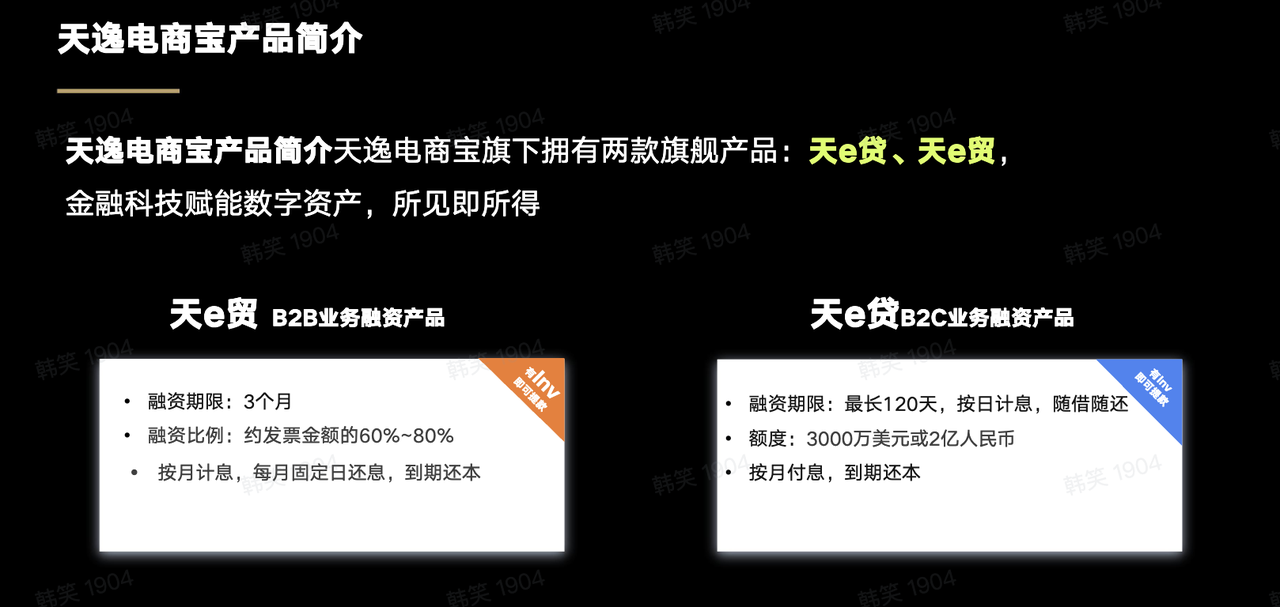
针对不同的经营需求,我们建立了两款产品体系:一款是面向B2B卖家的“天逸贸”,另一款是面向B2C卖家的“天逸贷”。

“天逸贸”采用保理模式。以亚马逊VC卖家为例,其经营周期可能比较长,经常会遇到货物已经交付、款项尚未到账的问题。针对这种情况,我们可以根据客户六个月的月均回款情况评估额度,最高按照月均回款的三倍计算,采用按月付息、到期还本的方式。

“天逸贷”主要面向B2C卖家,解决旺季备货、新品放量、库存周转和新平台布局等资金需求。它在使用上更加灵活,最长可以提供120天的期限,并支持按日计息、随借随还。

简单来说,账期问题可以考虑“天逸贸”,备货和周转问题可以考虑“天逸贷”。

从注册、额度授信到最后拨款,整个申请流程都可以在线完成。我们的目标是让所需材料更加清晰、办理进度更加透明。对符合条件的卖家,最快可以在当天完成相关流程的签署。

当然,企业在选择长期资金伙伴时,不会只看产品和参数,还要考虑服务能否持续。跨境电商是一个波动比较明显的行业,资金方是否理解行业的经营节奏,会直接影响后续的合作体验。

天逸集团深耕供应链金融和科技服务已有25年以上。过去,我们服务了一百多家银行及供应链金融机构,为其提供系统和风控服务。2023年,我们全球业务的发生量达到334亿美元,也曾获得央视新闻专题报道。

对我们来说,“天逸电商宝”并不是一款孤立的产品,而是把天逸在供应链金融、数据风控、跨境服务和资金安排方面积累的经验,放进跨境卖家的实际经营场景中。

不同资金渠道适合不同需求。银行在资金成本和体系方面具有优势,其他跨境资金服务商也各有自己的产品特点。天逸希望补充的是高频、数字化、经营节奏较快的跨境电商场景。

我们一直强调自有资金,是因为资金的稳定性对卖家非常重要。行业中的一些融资中介和科技公司依赖外部资金。当市场行情或者贸易政策发生变化时,外部资金方可能因为对行业缺乏足够了解而趋于保守,甚至停止投入。

2025年3月—4月,受到中美贸易摩擦影响,市场上一些银行和金融机构暂停了电商融资业务,部分卖家因此面临资金压力。因为天逸本身就是资金方,我们能够直接了解客户的具体经营情况,在那一阶段仍然持续为跨境企业提供资金支持。

“天逸电商宝”的特点可以概括为:自有资金、线上流程、数据授信和场景化经验。

卖家在选择资金合作伙伴时,可以重点比较四件事:资金是否稳定,审批速度能否赶上经营窗口,产品期限能否匹配回款周期,以及综合成本能否被相应的经营收益覆盖。当企业规模增长以后,需要管理的不只是销售额,还有资金在经营链路中流动的速度。

本文首发于 亿邦动力 官方网站

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

当前跨境电商卖家面临哪些资金层面的经营压力?

当前跨境电商行业规模化卖家数量持续增长,大促获客成本走高、广告运营预算分配更精细化,叠加平台回款周期拉长,导致前端投入加大、后端回款变慢,企业可调度现金空间被压缩,资金效率成为核心竞争维度。

传统融资方式为什么难以适配跨境电商的经营需求?

传统融资多围绕财务报表、征信、抵押物开展授信,未将跨境卖家核心经营资产如店铺销售、回款表现、库存周期等纳入评估,且审批速度、额度灵活度难以匹配跨境电商短经营窗口期、旺季备货节奏,存在信用评价错配。

天逸电商宝是一款什么产品?有什么优势?

天逸电商宝是天逸集团推出的跨境专属信贷服务,可覆盖多类经营主体、支持多币种申请,依托自有资金提供无抵押数据授信,最高融资额2亿元,1000万元以内拨款最快T0到账,分设适配B2B、B2C场景的产品,匹配卖家账期、备货周转等需求。

跨境卖家选择资金合作方需要重点考察哪些方面?

跨境卖家选择资金合作伙伴可重点考察四个维度:一是资金来源是否稳定,能否在行业波动期持续提供支持;二是审批速度能否匹配经营窗口期;三是产品期限是否适配回款周期;四是综合成本能否被对应经营收益覆盖。

这么好看,分享一下?

朋友圈 分享

APP内打开

+1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0