广告
加载中

酒业大变局:传统酒企集体过冬 散酒铺凭什么成为千亿“避风港”?

大椿 2026-06-04 13:37
大椿 2026/06/04 13:37

邦小白快读

EN
全文速览

本文核心信息是白酒行业整体下行的背景下,新式散酒铺异军突起,成为千亿级新赛道,核心干货整理如下:

1. 行业整体背景:2025年白酒行业全行业营收同比下滑7.5%,利润下滑13.3%,产量连续9年下滑,头部酒企也普遍出现业绩下滑,行业进入深度调整期。而散酒市场2025年已经突破千亿规模,年增速超过15%,成为行业新增长点。

2. 对普通消费者的价值:新式散酒砍掉了包装、广告、中间商的溢价,同等品质酒价仅为瓶装酒的1/5,几块钱就能尝鲜,还有上百种SKU涵盖低度果酒、风味酒、传统白酒,能满足年轻人日常微醺、悦己饮酒的需求,性价比更高。

3. 对想要创业的普通读者:新式散酒铺贴合社区消费,复购率能达到40%-60%,但也要注意,赛道竞争很快会进入红海,需要提前做好品质管控,规避同质化风险。

当前白酒行业进入深度调整期,散酒赛道成为品牌新的增量曲线,对应品牌商关注的干货整理如下:

1. 消费趋势变化:白酒消费已经转向年轻化、日常化、悦己化,年轻人不再为品牌溢价、包装溢价和社交应酬买单,更关注酒体本身的口感和性价比,日常悦己场景已经成为新的需求增长点。

2. 渠道与增长机会:散酒铺可以帮助品牌抢占社区高频消费场景,传统品牌入场散酒能够打破消费者对散酒低质的固有印象,还能盘活自身产能,开辟新的增长曲线,目前古井贡、口子窖等头部酒企已经开始布局。

3. 可借鉴的运营方向与风险提示:可以借鉴新式散酒“奶茶化”运营思路,推出多品类SKU适配多元需求,轻量化售卖降低试错成本;核心需要注意散酒全链路的品质管控,一旦出现品质问题,会牵连主品牌信誉,造成不可逆损失。

新式散酒是当前酒水零售赛道的高增长机会,对应卖家关注的机会、风险、经验整理如下:

1. 市场机会:当前白酒行业存量竞争,散酒赛道依托悦己消费的需求快速增长,2025年市场规模已经突破千亿,年增速超15%,目前赛道刚刚进入规范化发展阶段,还有充足的布局空间,而且散酒铺贴近社区,复购率高达40%-60%,现金流表现好。

2. 可学习的成功模式:沿用奶茶化运营逻辑,产品端布局上百种SKU,覆盖白酒、果酒、低度风味酒满足多元需求;售卖端按两、按杯销售,降低消费者试错成本;选址贴近社区,结合即时零售适配年轻人碎片化消费需求。

3. 风险提示:大量玩家入局后,赛道很快会进入红海竞争,容易出现同质化、价格内卷,单店盈利模型需要提前跑通;最核心的风险是品质管控,散酒储存、售卖环节容易出现卫生问题,会直接影响门店生存,需要做好全流程品控。

散酒赛道的爆发给酒水生产工厂带来了新的转型机会和发展方向,对应工厂关注的干货整理如下:

1. 产品生产与设计需求变化:当前消费者尤其是年轻消费者,需要适口性好、低度化、多元化的酒品,不再只偏好传统高度白酒,果酒、草本利口酒、风味啤酒等品类需求快速增长,工厂需要调整产品结构,适配多元化的市场需求。

2. 新商业机会:新式散酒铺普遍采用酒厂直达门店的模式,砍掉了多层中间商,工厂可以直接对接连锁散酒品牌直供基酒和成品,减少渠道分流,提升自身的利润空间;随着大量品牌布局散酒业务,2026年散酒市场的产能需求会进一步释放,给上游工厂带来更多订单。

3. 转型启示:工厂需要提升供应链的稳定性和全链路品控能力,才能满足连锁散酒品牌的标准化要求,建立长期稳定的合作;同时可以依托自身产能,开发面向日常悦己消费的散酒产品线,开辟新的增长曲线,对冲传统瓶装酒需求下滑的影响。

散酒赛道从小散乱向规范化、品牌化、连锁化转型,给服务商带来了新的市场机会,对应干货整理如下:

1. 行业发展趋势:散酒市场2025年已经突破千亿规模,年增速超过15%,目前传统酒企、新锐品牌、跨界玩家纷纷入场,赛道正式进入“正规军”竞争时代,大量新老玩家对专业服务的需求快速增长,比如口子窖已经公开招标整合营销服务商。

2. 核心客户痛点:当前散酒行业玩家普遍面临三类核心痛点,一是品质管控难度大,散酒在生产、运输、储存、零售环节都容易出现卫生不达标、品质参差不齐的问题;二是同质化竞争严重,缺乏差异化的产品和运营方案;三是跨区域扩张时,缺乏标准化的供应链和门店管理体系。

3. 解决方案与机会:服务商可以针对这些痛点,开发对应服务产品,比如推出散酒储存消毒的标准化解决方案,为品牌提供产品研发、营销推广、连锁运营管理、供应链整合等服务,帮助玩家解决核心问题,分享赛道增长红利。

散酒赛道的兴起给零售平台带来了新的增长点,对应平台商关注的干货整理如下:

1. 行业对平台的核心需求:新式散酒品牌走连锁化、社区化、即时化的路线,需要平台提供贴近社区的流量入口、成熟的即时配送体系,以及线上线下融合的零售基础设施,匹配年轻人碎片化、即时化的消费习惯。

2. 平台可布局的方向:平台可以依托自身的门店网络和流量优势,布局自营散酒铺,或者开放招商引入新锐散酒品牌,丰富自身的酒水品类,拉动销售增长,目前盒马已经开出首家自营酒铺,茶咖平台也在纷纷布局,验证了模式的可行性。

3. 运营与风险规避提示:平台需要建立严格的散酒品控标准,加强对入驻品牌和产品的品质管控,避免品质问题影响平台整体信誉;同时需要合理规划门店和品牌布局,避免同一区域过度开店导致同质化价格内卷,要引导品牌做差异化场景运营,提升整体盈利能力。

散酒赛道的兴起是白酒产业转型过程中的重要新动向,对应研究者关注的干货整理如下:

1. 产业新动向:当前白酒行业整体进入深度调整期,全行业营收利润连续下滑,头部酒企也出现增长停滞,而散酒赛道依托消费趋势变化快速崛起,2025年市场规模突破千亿,年增速超15%,成为白酒行业新的增长曲线,目前已经吸引传统酒企、新锐品牌、跨界玩家多方入局,2026年将进入全面竞争阶段。

2. 新商业模式总结:新式散酒铺打破了传统白酒的运营逻辑,采用“奶茶化”零售思路,砍掉中间环节和品牌包装溢价,核心是让消费者为酒体本身付费,依托社区门店和即时零售,适配年轻人悦己化、日常化的饮酒需求,重构了白酒零售的价值体系。

3. 新行业问题与研究方向:当前散酒行业已经出现同质化内卷的苗头,散酒本身品质管控难度远高于瓶装酒,行业从小散乱向规范化转型过程中,需要解决标准化品控、可复制盈利模型等问题,后续行业将经历市场出清,其发展过程对研究新消费改造传统产业具备典型的研究价值。

返回默认

声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

Against the backdrop of an overall downturn in China’s baijiu (Chinese liquor) industry, a new type of bulk baijiu retail store has emerged as a fast-growing new market segment worth over 100 billion yuan. Key takeaways are as follows:

1. Industry background: In 2025, the overall baijiu industry recorded a 7.5% year-on-year drop in revenue and a 13.3% drop in profit, with production declining for 9 consecutive years. Even leading baijiu players generally saw performance declines, putting the industry in a deep adjustment period. By contrast, the bulk baijiu market surpassed 100 billion yuan in scale in 2025, with an annual growth rate exceeding 15%, making it the industry’s new growth driver.

2. Value for general consumers: New-style bulk baijiu eliminates premiums from packaging, advertising and middlemen, resulting in prices equal to just one-fifth of bottled baijiu of the same quality. Consumers can try new products for just a few yuan, and there are over 100 SKUs covering low-alcohol fruit wine, flavored liquor and traditional baijiu, meeting young people’s demand for daily casual drinking for personal enjoyment, with far better value for money.

3. Notes for aspiring entrepreneurs: New-style bulk baijiu stores target community consumption and achieve repeat purchase rates between 40% and 60%. However, the segment will quickly become a red ocean of competition, so operators must establish strict quality control in advance to avoid the risk of homogenization.

China’s baijiu industry is now in a period of deep adjustment, and the bulk baijiu segment has become a new growth curve for established brands. Key insights for brand owners are as follows:

1. Shifting consumer trends: Baijiu consumption is becoming younger, more daily-oriented and focused on personal enjoyment. Young consumers are no longer willing to pay for brand and packaging premiums for social drinking, and instead prioritize taste and value for money of the liquor itself. Daily personal consumption has become a new source of demand growth.

2. Channel and growth opportunities: Bulk baijiu stores allow brands to capture high-frequency community consumption scenarios. When established traditional brands enter the bulk baijiu market, they can help overcome consumers’ long-held stereotype that bulk liquor is low-quality, while also utilizing idle production capacity and opening up a new growth curve. Leading players including Gujing Gong and Kouzijiao have already entered the space.

3. Usable operational strategies and risk warnings: Brands can adopt the "milk tea-style" operation model common to new-style bulk baijiu stores, launching a wide range of SKUs to meet diverse demand and using lightweight sales models to lower trial costs. The core priority is strict end-to-end quality control for bulk products—any quality issue will damage the reputation of the core brand and cause irreversible losses.

New-style bulk baijiu is a high-growth opportunity in today’s alcohol retail segment. Key opportunities, risks and insights for retail sellers are as follows:

1. Market opportunity: The overall baijiu market is now defined by stock competition, while the bulk baijiu segment is growing rapidly driven by rising demand for personal consumption. It surpassed 100 billion yuan in scale in 2025, with annual growth exceeding 15%, and is just entering the standardized development stage, leaving plenty of room for new entrants to establish a footprint. In addition, bulk baijiu stores are located close to residential communities, achieve repeat purchase rates of 40% to 60%, and generate strong cash flow.

2. Proven successful models to adopt: Sellers can follow the milk tea-style operation logic: offer over 100 SKUs covering traditional baijiu, fruit wine and low-alcohol flavored liquor to meet diverse demand; sell by the 50g portion or by the cup to lower consumers’ trial cost; locate stores close to communities and integrate with instant retail to fit young consumers’ fragmented consumption habits.

3. Risk warnings: As a flood of new players enter the market, the segment will quickly become a red ocean, prone to homogenization and price wars. Sellers must validate a profitable single-store model before expanding. The most critical risk is quality control: bulk liquor is vulnerable to hygiene issues during storage and sales, which can directly threaten a store’s survival, so end-to-end quality management is essential.

The boom in the bulk baijiu segment has brought new transformation opportunities and development directions for alcohol production factories. Key takeaways for manufacturers are as follows:

1. Shifts in product design and production demand: Today’s consumers, especially younger drinkers, demand good-tasting, low-alcohol and diverse liquor products, rather than only preferring traditional high-proof baijiu. Demand for fruit wine, herbal liqueurs and flavored beer is growing rapidly, so factories need to adjust their product mix to adapt to diversified market demand.

2. New business opportunities: Most new-style bulk baijiu brands use a direct-to-store model from distilleries, cutting out multiple layers of middlemen. Factories can directly supply base liquor and finished products to chain bulk baijiu brands, reducing channel diversion and increasing their own profit margins. As a growing number of brands expand their bulk liquor businesses, production demand in the bulk market will further increase in 2026, bringing more orders to upstream factories.

3. Transformation insights: Factories need to improve supply chain stability and end-to-end quality control capabilities to meet the standardization requirements of chain bulk baijiu brands and establish long-term stable partnerships. At the same time, they can leverage their existing production capacity to develop their own bulk liquor product lines targeting daily personal consumption, opening up a new growth curve to offset falling demand for traditional bottled baijiu.

The bulk baijiu segment is transforming from a fragmented, unregulated market to a standardized, branded, chain-based industry, bringing new market opportunities for service providers. Key insights are as follows:

1. Industry development trends: The bulk baijiu market surpassed 100 billion yuan in scale in 2025, with an annual growth rate exceeding 15%. Traditional baijiu enterprises, new brands and cross-industry entrants are all rushing into the market, and the segment has officially entered an era of competition among professional, large-scale players. Demand for professional services from the flood of new and existing players is growing rapidly—for example, Kouzijiao has already launched public tenders for integrated marketing services.

2. Core pain points of clients: Bulk baijiu players generally face three core pain points: First, quality control is difficult, as bulk liquor is prone to unhygienic conditions and inconsistent quality across production, transportation, storage and retail links. Second, homogenized competition is severe, with a lack of differentiated products and operation strategies. Third, players lack standardized supply chain and store management systems when expanding across regions.

3. Solutions and opportunities: Service providers can develop targeted service products to address these pain points, for example by developing standardized solutions for bulk liquor storage and disinfection, and offering product development, marketing, chain operation management and supply chain integration services to help players solve core problems and capture a share of the segment’s growth dividend.

The rise of the bulk baijiu segment has brought new growth opportunities for retail platforms. Key takeaways for platform operators are as follows:

1. Core industry demand from platforms: New bulk baijiu brands pursue a chain-based, community-focused, on-demand model, requiring platforms to provide community-focused traffic access, mature instant delivery infrastructure, and integrated online-offline retail infrastructure to match young consumers’ fragmented, on-demand consumption habits.

2. Viable expansion directions for platforms: Leveraging their existing store network and traffic advantages, platforms can launch self-operated bulk baijiu stores, or open up merchant recruitment to attract new bulk baijiu brands, enriching their alcohol category mix and driving overall sales growth. Fresh retail platform Hema has already opened its first self-operated liquor store, and tea and coffee platforms are also entering the space one after another, proving the model’s feasibility.

3. Operation and risk mitigation guidance: Platforms need to establish strict quality control standards for bulk liquor, and strengthen oversight of the quality of入驻 brands and products, to avoid quality issues damaging the platform’s overall reputation. They also need to rationally plan store and brand layout to avoid over-expansion in the same region that leads to homogenized price competition, and guide brands to carry out differentiated scenario-based operations to improve overall profitability.

The rise of the bulk baijiu segment is a notable new development in the evolution of China’s baijiu industry. Key insights for industry researchers are as follows:

1. New industry development: The overall baijiu industry is currently in a deep adjustment period, with overall industry revenue and profit declining consecutively, and even leading baijiu enterprises facing stagnant growth. By contrast, the bulk baijiu segment has risen rapidly driven by shifting consumer trends, surpassing 100 billion yuan in scale in 2025 with an annual growth rate exceeding 15%, becoming the new growth curve for the overall baijiu industry. It has already attracted entrants from traditional baijiu enterprises, new emerging brands and cross-industry players, and will enter a period of full-scale competition in 2026.

2. Summary of the new business model: New-style bulk baijiu stores break the operation logic of traditional baijiu, adopting a "milk tea-style" retail approach that cuts out middlemen and brand packaging premiums. Its core value proposition is getting consumers to pay for the liquor itself rather than added premiums. By leveraging community stores and instant retail, it meets young consumers’ demand for daily, personal-oriented drinking, and has reconstructed the value system of baijiu retail.

3. New industry issues and research directions: The bulk baijiu industry is already showing early signs of homogenized price competition. Quality control for bulk liquor is inherently far more difficult than for bottled liquor, and as the industry transforms from a fragmented, unregulated market to a standardized one, it needs to solve problems including standardized quality control and replicable profitable business models. The industry will go through a market consolidation phase in the coming period, and its development process offers significant research value for studying how new consumer trends transform traditional industries.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

散酒铺的核心竞争力不是便宜,而是“让消费者为酒体本身付费”的透明逻辑。

作者 | 大椿

编辑 | 杜仲

来源 | 观潮新消费(ID:TideSight)

白酒行业集体过冬的当下,散酒铺的生意却火了。

国家统计局所发布的数据显示,2025年整个白酒行业的营收和净利润继续下行,销售收入5724亿,同比下滑7.5%;利润总额1,884亿,同比下滑13.3%,白酒产量更是连续第九年下滑。

头部酒企的日子也不好过,茅台在2025年出现了上市24年以来首次营收和净利润双降,五粮液的营收和净利润腰斩有余,泸州老窖同样出现过去10年来的首次营收和净利润双降,上海贵酒甚至成了行业内的第一家退市企业。

当白酒行业进入深度调整期,价格倒挂、渠道承压、动销放缓成为行业共识,散酒这种曾被视为低端、过时的业态重新出现在街头巷尾,并迅速翻红。结合川酒集团发布的数据,2024年国内散酒市场规模已经超过800亿元,年增速超过15%,2025年已成功突破千亿大关。

从短期看,散酒铺是酒企应对存量竞争的“战术武器”。中长期看,散酒铺的火,本质是白酒消费年轻化、日常化、悦己化的缩影,谁先把产品力、供应链、食品安全、会员体系跑通,谁就能把散酒做成真正的增量曲线。

“老登”白酒没人喝,散酒铺接棒

传统散酒即散装白酒,一杯可卖,几斤可打,生意灵活,但客单价不高,主要做的是头客复购的生意。传统散酒铺并不少见,大多分布在集贸市场、社区周边,靠质优价廉的口粮酒满足老酒友。

散酒铺生意模式的变化,大约始于2023年。这一年,唐三两在成都开出首家门店,主打新中式风格,定位“年轻人的口粮酒”。这家“奶茶化”的散酒铺迅速引发年轻人关注,结合其官方数据,截止到2025年底已经在全国开出了138家门店。

另一边,成都本土品牌李不愁打着“人生有酒,何必言愁”的川式生活哲学上场,更是在短短半年内,就扩张至50家,单店日均客流超100人,复购率高达60%;由元气森林创始人唐彬森联合创立的斑马侠,目前旗下也已有140家门店。

除此之外,还有脸红熊猫、关爷打酒等一众新锐打酒铺品牌正以高颜值门店、全品类酒单和丰富的互联网营销手法,加速跑马圈地。

真正引爆赛道的,是传统酒企的入场。2025年底古井贡酒在老家杭州开出了首家线下直营打酒铺,采取“即打即喝”的方式,在很大程度上降低了消费者的体验门槛。大品牌卖散酒,从根本上打破了消费者对于“低价=低质”的传统印象。

随后,口子窖推出“口子酒坊打酒铺”,并于今年初在官网发布了整合营销服务商的招标公告,试图通过直营散酒铺来抢占社区高频场景,为品牌长期增长构建稳固基础。

此外,结合宋河酒业、川酒集团等在线下推动散酒业务来看,2026年散酒市场或将迎来一场巷战。

赛道风起,跨界品牌也闻风而动,其中最引人注目的莫过于以3亿金额被蜜雪冰城拿下的“鲜啤福鹿家”。截止到今年2月底,福鹿家在全国的门店数量已经突破2000家;2024年4月,茶颜悦色推出小酒馆品牌“昼夜诗酒茶·艺文小酒馆”;刚刚过去的5月29日,首家盒马酒铺(HEMA DRAFT BAR)在徐州盒马鲜生门店开业。据悉,目前瑞幸咖啡、茶百道等茶咖品牌也在蠢蠢欲动。

老酒企带着品牌积淀和产能入局,新锐品牌靠着模式创新和资本助推快速起量,跨界玩家用新茶饮的逻辑赋能酒饮零售……无论是快速增长的整体市场规模,还是白酒巨头纷纷押注,都在证明,打酒铺这门老生意,如今真的翻红了。

不过让人疑惑的是,唐三两超100个SKU中白酒产品的占比达35%、斑马侠中含有白酒的品类占比也在20%以上,盒马酒铺中白酒SKU约占一半……为什么传统酒企做不好的白酒,换个马甲就能够备受追捧呢?

拒绝溢价,重构饮酒新趋势

散酒铺为什么火?答案藏在消费人群迭代、渠道变革与产业结构重塑的三重共振里。

先来看消费人群。中国酒业协会《2025中国白酒市场中期研究报告》显示,35~55岁消费者在白酒群体中占比约65%~70%,贡献了七成以上销售额;里斯咨询也指出,35岁以上人群占据了高端白酒市场90%的份额。

这组数据让大家理所当然地认为:年轻人不喝白酒。但他们只是拒绝“为别人喝酒”。据中华网财经在2025年底的调研,18-40岁人群白酒选择率达46.94%,仅次于精酿啤酒排在第二位。

与传统“商务、社交”的白酒饮用场景不同,年轻人举杯的动机已经从“为别人喝”转向“为自己喝”,“快乐”“放松”“治愈”成为喝酒的高频关联词。换而言之,微醺经济之下,情绪价值正成为饮酒的核心驱动力。

《2024年中国酒水行业洞察报告》也在佐证,消费者买酒最关注的要素中,口味口感占比过半,位居第一,其后才是品质、品牌和性价比。青梅酒、精酿鲜啤等品类热销,本质上都在证明一件事,适口性更好、饮用门槛更低的酒,才是年轻人想要的酒。

当“喝酒”回归了“酒”本身,消费理性回归,购买行为随之发生改变。

年轻消费群体在选择白酒时也不再迷信品牌效应,而是更关注适口性以及性价比,量大管饱、好喝不贵。如在小红书等社媒平台上搜索“年轻人酒品推荐”,爆款种草笔记往往更加倾向于口感与价格,不再盲目追捧知名品牌,散酒成为消费结构调整下的直接受益者。

在供给端,散酒铺正在用“奶茶”的思路卖酒,以迎合年轻人。

第一招,卷口味创新,上百种SKU让选择自由。

散酒铺子深度嫁接小酒馆经营逻辑,形成”精酿+新酒饮+原酒散酒”的产品结构,既契合年轻群体多元化饮酒需求,又打破了传统散酒单一售卖的刻板印象。

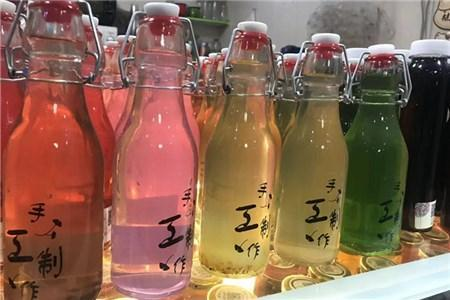
比如,唐三两旗下产品覆盖白酒、啤酒、果酒、米酒和洋酒等多个品类,低度酒大多维持在3~12度之间;斑马侠推出了果味啤酒、花果茶酒等创新产品,还和劲牌联合研发出草本利口酒;传统酒企中如古井贡酒打酒铺引入特色养生酒和发酵果酒等多元品类,兼顾健康和口味创新……上百种SKU,给消费者充分的选择权。

这种新模式对年轻人的吸引力远超预期。披露数据显示,斑马侠85%用户年龄集中在20~35岁之间,女性占比超50%;唐三两30岁以下客群占比最高,达到36%,男女性别比例几乎持平(男性51%,女性49%)。这表明,散酒铺不仅俘获了年轻人,还打破了酒饮的性别壁垒。

第二招,卷购买方式,主打一个“亲民”。过去买酒,要么整瓶,要么餐饮消费,一瓶酒的价格中,包装、广告和中间商占了大头。而散酒铺按两、按杯售卖的“轻量化”购买方式,让消费者几块钱就能轻松尝鲜,直接降低了消费者的试错成本,再加上酒厂直达门店的模式,砍掉了中间环节,将性价比拉到极致。

以唐三两为例,其通过直连全球酒厂的方式买基酒,可以直接将酒体成本占比从行业平均15%提升至70%。同等品质的白酒价格,店内售价仅为瓶装酒的1/5。“3块钱2两白,10块钱喝到微醺”,对于年轻人无疑有着巨大的吸引力。

第三招,不止是卖酒,更要卖“随时随地想喝就喝”的自由。

这一方面得益于散酒铺的渠道特性。数据显示,全国售卖散酒的零售终端在50万个以上,贴近生活社区售卖。这就意味着年轻人能像买杯奶茶一样走进散酒铺,花几块钱打一二两酒,或自己小酌,或喊朋友聚会,或者干脆拿回家做一杯特调鸡尾酒,冰着喝、调了喝,怎么自在怎么来。

同时,随着即时零售爆发,线上线下融合打破了时间与空间限制,不仅突破传统门店1-3公里经营半径,还和线下门店短平快的消费流程形成互补。线下购买过程压缩为"路过-进店-打酒-离开"的5分钟闭环,搭配线上配送服务体系,精准匹配年轻人碎片化、即时化的生活方式,让散酒融入随时取悦自己的日常。

供需双向奔赴之下,散酒铺连锁品牌成为高复购率赛道。官方数据显示,斑马侠的老客户月复购率基本维持在60%左右,唐三两也有40%,后者的创始人李孟龙曾公开表示“高频复购”是其核心指标。年轻人喝酒不为应酬,只为悦己,正在打开酒行业新的增长空间。

千亿蓝海,进入“正规军”时代

散酒铺真是稳赚不赔的生意吗?答案显然是否定的。

从行业基本面来看,散酒凭借灵活购买、性价比突出等优势,在下沉市场拥有庞大的消费群体,属于"低头捡钢镚"的赛道。但长期以来,这个赛道以小作坊、前店后厂、个体采买为主,长期面临着“低端、低价、低品质”的发展困境。

如今,在大牌入局和理性消费思潮的双重驱动下,散酒产业向规范化、品牌化、连锁化演进已成必然。然而,越是风口,越需冷静,曾经的奶茶、咖啡市场,同样经历了从野蛮生长到资本扎堆、再到红海厮杀、最终逐渐出清的完整周期,散酒赛道正在复刻这一轨迹。

最直观的是,散酒赛道竞争终将走向红海。

新式散酒铺是一门薄利多销的生意,当行业博弈加剧,价格战、同质化竞争、门店密度内卷将接踵而至,单店盈利模型能否跑通仍是未知数。以成都玉林西路为例,几百米的街道开出来唐三两、鲜啤福鹿家、皮浪精酿等多家散酒铺,SKU、装修风格几乎没有太大差异,在此现状下只能靠低价争抢消费者。

更隐形但致命的危机在于品质把控。相比瓶装酒,散酒的生产、运输和销售等环节更难规范,容易出现品质参差不齐、卫生不达标等问题。常见问题在于,一旦散酒铺的打酒枪头里面有残留,就极易产生细菌污染,更不用说散装酒桶未定期消毒、因阳光直射使得储存条件不达标等安全风险。

对于企业而言,一旦散酒出现品质问题,不仅会影响散酒业务本身,更会牵连主品牌的信誉,造成不可逆的损失。

“正规军”时代,散酒铺的打法不妨借鉴瑞幸“奶茶化”思路,将竞争核心转移到产品力建设、供应链优化与商业模式等方面。

首先,产品力:让白酒变“好喝”,完成尝新到复购的转化。被称为“爆品制造机”的瑞幸,曾通过生椰拿铁、橙C美式等爆款推动咖啡从“苦酸的舶来品”变为“更好喝的饮品”。散酒铺同样可以延续这一思路——通过添加消费者熟悉的爆款风味,去辛辣化、添适口,降低尝鲜门槛,确保新品的确定性放量。

其次,标准化:让散酒变“靠谱”,建立起即饮散酒铺不是低价、消费降级的“将就之选”,而是传统名酒在商超货架上“小份平移”的消费认知。

信任来源于对供应链的把控:优质原料产区的采购布局、中游基地的产能稳定供应以及下游门店网络的支撑。只有稳定高效的供应链,依托全链路精细化品控,才能改变“低价内卷、品质失焦”的乱象。

第三,场景化:从卖酒向卖生活方式转型,避免产品同质化。当产品趋同时,场景体验成为差异化关键,选址即是定位、人群即是生意,场景内的体验、品鉴、互动设计是连锁发展的核心命题。

第四,长期主义:让规模变“扎实”,搭建可复制的盈利模型。奶茶咖啡品牌的发展史启示我们,新消费短期拼价格,中期和长期所比拼的,从来都是品质和产业链的“内功”。

在供应链管理上能否建立如头部茶饮品牌般的成本壁垒?当门店突破区域向全国扩张时,产品结构能否有效适配,管理半径能否支撑?因此必须从单店思维走向连锁思维,搭建可复制、可扩张的盈利模型,通过多业态组合与系统化加盟体系,实现规模化健康发展。

二十年前,奶茶用“即买即走”颠覆了茶饮行业;十年前,瑞幸用“快咖啡”重构了咖啡认知;今天,散酒铺正在用同样的逻辑,让白酒从“礼品柜里的摆件”变成“冰箱里的日常”。

散酒铺的核心竞争力不是便宜,而是“让消费者为酒体本身付费”的透明逻辑。当“正规军”全面入场,比拼的不再是谁跑得快,而是谁站得稳、做得久。

注:文/大椿,文章来源:观潮新消费(公众号ID:TideSight),本文为作者独立观点,不代表亿邦动力立场。

文章来源:观潮新消费

广告
微信
朋友圈

这么好看,分享一下?

朋友圈 分享

APP内打开

赞 +1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0