广告
加载中

AI时代 跨境电商服务商的增量空间在哪里?

亿邦智库 2026-09-17 10:21
亿邦智库 2026/09/17 10:21

邦小白快读

EN
全文速览

这篇文章核心拆解了AI时代跨境电商服务商领域的结构性变化与增量机会,信息清晰直白,能帮助普通读者快速看懂跨境电商行业的AI发展风向。

1. 首先是行业正在发生的明确变化:电商平台AI工具快速普及,过去一年仅亚马逊第三方卖家就借助生成式AI创建超1200万条可售商品Listing,基础运营服务愈发标准化,57.3%的服务商已感受到明显生存压力,靠重复性人工执行的传统服务模式正在被淘汰。

2. 其次是值得关注的新趋势:AI正在改变消费者的购物路径,数据显示被ChatGPT推荐的品牌7天内获得网站访问的概率是未被推荐品牌的2.5倍,未来商品内容需要适配AI的理解逻辑才能获得更多流量。

3. 最后是当前行业格局:目前仅12.6%的服务商达到AI能力成熟期,近9成服务商仍处于零散尝试工具或初步应用AI的阶段,未来懂AI和不懂AI的服务商差距会持续拉大。

文章披露的AI时代跨境电商行业变化,能为品牌开展跨境布局、营销优化、用户运营提供明确的方向参考。

1. 首先是消费行为与流量的核心变化:AI已经重构消费者发现商品的路径,出现在ChatGPT推荐中的品牌7天内获得网站访问的可能性是未被推荐品牌的2.5倍,品牌做跨境运营不能只做传统的详情页优化,需要把产品价值、应用场景、用户体验按照AI可理解、可调用、可信任的逻辑搭建商品内容体系,才能拿到AI推荐的新增流量。

2. 其次是服务合作的选择方向:当前卖家对AI服务的需求已经从尝鲜转向解决实际痛点,80.6%的卖家需要和自身品类、业务场景深度绑定的AI方案,超半数卖家愿意开放业务数据共创专属模型,近4成偏好按效果付费的合作模式。品牌可根据自身阶段选适配服务:小型品牌选普惠标准化AI工具补基础能力,中腰部品牌选垂直场景AI服务打造单点优势,头部品牌可深度定制专属AI决策模型构建竞争壁垒。

文章清晰点明了AI时代跨境卖家面临的经营变化、风险点与增长机会,可直接指导卖家的AI工具选型与业务布局。

1. 首先是需要警惕的经营风险:电商平台AI工具快速普及,过去一年亚马逊第三方卖家用AI生成超1200万条Listing,基础运营环节的可替代性大幅增强,如果卖家还停留在用AI做基础商品信息生成的浅度应用阶段,很难构建差异化优势,会陷入产品同质化、运营成本高、溢价能力弱的困境。

2. 其次是明确的流量增长机会:AI重构了流量分配逻辑,获得ChatGPT等AI工具的推荐能让品牌7天访问量达到未被推荐品牌的2.5倍,卖家需要尽快搭建适配AI理解逻辑的商品内容体系,抢占AI推荐流量。

3. 最后是高性价比的合作方向:卖家不需要盲目采购通用AI工具,80.6%的高价值AI方案是和品类、业务场景深度绑定的,卖家可按自身规模选服务:小卖家选普惠标准化工具补能力短板,中腰部卖家选垂直场景服务打造单点优势,大卖家可开放业务数据和服务商共创专属模型,优先选择按效果付费的合作模式降低投入风险。

文章披露的跨境电商AI发展趋势,能为工厂开展跨境电商布局、推进数字化升级、适配新渠道需求提供清晰的行动参考。

1. 首先是跨境渠道的新需求方向:当前AI正在重构跨境电商的流量规则,商品能否被AI识别、推荐成为获取流量的关键,工厂布局跨境线上渠道时,产品的卖点设计、场景描述、详情页内容不能只适配人类消费者的阅读习惯,还要按照AI可理解、可调用、可信任的逻辑梳理产品价值与应用场景,才能拿到AI推荐的新增流量,获得2.5倍于普通商品的访问机会。

2. 其次是数字化升级的可行路径:工厂做跨境电商不需要盲目投入重金搭建全套AI系统,可根据自身规模选择适配的AI服务:规模较小的工厂可先用标准化普惠AI工具补足基础运营能力,有一定跨境基础的中腰部工厂可选择垂直场景的AI服务打造爆款单品优势,规模较大的工厂可开放供应链与运营数据,和服务商共创专属模型,靠智能决策构建竞争壁垒,避开同质化价格战。

文章系统拆解了AI时代跨境电商服务商面临的行业变局、客户痛点与增量机会,为服务商的能力升级与业务布局指明了方向。

1. 首先是必须正视的行业生存压力:当前电商平台AI工具快速普及,过去一年亚马逊第三方卖家用AI生成超1200万条Listing,基础运营服务标准化程度快速提升,57.3%的服务商已经感受到明显生存压力,61.7%的服务商预判懂AI和不懂AI的同行差距会持续拉大,仅靠重复性执行获取价值的服务模式将持续面临挑战。

2. 其次是清晰的客户需求变化:当前卖家的AI诉求已经从简化运营转向智能增长,80.6%的卖家需要和自身品类、业务场景深度绑定的AI方案,76.2%的卖家关注AI方案能否解决实际问题,52.9%的卖家愿意分享业务数据共创模型,38.4%的卖家偏好按效果付费的模式;从客户分层看,中腰部卖家是未来三年AI需求增长最快的群体,小卖家需要标准化普惠工具,头部卖家需要深度定制方案。

3. 最后是分层发展的可行路径:起步期服务商可先用标准化工具切入小卖家市场积累经验,成长期服务商可深耕垂直场景卡位中腰部卖家,成熟期服务商可凭全栈能力覆盖全客群。

文章披露的跨境电商AI发展趋势与卖家、服务商的行为变化,能为平台优化生态建设、开展招商运营、做好风向规避提供决策参考。

1. 首先是平台生态内的明确变化趋势:当前平台内置AI工具的普及已经大幅提升运营效率,过去一年仅亚马逊平台就有第三方卖家用生成式AI创建超1200万条商品Listing,基础运营服务标准化程度持续提升,超半数服务商感受到生存压力,平台需要引导服务商向高价值的差异化服务升级,避免低质同质化服务扰乱生态。

2. 其次是平台商家的核心诉求变化:当前商家的AI需求已经从功能尝鲜转向实际增长,超八成商家需要和自身品类、业务场景深度绑定的AI能力,超半数商家愿意共享业务数据训练适配自身场景的模型,近四成商家偏好按效果付费的服务模式;同时AI重构了流量路径,被AI推荐的品牌能获得2.5倍的访问量,商家普遍需要适配AI逻辑的内容建设指导。

3. 最后是生态建设的优化方向:平台可以针对不同规模商家分层匹配AI服务资源,引入不同能力层级的服务商,完善数据安全与效果保障机制,提升整个生态的运营效率。

这篇基于206份服务商有效样本、结合平台运营数据与第三方研究结论的行业报告,呈现了AI时代跨境电商服务产业的新动向、新结构与新模式,具备较高的研究参考价值。

1. 首先是产业出现的结构性新变化:供需两端正在推动服务商市场重构,供给端电商平台AI基建快速完善,基础运营服务标准化程度提升,持续挤压传统服务的价值空间;需求端卖家的AI诉求从简化运营转向智能增长,从功能尝鲜转向场景深耕,从单项服务采购转向深度数据共创、效果分成的绑定模式,80.6%的卖家需要场景化深度绑定的AI方案,52.9%的卖家愿意共享数据训练专属模型。

2. 其次是产业形成的分层新格局:当前服务商AI能力呈金字塔分化,56.3%处于零散尝试工具的起步期,31.1%处于核心业务应用AI的成长期,仅12.6%进入可对外输出AI产品化能力的成熟期;需求端也出现分层,中腰部卖家是未来三年AI需求增长最快的客群,占比达52.4%,头部、小卖家的需求占比分别为32%、15.5%,能力分层匹配客群分层的新竞争格局正在形成。

3. 此外AI驱动的流量规则变化、数据共享中的安全保障等新问题,也具备持续跟踪研究的价值。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

This article breaks down the structural shifts and emerging growth opportunities in the cross-border e-commerce service provider sector amid the AI era, with clear, straightforward insights that help general readers quickly grasp how AI is reshaping the industry.

1. First, the tangible changes underway across the sector: AI tools built into e-commerce platforms are spreading rapidly. Over the past year alone, third-party sellers on Amazon have used generative AI to create more than 12 million sellable product listings. Basic operational services are becoming increasingly standardized, and 57.3% of service providers are already reporting significant survival pressure, as traditional service models relying on repetitive manual work are being phased out.

2. Second, the noteworthy new trends: AI is reshaping consumer shopping journeys. Data shows that brands recommended by ChatGPT are 2.5 times more likely to drive website traffic within seven days than brands without such recommendations. Going forward, product content will need to align with AI comprehension logic to capture greater traffic.

3. Third, the current industry landscape: Only 12.6% of service providers have reached a mature stage of AI capability, while nearly 90% remain in the phase of scattered tool testing or preliminary AI application. The gap between AI-proficient and AI-illiterate service providers will continue to widen.

The industry shifts outlined in this article offer clear directional guidance for brands pursuing cross-border expansion, marketing optimization, and user operation in the AI era.

1. First, the core changes in consumer behavior and traffic: AI has restructured how consumers discover products. Brands featured in ChatGPT recommendations are 2.5 times more likely to generate website visits within seven days than unmentioned brands. For cross-border operations, brands can no longer rely solely on traditional product detail page optimization; instead, they need to build product content systems that present product value, use cases, and user experience in a logic that AI can understand, retrieve, and trust, in order to capture incremental traffic from AI recommendations.

2. Second, the criteria for selecting service partners: Sellers’ demand for AI services has shifted from novelty testing to solving practical pain points. 80.6% of sellers require AI solutions deeply tailored to their product categories and business scenarios, more than half are willing to share business data to co-develop proprietary models, and nearly 40% prefer performance-based payment models. Brands can select suitable services based on their own stage: small brands can adopt affordable, standardized AI tools to build foundational capabilities; mid-tier brands can leverage vertical-scenario AI services to develop targeted competitive edges; and leading brands can invest in deeply customized proprietary AI decision-making models to build long-term moats.

This article clearly outlines the operational changes, risks, and growth opportunities facing cross-border e-commerce sellers in the AI era, providing actionable guidance for AI tool selection and business planning.

1. First, the operational risks to watch out for: Native AI tools on e-commerce platforms are spreading rapidly. Over the past year, Amazon third-party sellers have generated more than 12 million listings via AI, greatly increasing the replaceability of basic operational tasks. Sellers who only use AI for superficial tasks such as basic product information generation will struggle to build differentiated advantages, and will fall into the trap of product homogenization, high operating costs, and weak pricing power.

2. Second, the clear traffic growth opportunities: AI has restructured traffic distribution rules. Recommendations from AI tools such as ChatGPT can drive 2.5 times more seven-day website visits for brands compared to those without recommendations. Sellers should build product content systems aligned with AI comprehension logic as soon as possible to capture AI-referred traffic.

3. Finally, the high-ROI collaboration approach: Sellers do not need to blindly purchase generic AI tools. 80.6% of high-value AI solutions are deeply integrated with specific product categories and business scenarios. Sellers can select services matched to their scale: small sellers can use affordable standardized tools to close capability gaps, mid-tier sellers can adopt vertical-scenario services to build targeted advantages, and large sellers can share business data with service providers to co-develop proprietary models, prioritizing performance-based payment models to reduce investment risk.

The cross-border e-commerce AI trends highlighted in this article provide clear actionable references for manufacturers planning cross-border e-commerce entry, advancing digital upgrading, and adapting to new channel requirements.

1. First, new demand signals from cross-border channels: AI is restructuring traffic rules in cross-border e-commerce, and whether products can be recognized and recommended by AI has become a core determinant of traffic acquisition. When building cross-border online channels, manufacturers should not design product selling points, scenario descriptions, and detail page content only to suit human readers’ habits; they also need to frame product value and use cases following a logic that AI can understand, retrieve, and trust, in order to capture incremental AI-referred traffic and gain 2.5 times more visit opportunities than ordinary products.

2. Second, feasible pathways for digital upgrading: Manufacturers do not need to make heavy, blind investments in building full in-house AI systems for cross-border e-commerce. Instead, they can select AI services aligned with their scale: smaller factories can first use affordable standardized AI tools to build basic operational capabilities; mid-sized factories with existing cross-border experience can adopt vertical-scenario AI services to build hit product advantages; larger factories can share supply chain and operational data to co-develop proprietary models with service providers, leveraging intelligent decision-making to build competitive moats and avoid homogenized price wars.

This article systematically breaks down the industry shifts, client pain points, and incremental growth opportunities facing cross-border e-commerce service providers in the AI era, outlining clear directions for capability upgrading and business positioning.

1. First, the existential industry pressure that must be addressed: Native AI tools on e-commerce platforms are spreading rapidly, with Amazon third-party sellers generating more than 12 million listings via AI over the past year. The standardization of basic operational services is rising fast, with 57.3% of service providers already reporting significant survival pressure, and 61.7% expecting the gap between AI-proficient and non-AI peers to keep widening. Service models that capture value solely through repetitive execution will face sustained challenges.

2. Second, the clear shifts in client demand: Sellers’ AI priorities have shifted from operational simplification to intelligent growth. 80.6% of sellers require AI solutions deeply tailored to their categories and business scenarios, 76.2% prioritize solutions that solve practical business problems, 52.9% are willing to share business data to co-develop models, and 38.4% prefer performance-based payment models. In terms of client segmentation, mid-tier sellers will be the fastest-growing AI demand group over the next three years; small sellers need affordable standardized tools, while leading sellers require deeply customized solutions.

3. Finally, viable tiered development pathways: Early-stage service providers can start with standardized tools to serve the small-seller market and build operational experience; growth-stage providers can focus on vertical scenarios to capture mid-tier seller clients; mature providers can leverage full-stack capabilities to serve all client segments.

The cross-border e-commerce AI trends, along with evolving seller and service provider behaviors outlined in this article, offer decision-making references for e-commerce platforms to optimize ecosystem construction, improve merchant recruitment and operation, and mitigate industry risks.

1. First, the clear trends across the platform ecosystem: The proliferation of built-in platform AI tools has greatly improved operational efficiency. On Amazon alone, third-party sellers used generative AI to create more than 12 million product listings over the past year. As basic operational services become increasingly standardized, more than half of service providers are facing survival pressure. Platforms need to guide service providers to upgrade toward high-value, differentiated services, to prevent low-quality, homogenized offerings from disrupting the ecosystem.

2. Second, the shifting core demands of platform merchants: Merchants’ AI needs have evolved from novelty feature testing to practical growth support. More than 80% of merchants require AI capabilities deeply tailored to their categories and business scenarios, over half are willing to share business data to train scenario-specific models, and nearly 40% prefer performance-based service models. Meanwhile, AI is restructuring traffic pathways—brands recommended by AI gain 2.5 times more visits—and merchants broadly need guidance on building content aligned with AI logic.

3. Finally, directions for ecosystem optimization: Platforms can match AI service resources to merchants of different scales in a tiered manner, onboard service providers with varying capability levels, improve data security and performance guarantee mechanisms, and raise the overall operational efficiency of the ecosystem.

Based on a valid sample of 206 service providers, combined with platform operational data and third-party research findings, this industry report presents the new trends, structures, and models emerging in the cross-border e-commerce service industry amid the AI era, with high reference value for research.

1. First, the new structural changes across the industry: Both supply and demand sides are driving a restructuring of the service provider market. On the supply side, the rapid improvement of e-commerce platforms’ AI infrastructure and rising standardization of basic operational services continue to squeeze the value space of traditional services. On the demand side, sellers’ AI demands are shifting from operational simplification to intelligent growth, from novelty testing to deep scenario-specific application, and from single-service procurement to deep data co-creation and performance-revenue sharing partnership models. 80.6% of sellers require deeply scenario-integrated AI solutions, and 52.9% are willing to share data to train proprietary models.

2. Second, the new tiered industry structure taking shape: Service providers’ AI capabilities show a pyramid-shaped differentiation: 56.3% are in the initial stage of scattered tool testing, 31.1% are in the growth stage of applying AI to core business operations, and only 12.6% have reached the mature stage of being able to commercialize and externalize productized AI capabilities. The demand side is also segmented: mid-tier sellers, accounting for 52.4% of demand, will be the fastest-growing AI client group over the next three years, while leading sellers and small sellers account for 32% and 15.5% of demand respectively. A new competitive landscape where tiered capabilities match tiered client groups is forming.

3. Additional emerging issues—including AI-driven changes to traffic rules and security guarantees in data sharing—also warrant ongoing tracking and research.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

【亿邦原创】全球电商迈入智能发展新周期,服务商市场迎来结构性变化。一方面,电商网站AI 工具普及让基础运营服务愈发标准化,挤压传统服务价值空间;另一方面,卖家AI 诉求已从简化运营转向智能增长,催生了大量未被满足的服务新需求。供需两端变化正在撬动AI 细分服务市场增量空间。

2026年7月30日,亿邦智库联合亚马逊SPN服务商网络发布《智胜新周期—跨境电商服务商AI发展报告》(以下简称“报告”),报告从电商网站基建、卖家需求、服务商供给三大维度, 逐层拆解新周期下服务商的竞争格局与增长机遇。

01

电商网站:基础服务标准化与消费行为变革倒逼服务升级

随着电商网站AI能力不断增强,部分基础运营环节正从人工服务转向智能化工具支持。报告显示,过去一年,仅亚马逊第三方卖家就利用生成式AI创建超过1200万条可售商品Listing,相当于平均每分钟有20多条新商品信息在AI辅助下生成并上线1

“一键生成”能力使基础运营服务可替代性增强,调研显示,57.3%的服务商已明显感知生存压力2。未来,依靠重复性执行获得价值的服务模式将面临挑战,服务商需要向更具专业价值和差异化能力的方向升级。

AI不仅改变运营方式,也正在改变消费者发现商品的路径。Similarweb研究表明,出现在ChatGPT推荐中的品牌在7天内获得网站访问的可能性是未被推荐品牌的2.5倍。卖家需要将产品价值、应用场景和用户体验,以更符合AI理解逻辑的方式融入商品详情页3。这对服务商提出新的要求:不仅要帮助卖家完成传统运营优化,更需要帮助其构建“AI可理解、可调用、可信任”的商品内容体系。

02

卖家端:AI核心诉求从简化运营转向智能增长

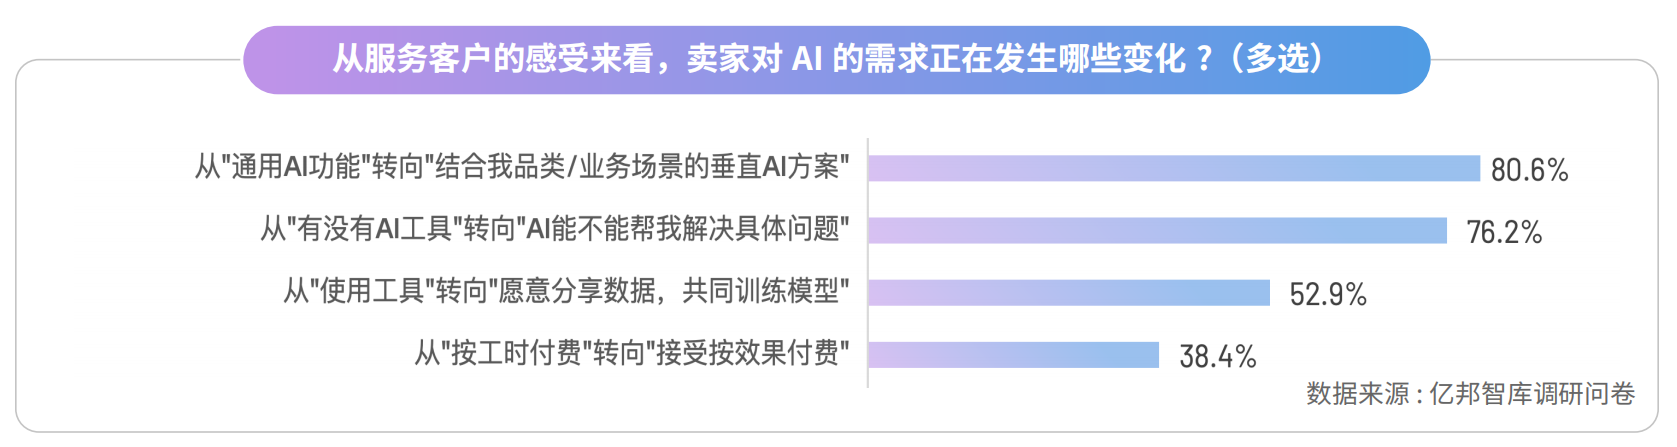
一是从“功能尝鲜”到“场景深耕”。卖家希望以更垂直的AI产品解决个性化痛点。当前卖家受困于产品同质化严重、运营成本居高不下、商品溢价能力不足等问题。随着通用型AI工具逐步成为卖家标配,卖家对服务需求已经转向更懂品类特性、更贴合自身业务场景的AI产品,解决实际痛点。根据服务商反馈,80.6%的卖家迫切要求AI方案与自身品类或业务场景深度绑定,76.2%的卖家关注点已从“有无AI工具”变为“能否解决具体问题”。

这就要求服务商敏捷洞察卖家需求变化,围绕品类特性和业务场景打磨AI产品和服务,精准响应卖家升级需求。

二是从单项采购到双向绑定。卖家希望以更深入的合作模式换取独特竞争优势和长远发展。目前市面上AI应用趋同难以形成差异化,卖家意识到,唯有开放更深度的协作,才能获得为其业务量身打造的专属 AI 能力,同时保障自身业务独立性及安全性,赢得可持续增长。根据服务商反馈,52.9%的卖家愿意分享业务数据,用于共同训练更贴合自身场景的模型;38.4%的卖家更倾向“按效果付费”的交付模式。

服务商与卖家的关系正在从传统服务采购转向深度合作。未来,服务商需要建立更加透明、安全和可量化的合作机制,保障交付成果高质量、效果可量化,通过数据共享、模型共创和效果分成等方式,实现双向绑定与深度共赢。

03

服务商端:AI细分服务市场撬动新增量空间

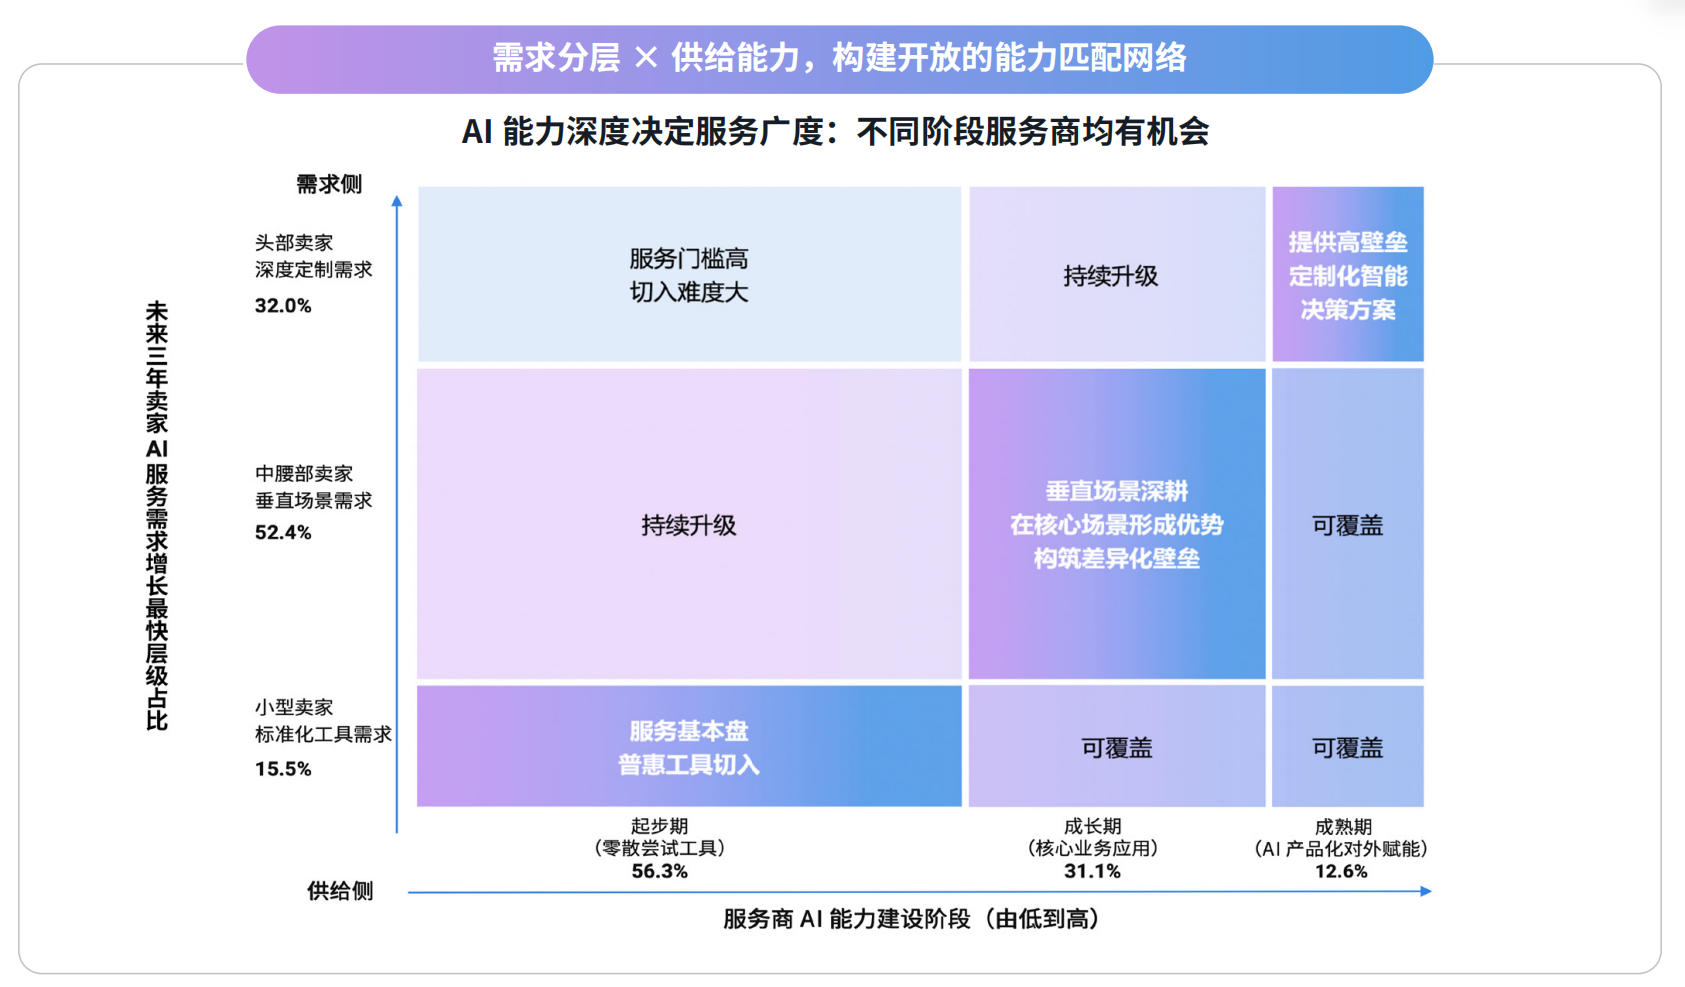
服务商AI能力建设呈金字塔分化。不同企业之间的AI成熟度差距逐渐显现,调研显示,56.3%的服务商仍处于“零散尝试工具”的起步期;31.1%的服务商进入成长期,开始在核心业务中应用AI构建差异化能力;而真正具备AI产品化能力、能够对外赋能的成熟期服务商仅占12.6%。

从服务商AI能力建设情况分析,起步期与成长期服务商合计占比近90%,这批服务商的成长速度将直接决定未来竞争格局。调研显示,61.7%的服务商认为“懂AI的服务商与不懂AI的服务商差距将拉大”2, 未来率先迈向“能力沉淀”者将赢得主动权。

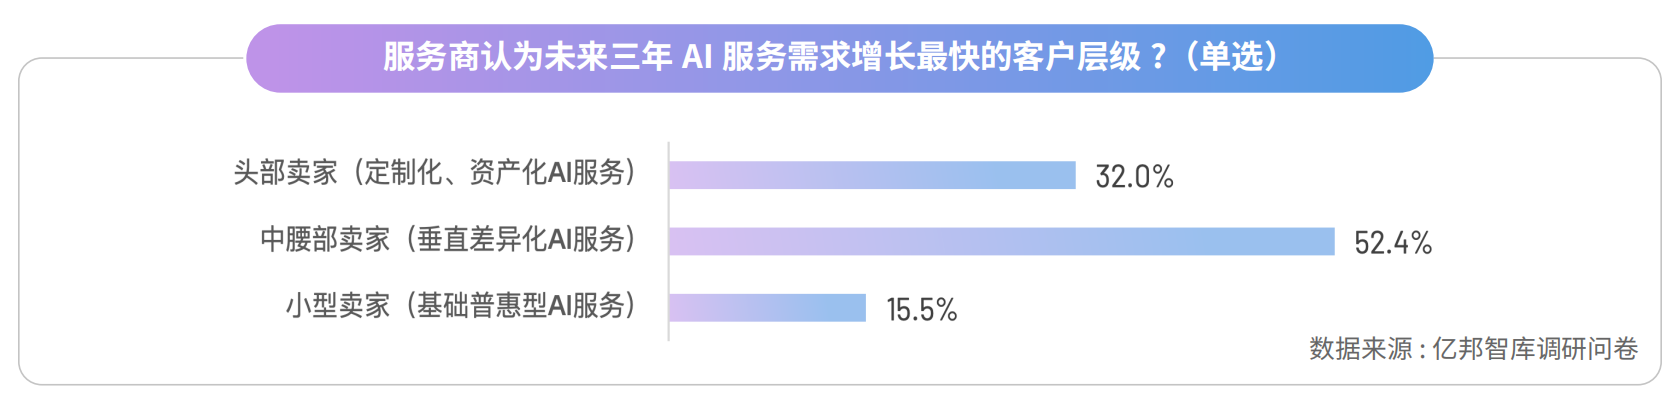
需求端层级决定AI服务差异化。卖家因规模及运营阶段不同,对未来AI服务需求呈现分化:根据服务商调研,当被问及“未来三年AI需求增长最快的客户层级”时,选择中腰部卖家的服务商比例高达52.4%,选择头部卖家与小型卖家的比例分别为32.0%和15.5%。

  • 小型卖家:资源与经验有限,急需标准化、普惠的AI工具,将技术直接转化为有效运营动作,以弥补基础能力不足; 
  • 中腰部卖家:是AI 服务核心增长引擎,需在特定业务场景形成单点优势,其“垂直差异化AI服务”需求与服务商的场景化能力天然契合; 
  • 头部卖家:虽然头部卖家服务门槛高,但依然有近三分之一的服务商将其视为增长最快的客户群体。此类客户需深度定制化AI服务,旨在将自身运营经验与私有数据训练为专属模型,构建高壁垒的智能决策方案。

AI能力深度决定服务广度。应对三类卖家需求, 服务商的能力半径决定能撬动多少增量空间,率先构筑“深度 AI”者将赢得增量机会。

  • 起步期服务商可凭基础标准化工具切入小型卖家,积累经验后向中腰部爬坡,若停留在“零散尝试工具”阶段,未来生存空间将持续压缩; 
  • 成长期服务商既可凭借垂直场景深耕构筑差异化壁垒,向上精准卡位中腰部卖家,也可通过标准化服务覆盖小型卖家; 
  • 成熟期服务商具备全栈服务能力,向上提供深度定制方案、向下能覆盖中腰部及小型卖家; 

服务商唯有认清主攻方向,在持续服务中沉淀能力,方能在动态匹配中抢占增量机会。

参考阅读:

[1] https://gs.amazon.cn/news/news-brand-260611

[2] 2026 跨境电商服务商 AI 能力调研 有效样本 N=206

[3]https://www.searchenginejournal.com/ai-recommended-brands-saw-2-5x-more-site-visits-similarweb/580241/

本文首发于 亿邦动力 官方网站

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

AI时代跨境电商卖家对服务商的需求有哪些变化?

当前跨境电商卖家对AI服务的核心诉求已从简化运营转向智能增长,80.6%的卖家要求AI方案与自身品类或业务场景深度绑定,52.9%的卖家愿意分享业务数据共建专属模型,合作模式从传统单项采购转向深度绑定、按效果付费的长期合作。

AI普及对跨境电商传统基础运营服务有哪些冲击?

随着电商平台AI工具普及,基础运营环节逐步转向智能化工具支持,过去一年仅亚马逊第三方卖家就借助生成式AI创建超1200万条可售商品Listing,基础运营服务可替代性增强,57.3%的服务商已感知到明显生存压力,重复执行类服务模式面临淘汰风险。

当前跨境电商服务商的AI能力分为哪几个阶段?

目前跨境电商服务商AI能力呈金字塔分化,56.3%处于零散尝试AI工具的起步期,31.1%进入在核心业务应用AI构建差异化能力的成长期,仅12.6%进入具备AI产品化、可对外赋能能力的成熟期,近九成服务商仍在能力爬坡阶段。

未来跨境电商AI服务的核心增量客群是哪类卖家?

未来三年中腰部卖家是跨境电商AI服务的核心增长引擎,52.4%的服务商认为该客群AI需求增长最快,这类卖家需要垂直业务场景的差异化AI服务以形成单点优势,与服务商的场景化服务能力高度契合。

这么好看,分享一下?

朋友圈 分享

APP内打开

+1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0