广告
加载中

抖音双11终极榜单:美容个护霸主地位动摇 男女装仍有机会

廖紫琳 2026-11-18 12:51
廖紫琳 2026/11/18 12:51

邦小白快读

EN
全文速览

总1:这届抖音双11最值得看的是增长行业和机会赛道。

1.大促10月15日至11月11日,消费券带动超2万中小商家成交额破百万元,破亿商家数量同比增15%。

2.农产品、宠物、运动户外、护肤增长显著,破亿品牌数量分别同比增200%、100%、45%、35%。

总2:榜单里的新面孔和品牌做法可作为观察样本。

1.彩妆好物TOP10新老黑马并出,蒂洛薇主攻中端平价,卡姿兰老牌国货翻红,专业化妆师品牌和修可芙轻敏肌彩妆护肤走俏。

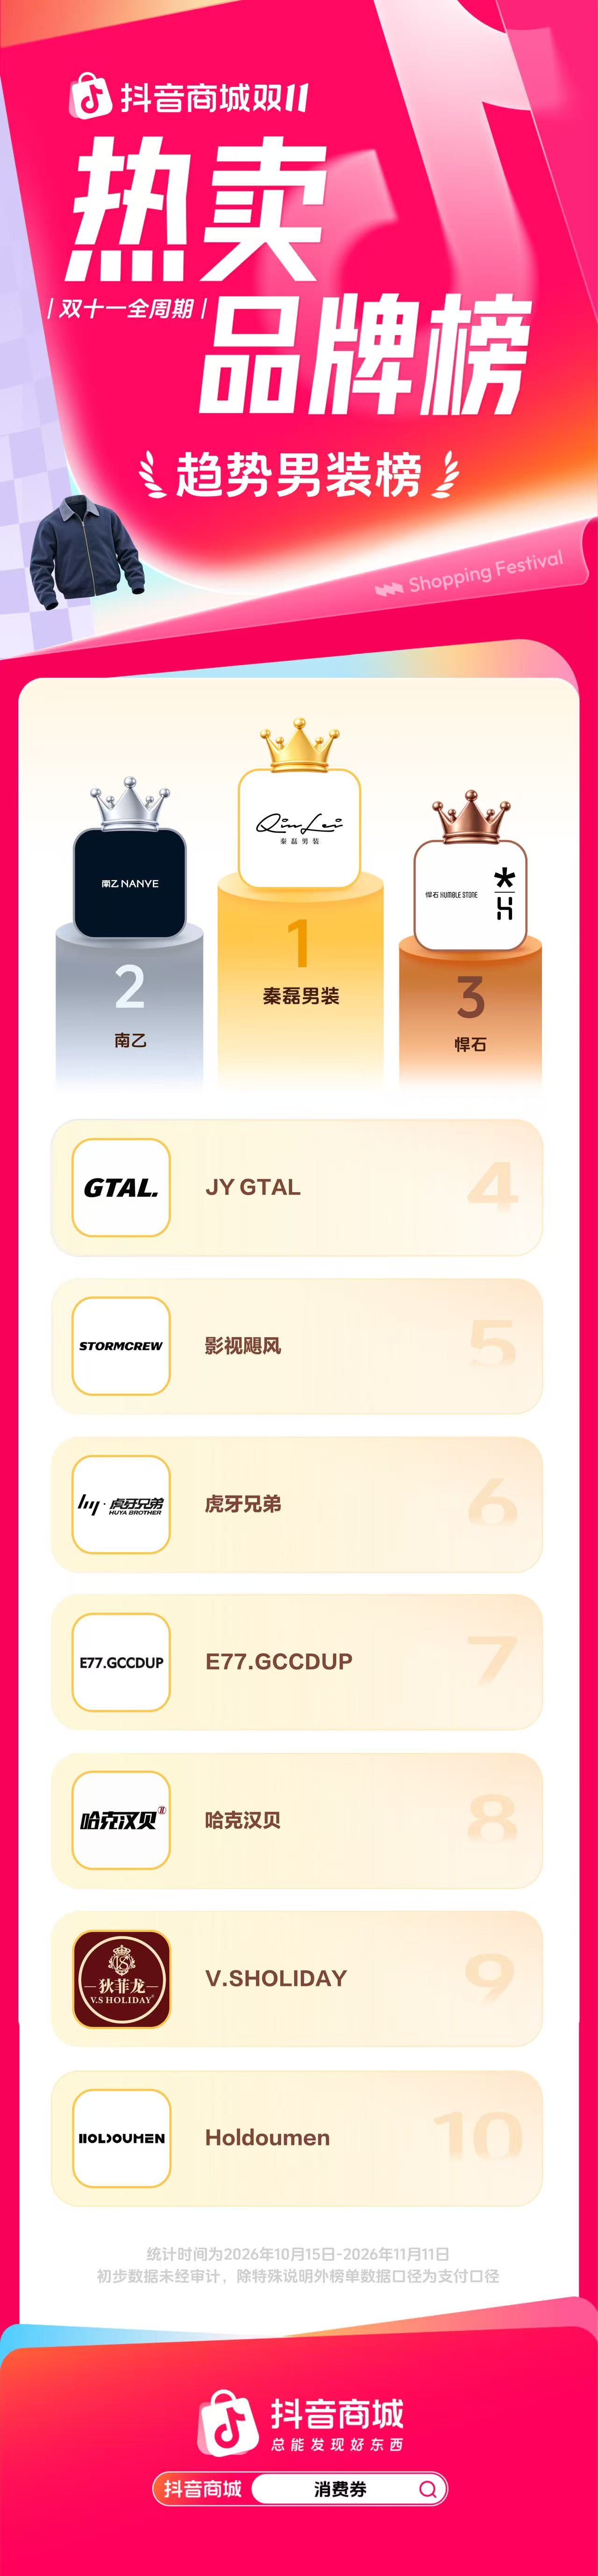
2.男装秦磊男装靠主理人IP和平替老钱风,南乙做平价快时尚,悍石从常熟产业带低价冲锋衣转向硬指标国货户外。

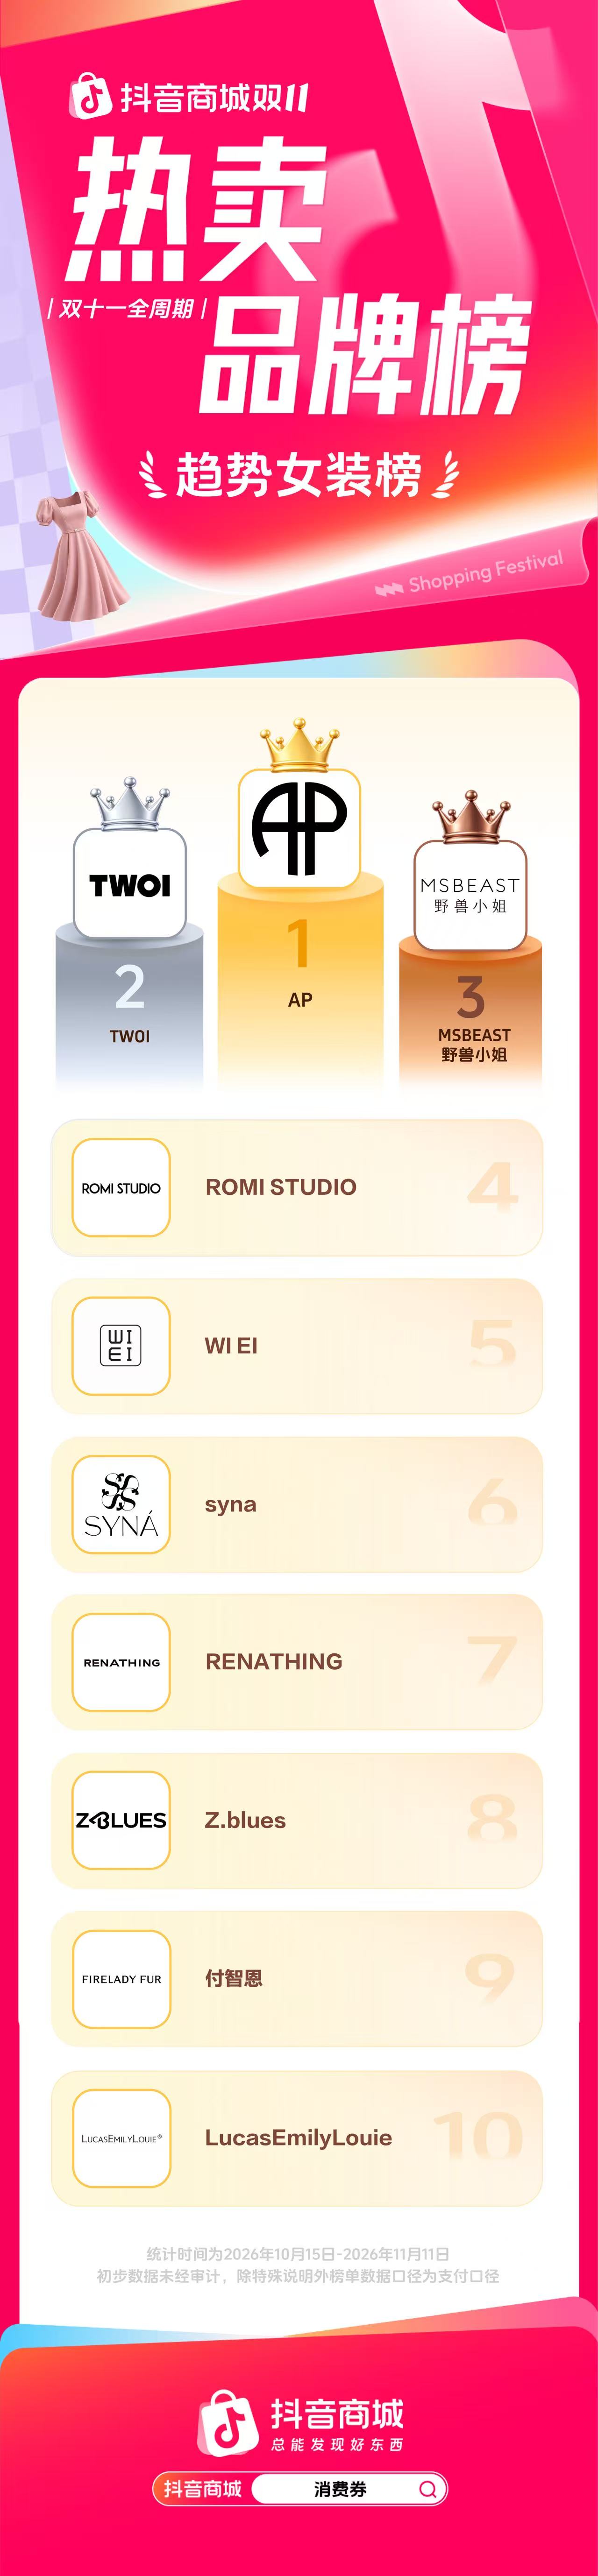
3.女装TWOI靠奶油风审美、限量周边和社群运营,WIEI靠自研面料与版型,RENATHING主理轻懒主义,Z.blues靠丝毛棉麻外贸高货。

总1:品牌竞争呈现细分赛道新面孔增多、国潮与国际品牌分层竞争。

1.趋势女装、趋势男装、彩妆好物仍是机会赛道,TOP10新面孔频出;彩妆中蒂洛薇中端平价、卡姿兰国货翻红、专业化妆师品牌和修可芙轻敏肌定位形成差异。

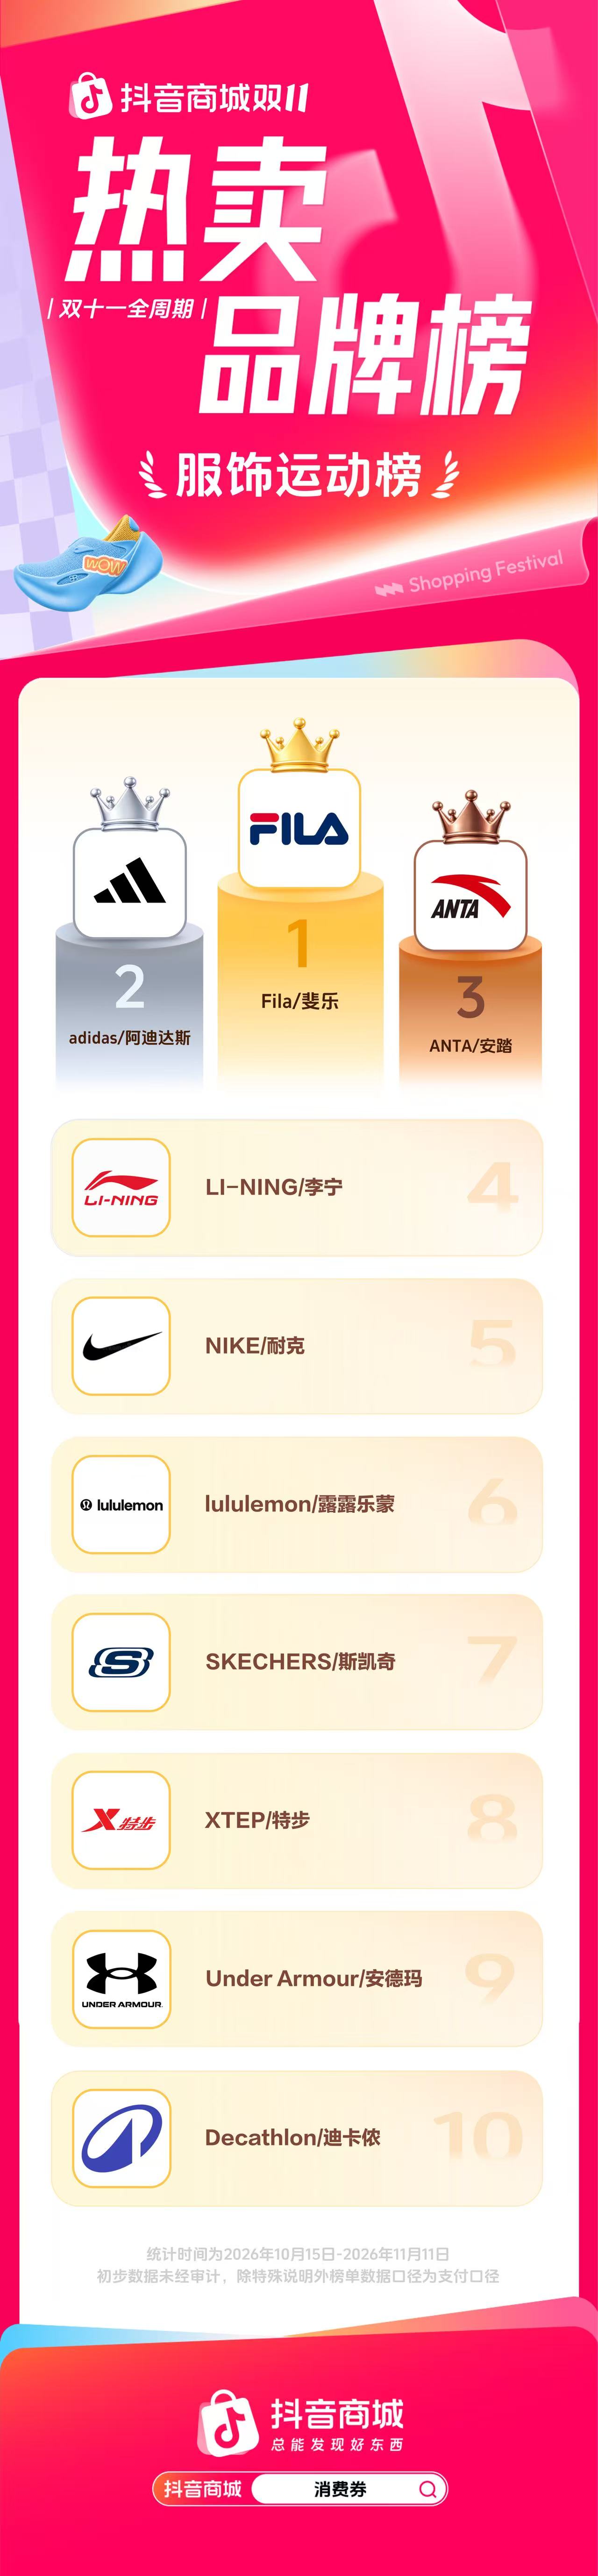
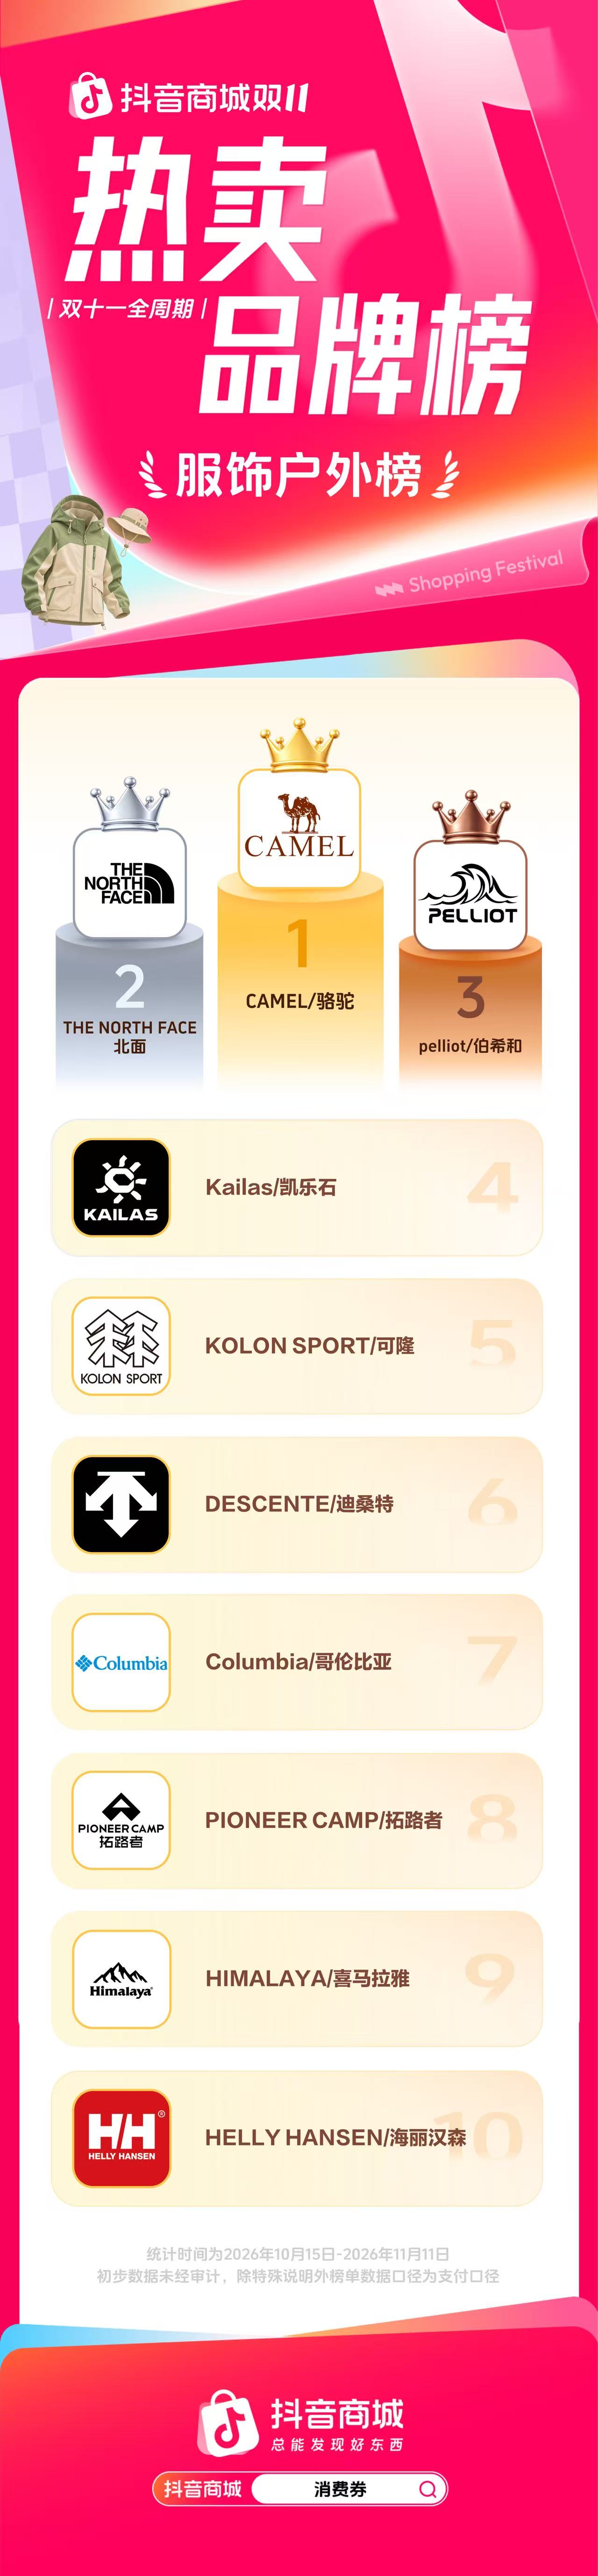
2.运动户外服饰户外榜一半以上中国品牌,骆驼第1、伯希和第3;服饰运动榜中国品牌仅30%,安踏、李宁、特步上榜。美容护肤总榜50%国产品牌且韩束第1、珀莱雅第2、谷雨第5,但护肤好物榜国际品牌占6席。

总2:品牌营销和产品研发要围绕人群、调性与硬指标展开。

1.男装秦磊男装用主理人IP和奢侈品牌设计语言加亚洲版型做平替老钱风,南乙走平价快时尚,悍石砍低端线转防水透湿耐磨硬指标。

2.女装TWOI用奶油风审美、限量周边和社群运营,WIEI靠自研面料和版型,RENATHING主打轻懒主义,Z.blues靠丝毛棉麻外贸高货。

3.美容护肤、家清、个人护理、宠粮等类目榜首更替,品牌需应对榜单洗牌和价格带竞争。

总1:平台消费券是本届抖音双11的重要拉动,增长行业和机会赛道值得卖家跟进。

1.10月15日至11月11日,消费券带动超2万中小商家成交额破百万元,带动成交额破亿商家数量同比增15%。

2.农产品、宠物、运动户外、护肤破亿品牌数量分别同比增200%、100%、45%、35%。

3.趋势女装、趋势男装、彩妆好物TOP10新面孔频出,说明细分赛道仍有增长窗口。

总2:卖家可学习差异化定位,同时注意榜单洗牌风险。

1.彩妆可做中端平价、老牌国货翻红、专业化妆师品牌、轻敏肌彩妆护肤等细分。

2.男装可借主理人IP、平价快时尚、产业带户外品牌转型硬指标;女装可做审美社群、自研面料版型、轻懒主义和外贸高货。

3.美容护肤、家清、个人护理、宠粮榜首变化明显,蓝月亮未上榜等提示卖家要防范竞争位次变化。

总1:榜单显示工厂型品牌的机会在产业带转型、产品硬指标和设计研发。

1.悍石从常熟产业带长出来,早期低价冲锋衣起量,后主动砍掉低端线,转向防水、透湿、耐磨等硬指标的高性价比国货户外。

2.男装出现奢侈品牌设计语言加亚洲身材版型的平替老钱风,以及韩系简约、极简、中式复古的日常实穿路线,对版型和设计提出要求。

3.女装WIEI依靠自研面料和版型设计做高级感极简,Z.blues依靠丝毛棉麻外贸高货,显示面料与供应链能力仍是关键。

总2:增长品类给工厂带来订单和电商化启示。

1.农产品、宠物、运动户外、护肤增长显著,破亿品牌数量同比增200%、100%、45%、35%,可关注对应生产与设计需求。

2.彩妆中中端平价、专业化妆师品牌、轻敏肌彩妆护肤等定位,提示工厂要配合细分人群做产品开发。

3.产业带工厂可通过电商品牌化、砍低端线、强调硬指标和自研面料,推进数字化与品牌化经营。

总1:服务商应关注抖音双11的行业增长、榜单更替和品牌分化趋势。

1.消费券带动超2万中小商家成交额破百万元,破亿商家数量同比增15%;农产品、宠物、运动户外、护肤增长显著,破亿品牌数量分别同比增200%、100%、45%、35%。

2.趋势女装、趋势男装、彩妆好物TOP10新面孔频出;国潮在运动户外、美容护肤、滋补保健等细分垂类明显,但部分总榜仍由国际品牌占优。

总2:客户痛点集中在同质化竞争、榜单位次波动和产品差异化,解决方案可从品牌定位与运营入手。

1.彩妆需做中端平价、国货翻红、专业化妆师、轻敏肌等细分定位;男装需做主理人IP、平价快时尚、产业带户外硬指标转型。

2.女装需用奶油风审美、限量周边、社群运营、自研面料版型、轻懒主义、外贸高货等形成差异。

3.美容护肤、家清、个人护理、宠粮榜首更替,服务商要帮助客户应对竞争洗牌和统计口径变化带来的不确定性。

总1:平台用消费券拉动中小商家,同时通过榜单呈现招商与运营方向。

1.10月15日至11月11日,消费券带动超2万中小商家成交额破百万元,破亿商家数量同比增15%,说明补贴对中小商家和头部商家均有拉动。

2.农产品、宠物、运动户外、护肤增长显著,破亿品牌数量分别同比增200%、100%、45%、35%,可作为招商和品类运营重点。

3.趋势女装、趋势男装、彩妆好物TOP10新面孔频出,平台可围绕机会赛道引入新锐品牌。

总2:平台需关注榜单竞争和统计口径风险。

1.国潮在运动户外、美容护肤、滋补保健等细分垂类明显,但服饰运动榜、护肤好物榜仍由国际品牌占优,平台运营要平衡国货扶持与国际品牌供给。

2.美容护肤、家清、个人护理、宠粮榜首更替,平台要管理类目竞争和商家位次波动。

3.文中提到2025年、2026年平台榜单统计口径不一致可能导致排名改变,平台应统一口径、规避榜单争议。

总1:抖音双11榜单呈现机会赛道新锐化、国潮细分化和类目霸主更替三条产业动向。

1.趋势女装、趋势男装、彩妆好物TOP10新面孔频出;男装出现主理人IP、平价快时尚、产业带户外硬指标转型,女装出现审美社群、自研面料版型、轻懒主义、外贸高货等模式。

2.国潮在运动户外、美容护肤、滋补保健等细分垂类明显;滋补保健前10全为中国品牌,部分品牌用进口原料但所有权和运营主体在国内。

3.美容护肤韩束从去年第1降至今年第5、赫莲娜第1,家清滴露第1、蓝月亮未上榜,个人护理淘淘氧棉登顶,宠粮卫仕从去年第3升至第1。

总2:新问题在榜单统计口径和品牌分层。

1.服饰户外榜一半以上中国品牌,服饰运动榜仅30%;美容护肤总榜50%国产品牌靠前,护肤好物榜国际品牌占6席。

2.文章提示2025年、2026年平台榜单统计口径不一致可能导致排名改变,研究需关注口径对结论的影响。

3.商业模式上可研究主理人IP、社群运营、自研面料、产业带品牌化、平价老钱风、外贸高货与细分人群定位。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

Summary 1: The most notable aspects of this Douyin Double 11 are growth industries and opportunity tracks.

1. The promotion ran from Oct 15 to Nov 11. Consumption coupons drove more than 20,000 small and medium-sized merchants to exceed RMB 1 million in GMV, and the number of merchants surpassing RMB 100 million rose 15% YoY.

2. Agricultural products, pets, sports and outdoor, and skincare showed notable growth; the number of brands exceeding RMB 100 million increased 200%, 100%, 45%, and 35% YoY, respectively.

Summary 2: New entrants and brand practices in the rankings can serve as useful observation samples.

1. In the top 10 beauty and makeup products, new and established dark horses appeared together. Diluowei focused on mid-priced affordable products; Carslan, an established Chinese brand, regained popularity; professional makeup artist brands and Xiukefu's mildly sensitive-skin makeup and skincare gained traction.

2. Qin Lei Menswear relied on founder IP and affordable old-money style; Nanyi pursued affordable fast fashion; Hanshi shifted from low-priced shell jackets in the Changshu industrial belt to a Chinese outdoor brand defined by hard performance metrics.

3. TWOI leveraged a creamy aesthetic, limited-edition merchandise, and community operations; WIEI relied on in-house fabrics and fits; RENATHING focused on a light-lazy philosophy; Z.blues relied on high-end silk, wool, cotton, and linen export goods.

Summary 1: Brand competition shows more new faces in niche tracks and tiered competition between Chinese and international brands.

1. Trendy womenswear, trendy menswear, and color cosmetics remain opportunity tracks, with frequent new entrants in the top 10. In color cosmetics, Diluowei's mid-priced affordable positioning, Carslan's renewed popularity as a Chinese brand, professional makeup artist brands, and Xiukefu's mildly sensitive-skin positioning created differentiation.

2. In sports and outdoor apparel, more than half of the outdoor list are Chinese brands, with Camel No.1 and Pelliot No.3; in apparel and sports, Chinese brands account for only 30%, with Anta, Li Ning, and Xtep on the list. In the overall beauty and skincare list, 50% are Chinese brands, with Kans No.1, Proya No.2, and Guyu No.5; however, international brands hold six spots in the skincare products list.

Summary 2: Brand marketing and product development should focus on target groups, brand tone, and hard performance metrics.

1. Qin Lei Menswear uses founder IP and luxury brand design language with Asian fits to create an affordable old-money style; Nanyi pursues affordable fast fashion; Hanshi cuts low-end lines and shifts to waterproof, breathable, and abrasion-resistant hard metrics.

2. TWOI uses a creamy aesthetic, limited-edition merchandise, and community operations; WIEI relies on in-house fabrics and fits; RENATHING focuses on a light-lazy philosophy; Z.blues relies on high-end silk, wool, cotton, and linen export goods.

3. Leadership in beauty and skincare, home cleaning, personal care, and pet food changed; brands need to respond to ranking reshuffles and price-band competition.

Summary 1: Platform consumption coupons were a key driver of this Douyin Double 11, and growth industries and opportunity tracks are worth sellers' attention.

1. From Oct 15 to Nov 11, consumption coupons drove more than 20,000 small and medium-sized merchants to exceed RMB 1 million in GMV and increased the number of merchants with GMV above RMB 100 million by 15% YoY.

2. The number of brands exceeding RMB 100 million in agricultural products, pets, sports and outdoor, and skincare grew 200%, 100%, 45%, and 35% YoY, respectively.

3. Frequent new entrants in the top 10 of trendy womenswear, trendy menswear, and color cosmetics indicate that niche tracks still offer growth windows.

Summary 2: Sellers can learn from differentiated positioning while watching for ranking reshuffle risks.

1. In color cosmetics, sellers can target mid-priced affordable products, renewed Chinese heritage brands, professional makeup artist brands, and mildly sensitive-skin makeup and skincare.

2. Menswear can leverage founder IP, affordable fast fashion, and industrial-belt outdoor brands transitioning to hard performance metrics; womenswear can pursue aesthetic communities, in-house fabrics and fits, a light-lazy philosophy, and high-end export goods.

3. Leadership changes in beauty and skincare, home cleaning, personal care, and pet food, including Blue Moon's absence from the list, signal that sellers should guard against shifts in competitive position.

Summary 1: The rankings show that opportunities for factory-origin brands lie in industrial-belt transformation, hard product metrics, and design and R&D.

1. Hanshi emerged from the Changshu industrial belt, initially growing through low-priced shell jackets and later cutting low-end lines to shift toward high-value Chinese outdoor products with hard metrics such as waterproofing, breathability, and abrasion resistance.

2. Menswear saw affordable old-money styles combining luxury design language with Asian body fits, as well as Korean minimalist, minimalist, and Chinese retro routes for daily wear, raising requirements for fit and design.

3. Womenswear brand WIEI relies on in-house fabrics and fit design for refined minimalist looks; Z.blues relies on high-end silk, wool, cotton, and linen export goods, showing that fabric and supply-chain capabilities remain critical.

Summary 2: Growing categories bring factories orders and e-commerce implications.

1. Agricultural products, pets, sports and outdoor, and skincare grew notably, with the number of brands exceeding RMB 100 million up 200%, 100%, 45%, and 35% YoY; factories can monitor corresponding production and design demand.

2. In color cosmetics, mid-priced affordable positioning, professional makeup artist brands, and mildly sensitive-skin makeup and skincare suggest that factories should develop products for segmented consumer groups.

3. Industrial-belt factories can advance digitalization and brand-building by branding on e-commerce, cutting low-end lines, emphasizing hard metrics, and developing in-house fabrics.

Summary 1: Service providers should watch industry growth, ranking changes, and brand differentiation on Douyin Double 11.

1. Consumption coupons drove more than 20,000 small and medium-sized merchants to exceed RMB 1 million in GMV, and the number of merchants with GMV above RMB 100 million rose 15% YoY; agricultural products, pets, sports and outdoor, and skincare grew notably, with the number of brands exceeding RMB 100 million up 200%, 100%, 45%, and 35% YoY, respectively.

2. Frequent new entrants appeared in the top 10 of trendy womenswear, trendy menswear, and color cosmetics; Chinese trends were evident in verticals such as sports and outdoor, beauty and skincare, and health supplements, but international brands still led some overall lists.

Summary 2: Client pain points center on homogeneous competition, ranking volatility, and product differentiation; solutions can start with brand positioning and operations.

1. Color cosmetics require differentiated positioning such as mid-priced affordable products, renewed Chinese brands, professional makeup artists, and mildly sensitive skin; menswear requires founder IP, affordable fast fashion, and industrial-belt outdoor brands transitioning to hard metrics.

2. Womenswear needs differentiation through creamy aesthetics, limited-edition merchandise, community operations, in-house fabrics and fits, a light-lazy philosophy, and high-end export goods.

3. Leadership changes in beauty and skincare, home cleaning, personal care, and pet food mean service providers must help clients cope with competitive reshuffles and uncertainty from changes in statistical methodology.

Summary 1: The platform used consumption coupons to drive small and medium-sized merchants while using rankings to signal merchant recruitment and operational directions.

1. From Oct 15 to Nov 11, consumption coupons drove more than 20,000 small and medium-sized merchants to exceed RMB 1 million in GMV and increased the number of merchants with GMV above RMB 100 million by 15% YoY, indicating that subsidies boosted both small and medium-sized merchants and top merchants.

2. Agricultural products, pets, sports and outdoor, and skincare grew notably, with the number of brands exceeding RMB 100 million up 200%, 100%, 45%, and 35% YoY, respectively; these can be priorities for merchant recruitment and category operations.

3. Frequent new entrants in the top 10 of trendy womenswear, trendy menswear, and color cosmetics mean the platform can bring emerging brands into opportunity tracks.

Summary 2: The platform should watch ranking competition and statistical-scope risks.

1. Chinese trends are evident in verticals such as sports and outdoor, beauty and skincare, and health supplements, but international brands still lead the apparel and sports list and the skincare products list; platform operations should balance support for Chinese brands with international brand supply.

2. Leadership changes in beauty and skincare, home cleaning, personal care, and pet food mean the platform must manage category competition and merchant rank volatility.

3. The article notes that inconsistent statistical scopes for platform rankings in 2025 and 2026 may change rankings; the platform should unify standards and avoid ranking disputes.

Summary 1: Douyin Double 11 rankings reveal three industry trends: new entrants in opportunity tracks, segmented Chinese trends, and changing category leaders.

1. Frequent new entrants appeared in the top 10 of trendy womenswear, trendy menswear, and color cosmetics; menswear saw founder IP, affordable fast fashion, and industrial-belt outdoor brands transitioning to hard metrics, while womenswear saw aesthetic communities, in-house fabrics and fits, a light-lazy philosophy, and high-end export goods.

2. Chinese trends were evident in verticals such as sports and outdoor, beauty and skincare, and health supplements; the top 10 in health supplements were all Chinese brands, and some brands used imported ingredients but had domestic ownership and operating entities.

3. In beauty and skincare, Kans fell from No.1 last year to No.5 this year, with Helena Rubinstein at No.1; in home cleaning, Dettol was No.1 and Blue Moon was absent; in personal care, Taotao Yangmian topped the list; in pet food, Weishi rose from No.3 last year to No.1.

Summary 2: New questions concern ranking statistical scope and brand stratification.

1. More than half of the apparel and outdoor list are Chinese brands, while only 30% of the apparel and sports list are; in the overall beauty and skincare list, 50% of leading brands are Chinese, while international brands hold six spots in the skincare products list.

2. The article notes that inconsistent statistical scopes for platform rankings in 2025 and 2026 may change rankings; research should consider how scope affects conclusions.

3. Business models worth studying include founder IP, community operations, in-house fabrics, industrial-belt brand-building, affordable old-money style, high-end export goods, and positioning for segmented consumer groups.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

【亿邦原创】目前,抖音电商双11已经收官:10月15日至11月11日大促期间,超2万中小商家在平台消费券带动下,成交额突破百万元;消费券带动成交额破亿商家数量同比增长15%。

其中,农产品、宠物、运动户外和护肤行业增长显著,破亿品牌数量分别同比增长200%、100%和45%、35%。全行业热卖品牌榜单也已经出炉。对比往年的各行业热卖品牌榜,亿邦动力发现:

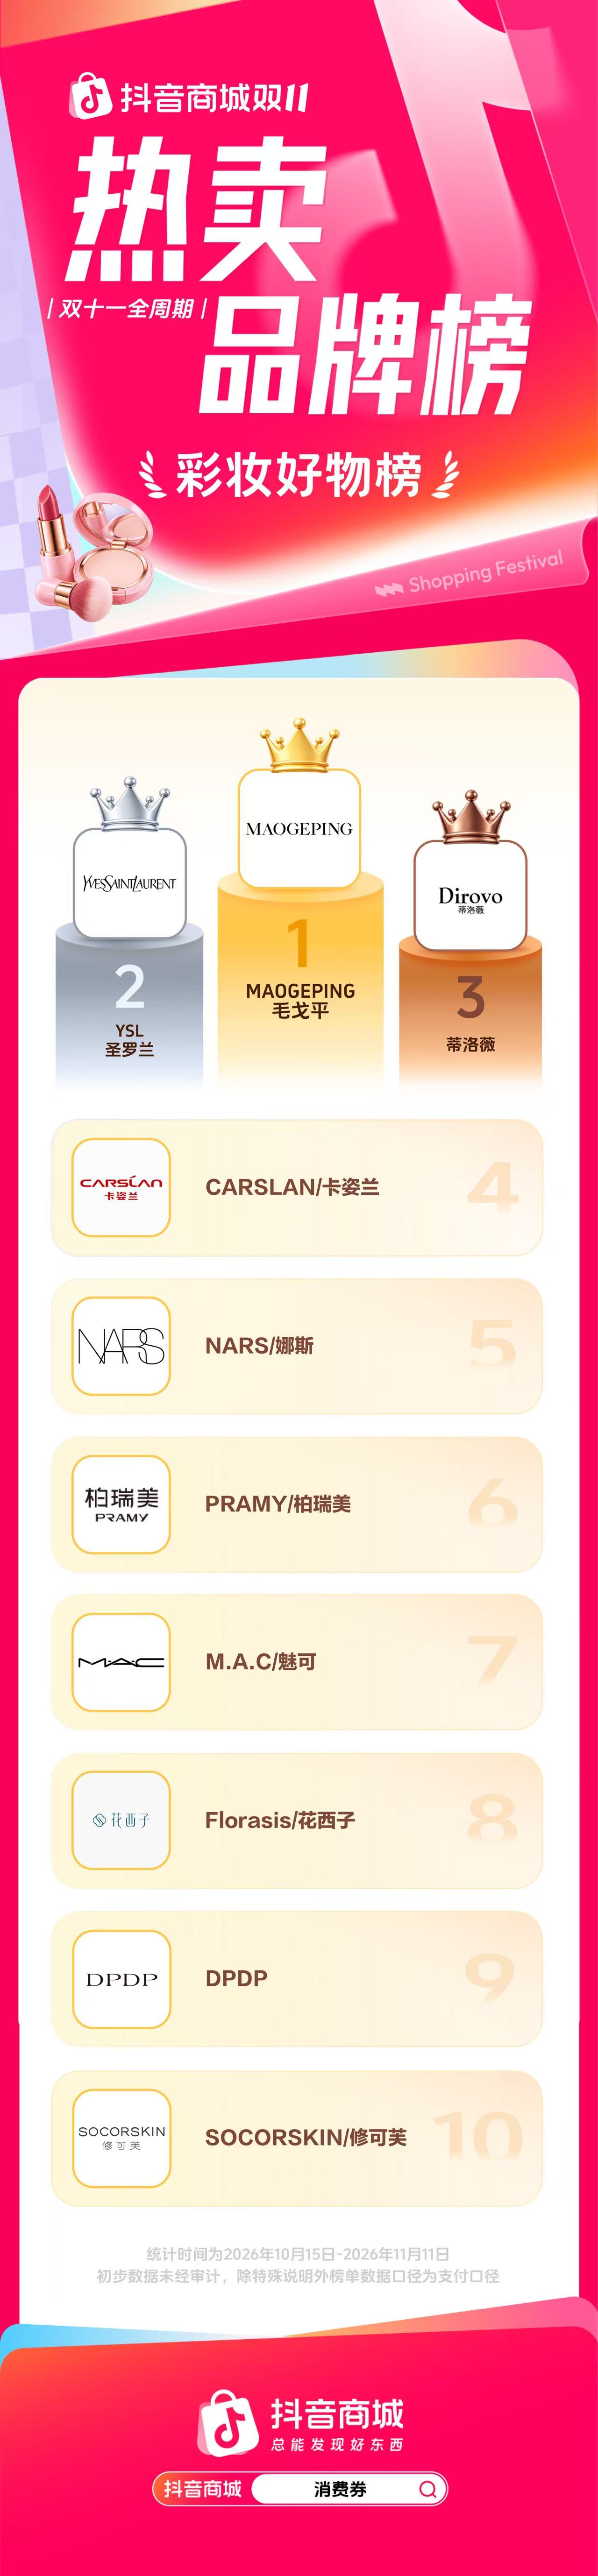
1、趋势女装、趋势男装、彩妆好物等仍是机会赛道,TOP10中新面孔频出。在彩妆好物榜里,第3名蒂洛薇主攻中端平价市场,第4名卡姿兰是老牌国货翻红,第6名为专业化妆师品牌走俏,第10名修可芙主打轻敏肌彩妆护肤赛道,这些新老品牌都是今年双11的彩妆赛道黑马。

趋势男装赛道里,新面孔品牌也各有特色,比如第1名秦磊男装依靠主理人IP起家,主打“奢侈品牌设计语言+亚洲身材版型”的平替老钱风,第2名南乙是杭州起家的平价快时尚男装,走韩系简约、极简与中式复古的日常实穿路线,第3名悍石常熟产业带里长出来的户外电商品牌,早期以低价冲锋衣起量,后主动砍掉低端线,转向强调防水、透湿、耐磨等硬指标的高性价比国货户外。

趋势女装赛道里,第2名TWOI、第5名WIEI、第7名RENATHING、第8名Z.blues都是往年未上榜的新锐品牌。其中,TWOI凭借主理人“奶油风”审美和限量周边产品、较强的社群运营吸引用户;WIEI依靠自研面料和版型设计,做出高级感极简风格;RENATHING由武晓娜主理,主打极简的“轻懒主义”;Z.blues依靠丝毛棉麻的外贸高货。

2、国潮趋势在细分垂类市场明显,但部分类目总榜仍以国际品牌为主。运动户外是一个典型的赛道。今年服饰户外榜中,有一半以上为中国品牌,比如第1名骆驼、第3名伯希和等;但在服饰运动榜里只有30%为中国品牌,分别是第3名安踏、第4名李宁、第8名特步。

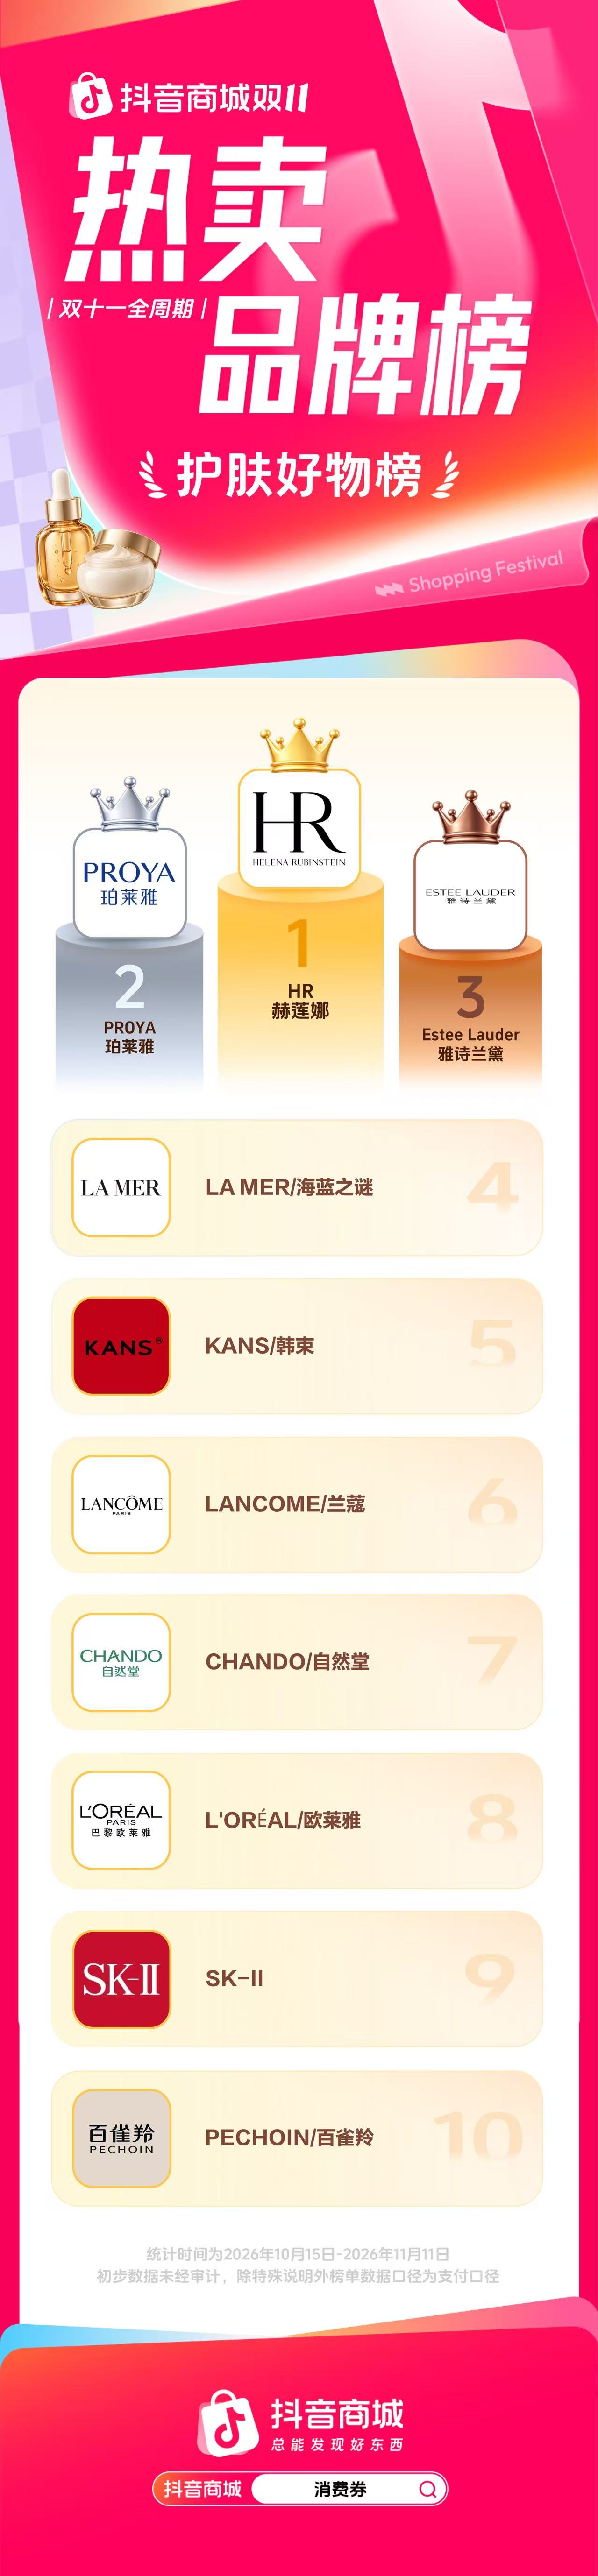
美容护肤行业是另一个案例。2025年双11美容护肤榜中,50%为国产品牌,且排名比较靠前,如第1名韩束、第2名珀莱雅、第5名谷雨等;但在今年的护肤好物榜里,赫莲娜、雅诗兰黛、海蓝之谜等国际品牌占据6席,整体排名超过中国品牌。当然,这也不排除2025年、2026年平台榜单统计口径不一致,导致的相关排名改变。

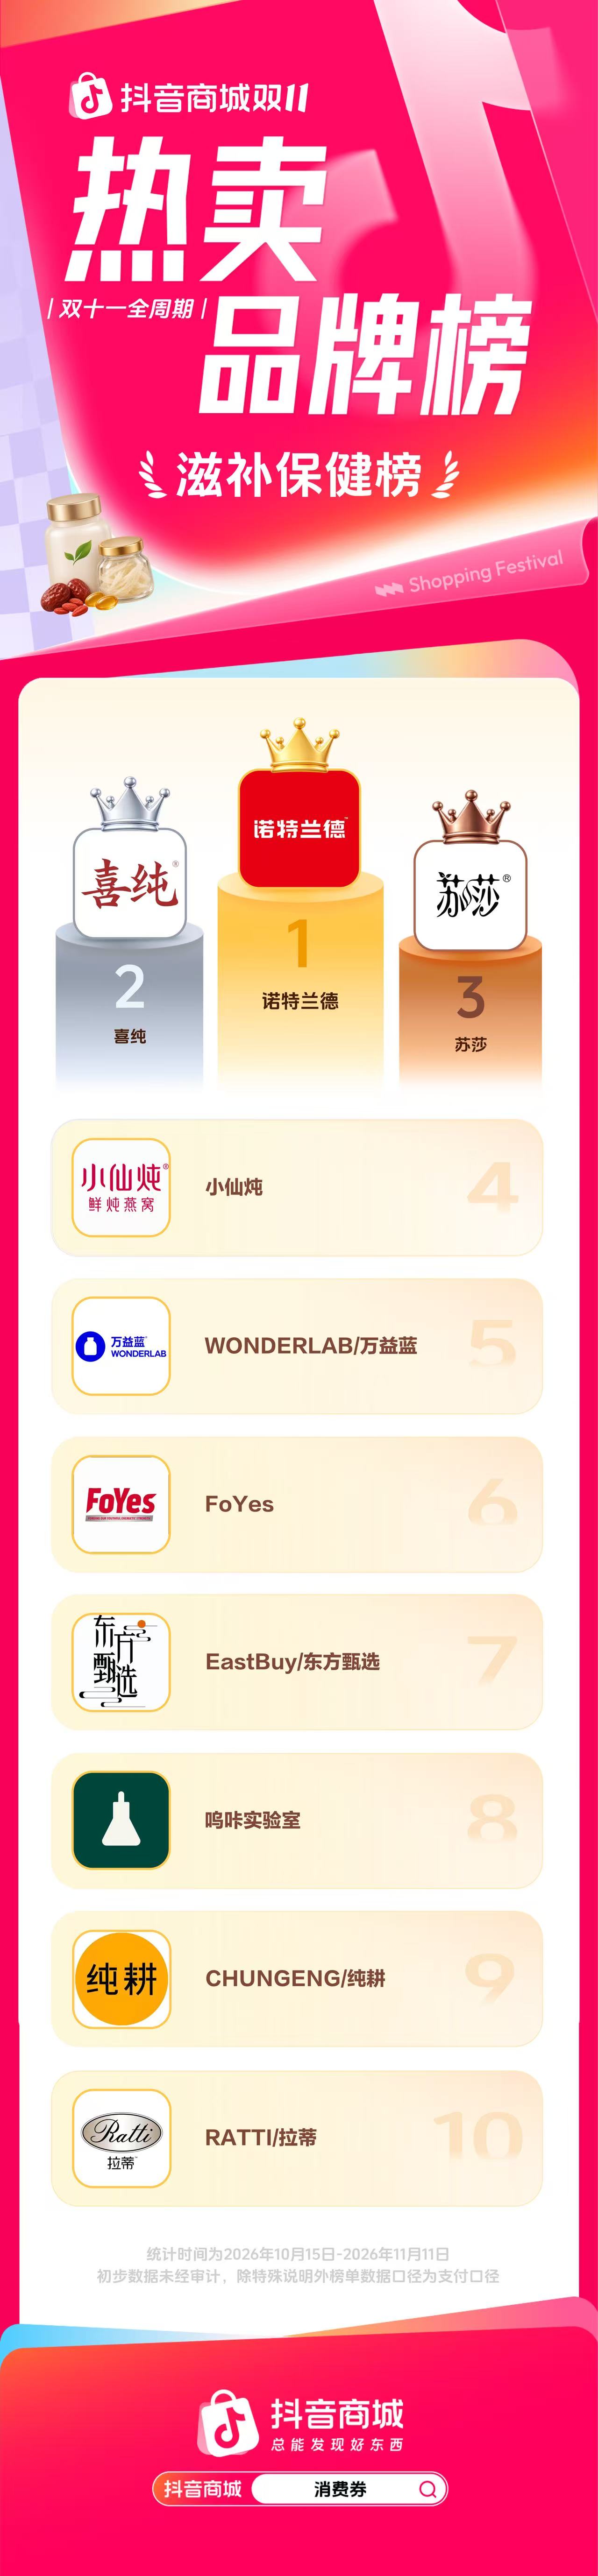
在滋补保健行业,中国品牌强势崛起,榜单前10名中全部为中国品牌。上榜品牌依次为:诺诗兰德、喜纯、苏莎 小仙炖、万益蓝、Fo Yes、东方甄选、呜咔实验室、纯耕、拉蒂。万益蓝、FoYes、拉蒂这类品牌虽然常用进口原料或国际原料商,但品牌所有权和运营主体都在国内。

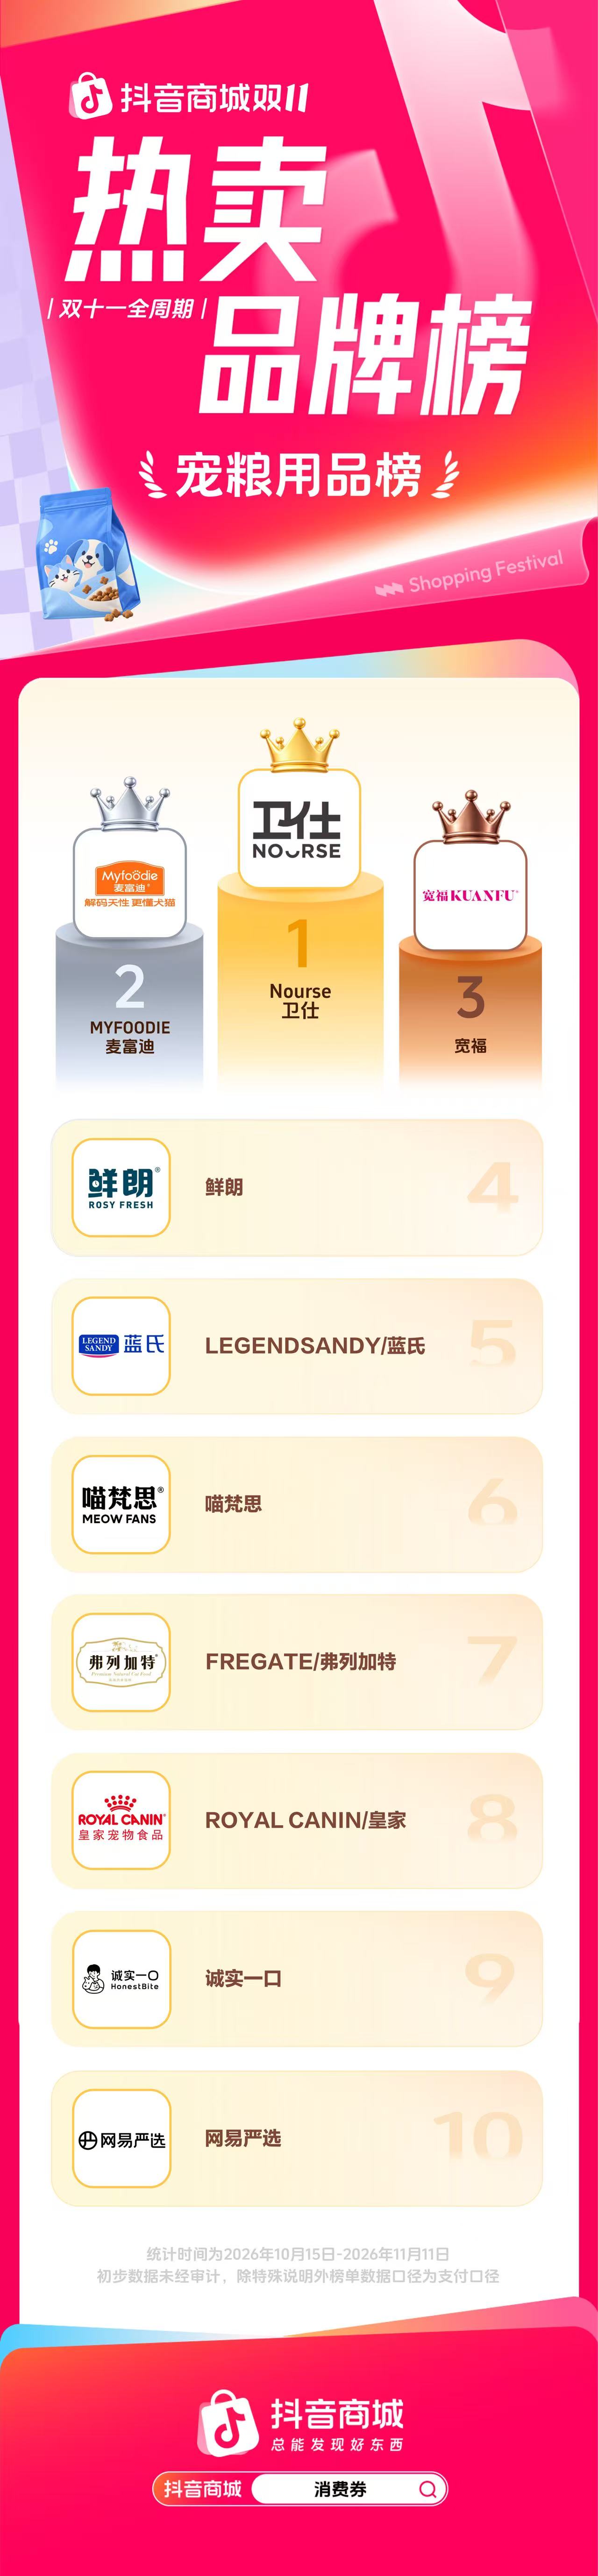
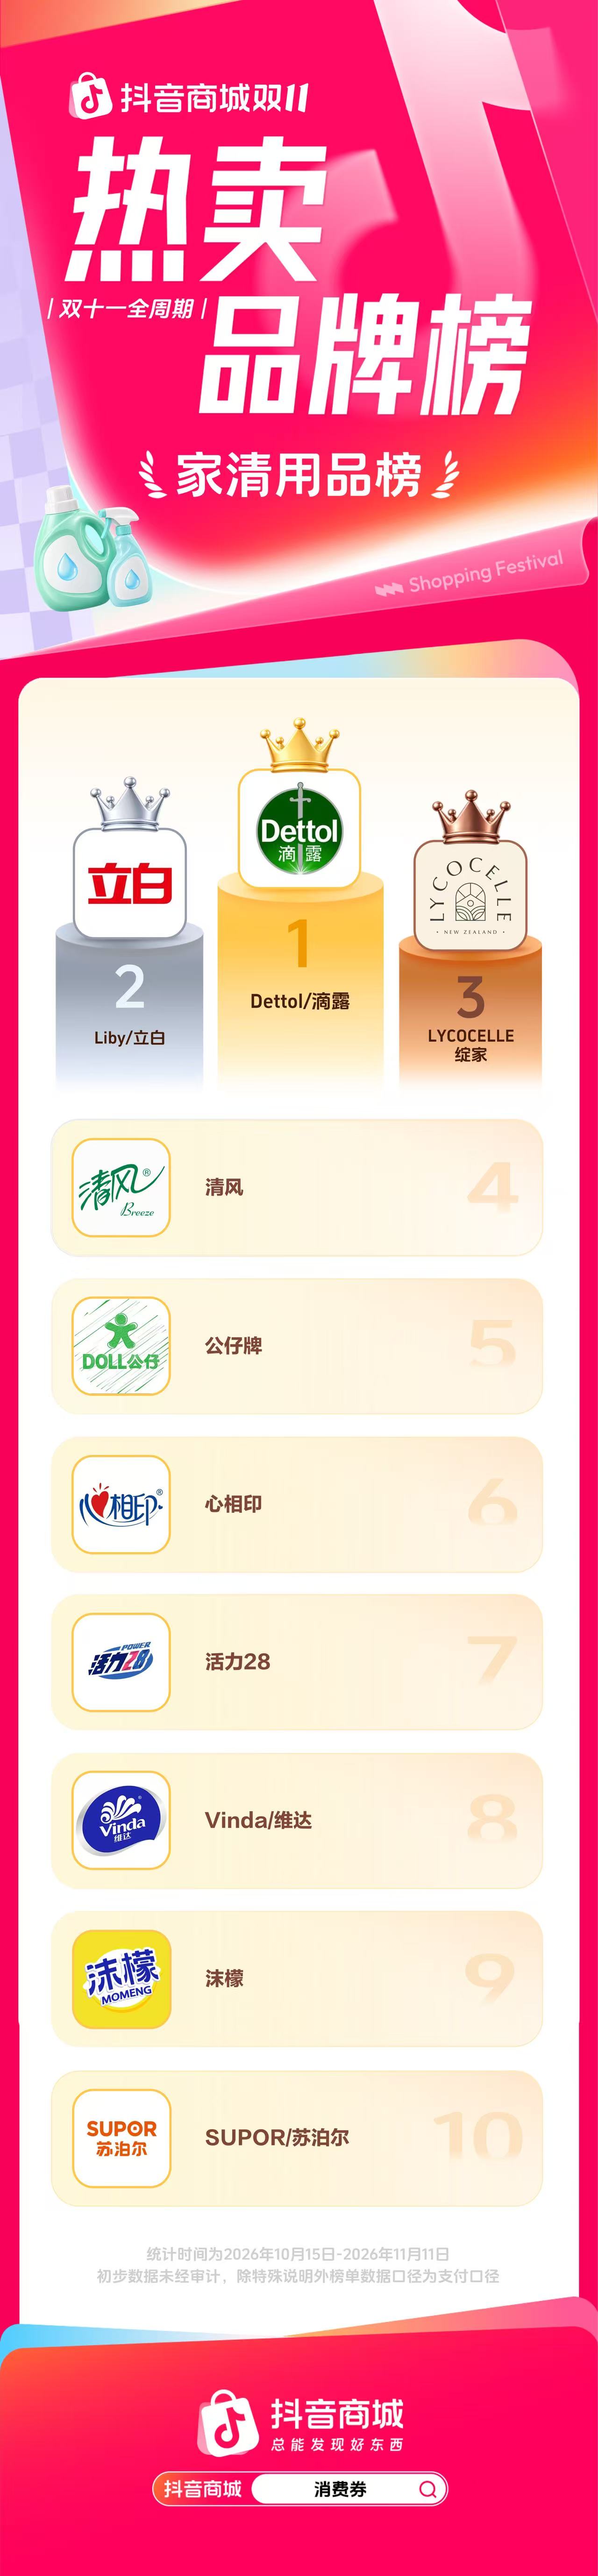
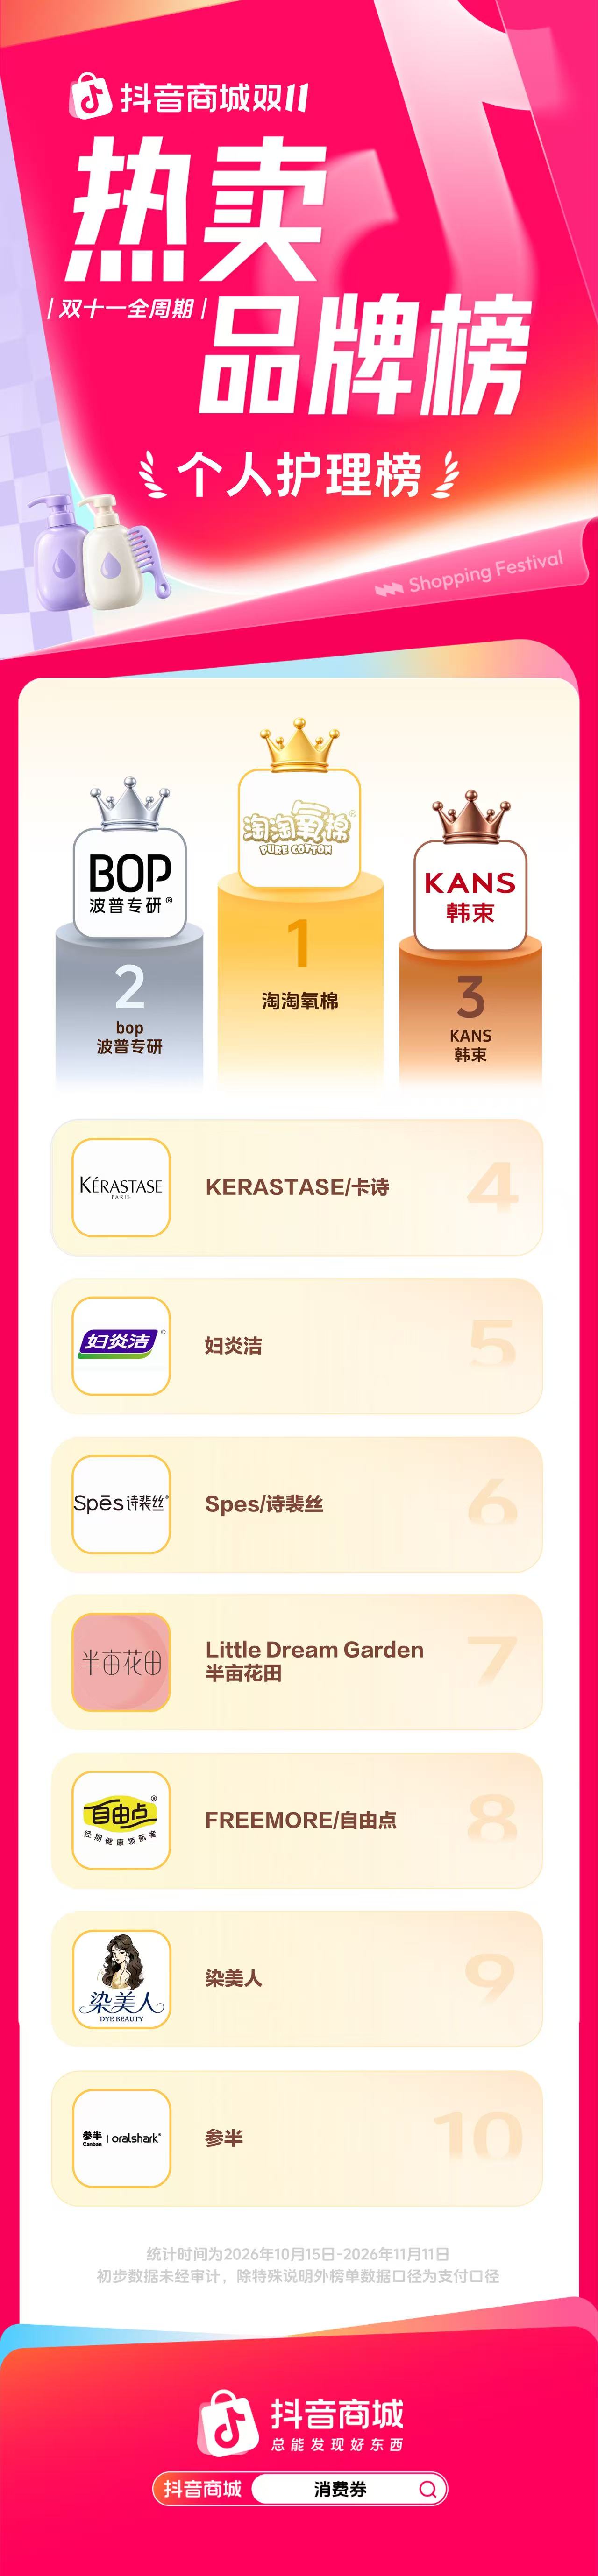
3、多类目往年霸主地位动摇,前十名里竞争依然激烈。比如去年的美容护肤榜第1名是韩束,今年它排名下降至第5名,赫莲娜拿下美容护肤第1名;今年滴露拿下家清用品第一名,而去年的冠军是蓝月亮,今年并未上榜;在个人护理榜中,去年的第3名淘淘氧棉拿下了今年的榜首;在宠粮用品榜里,第1名卫仕是去年宠物品牌榜的第3名。

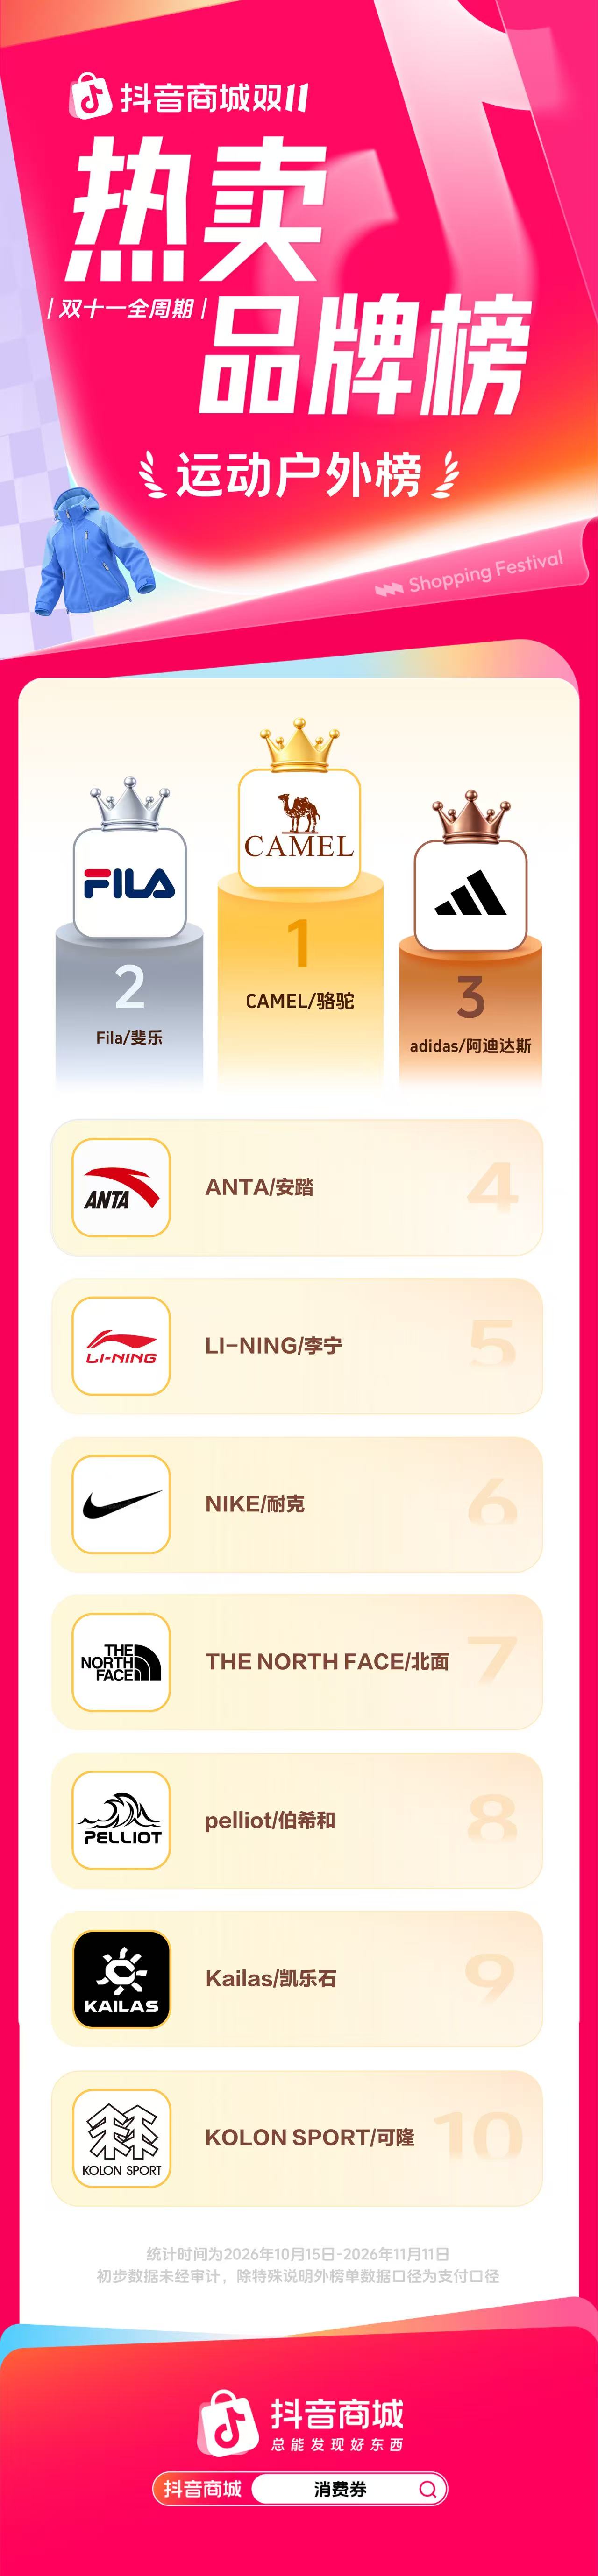
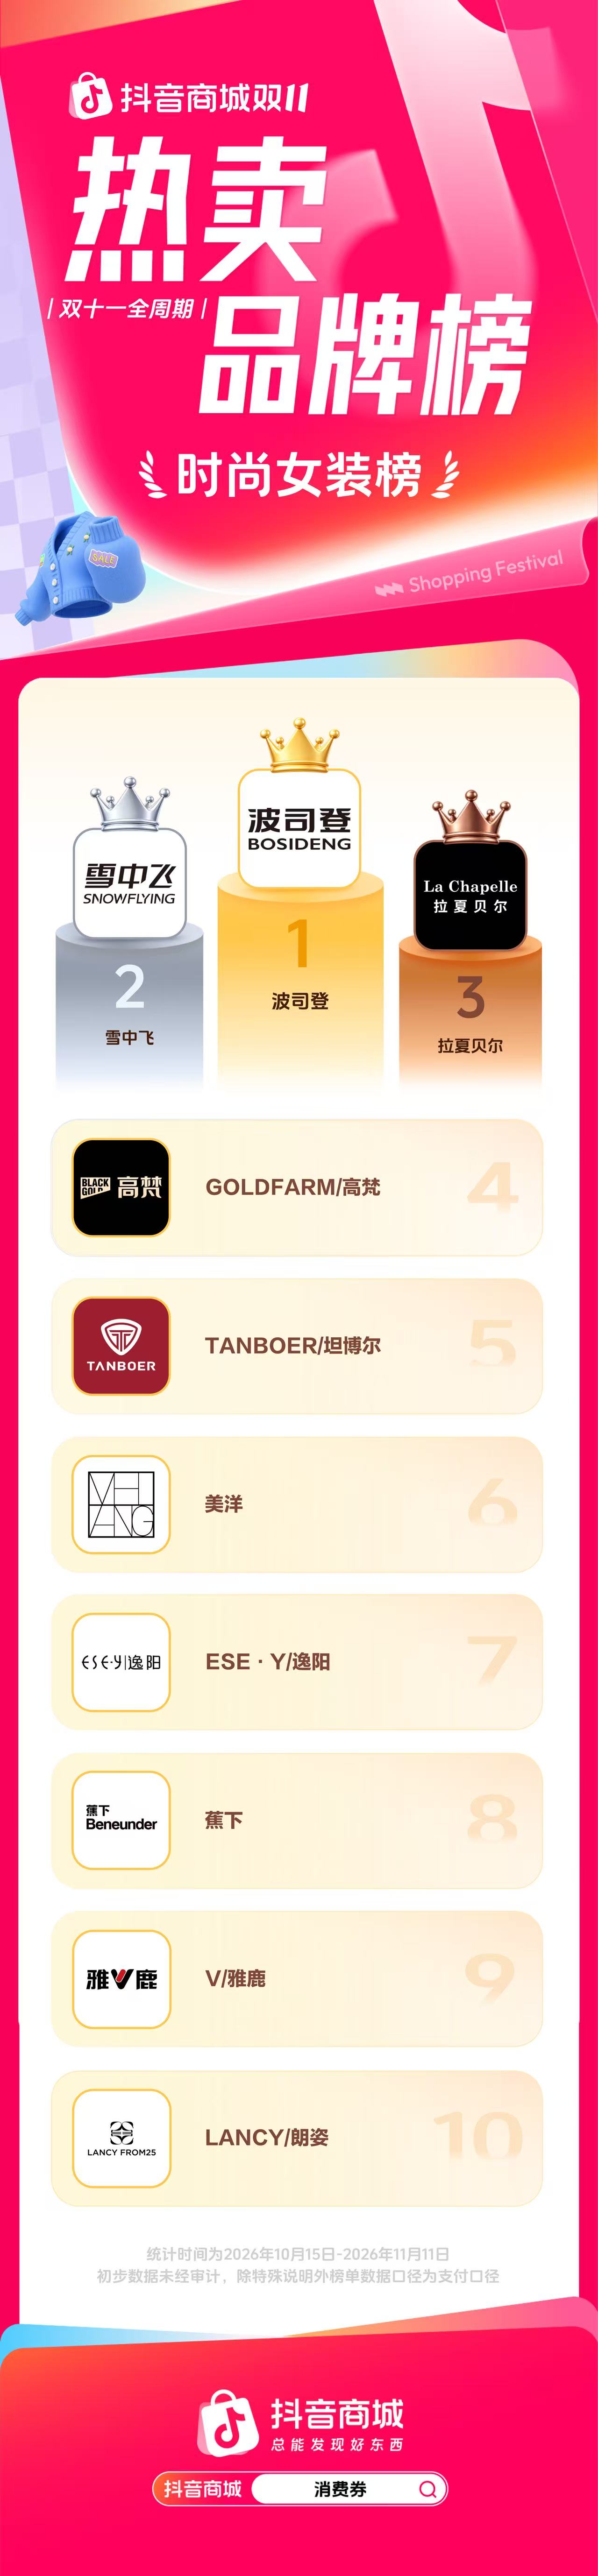
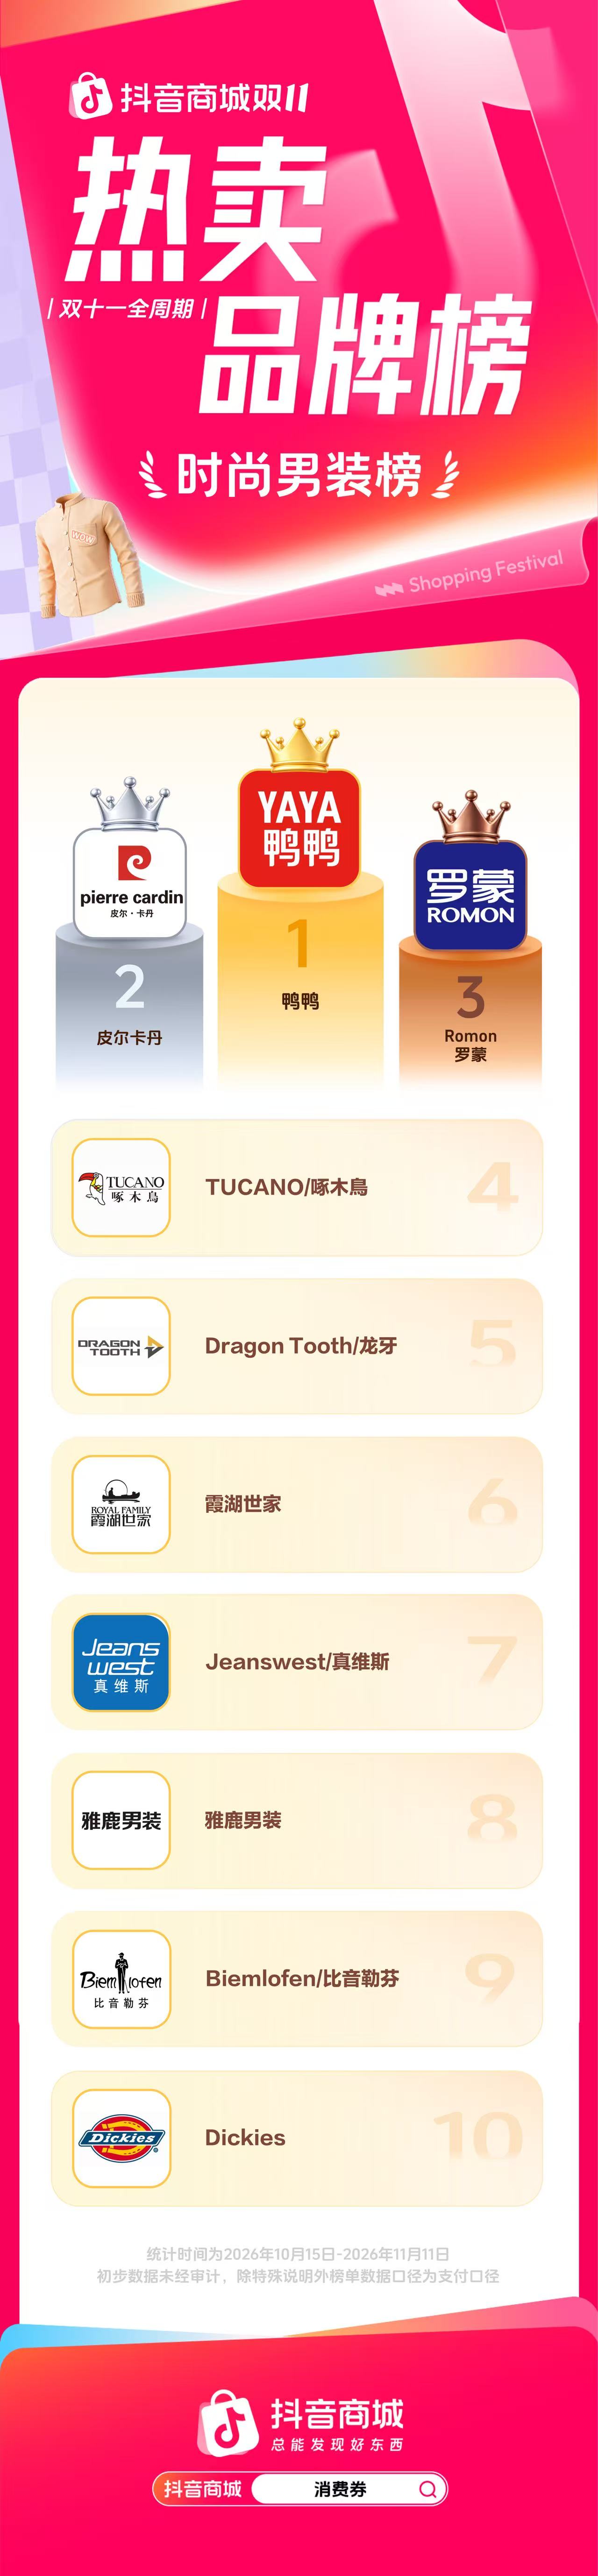
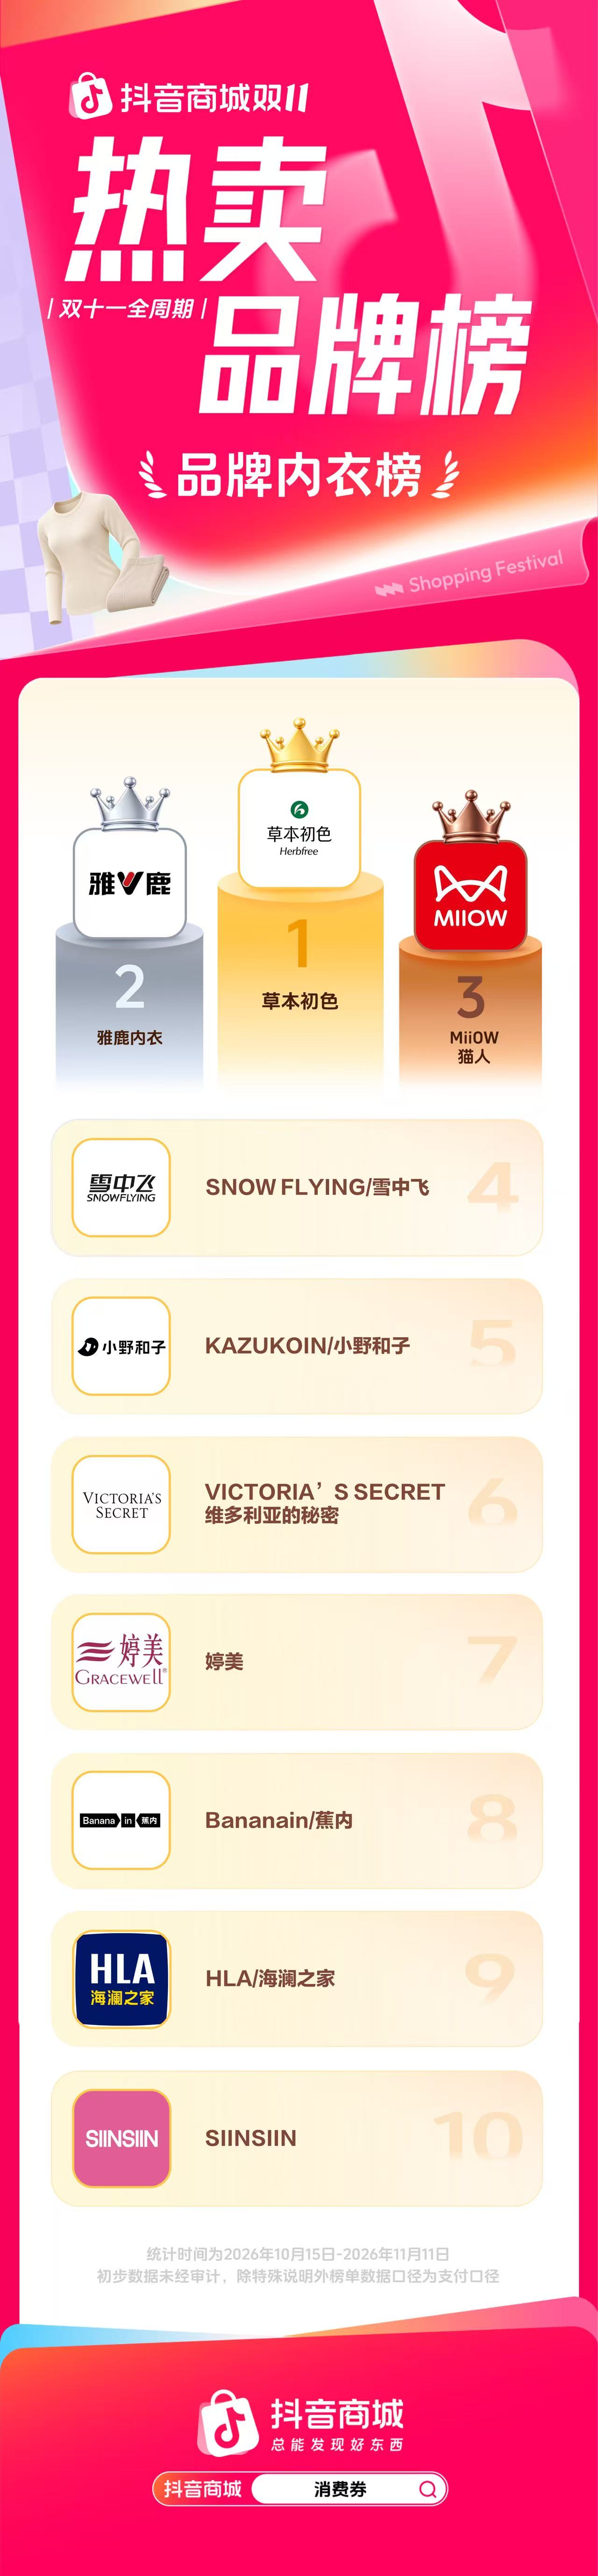
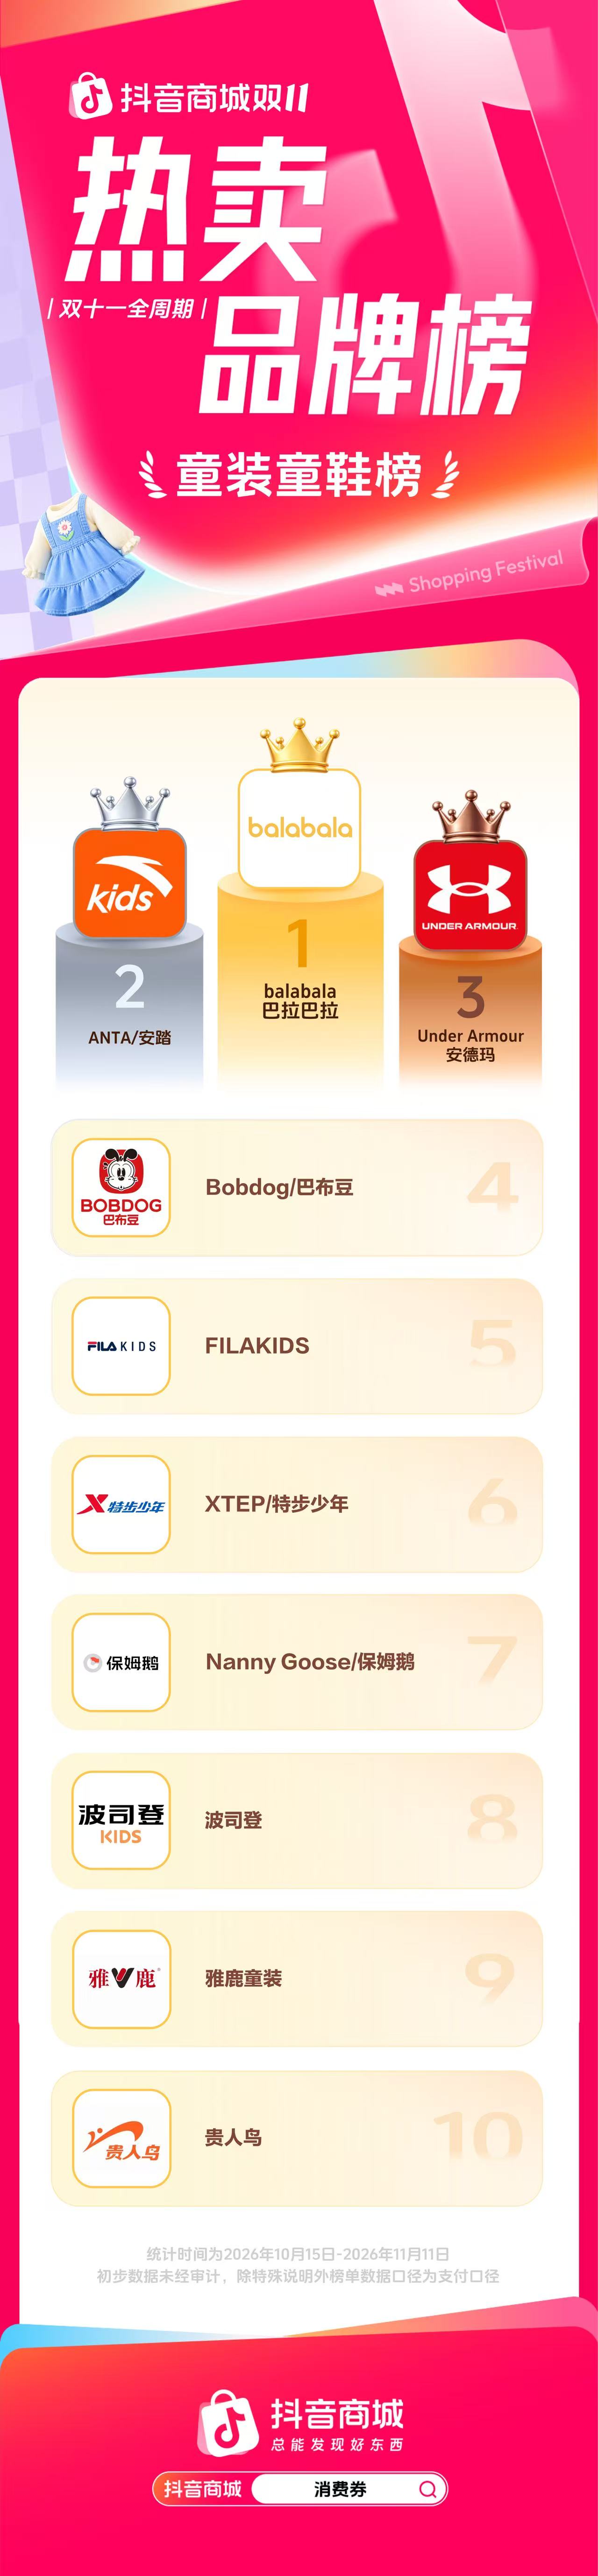
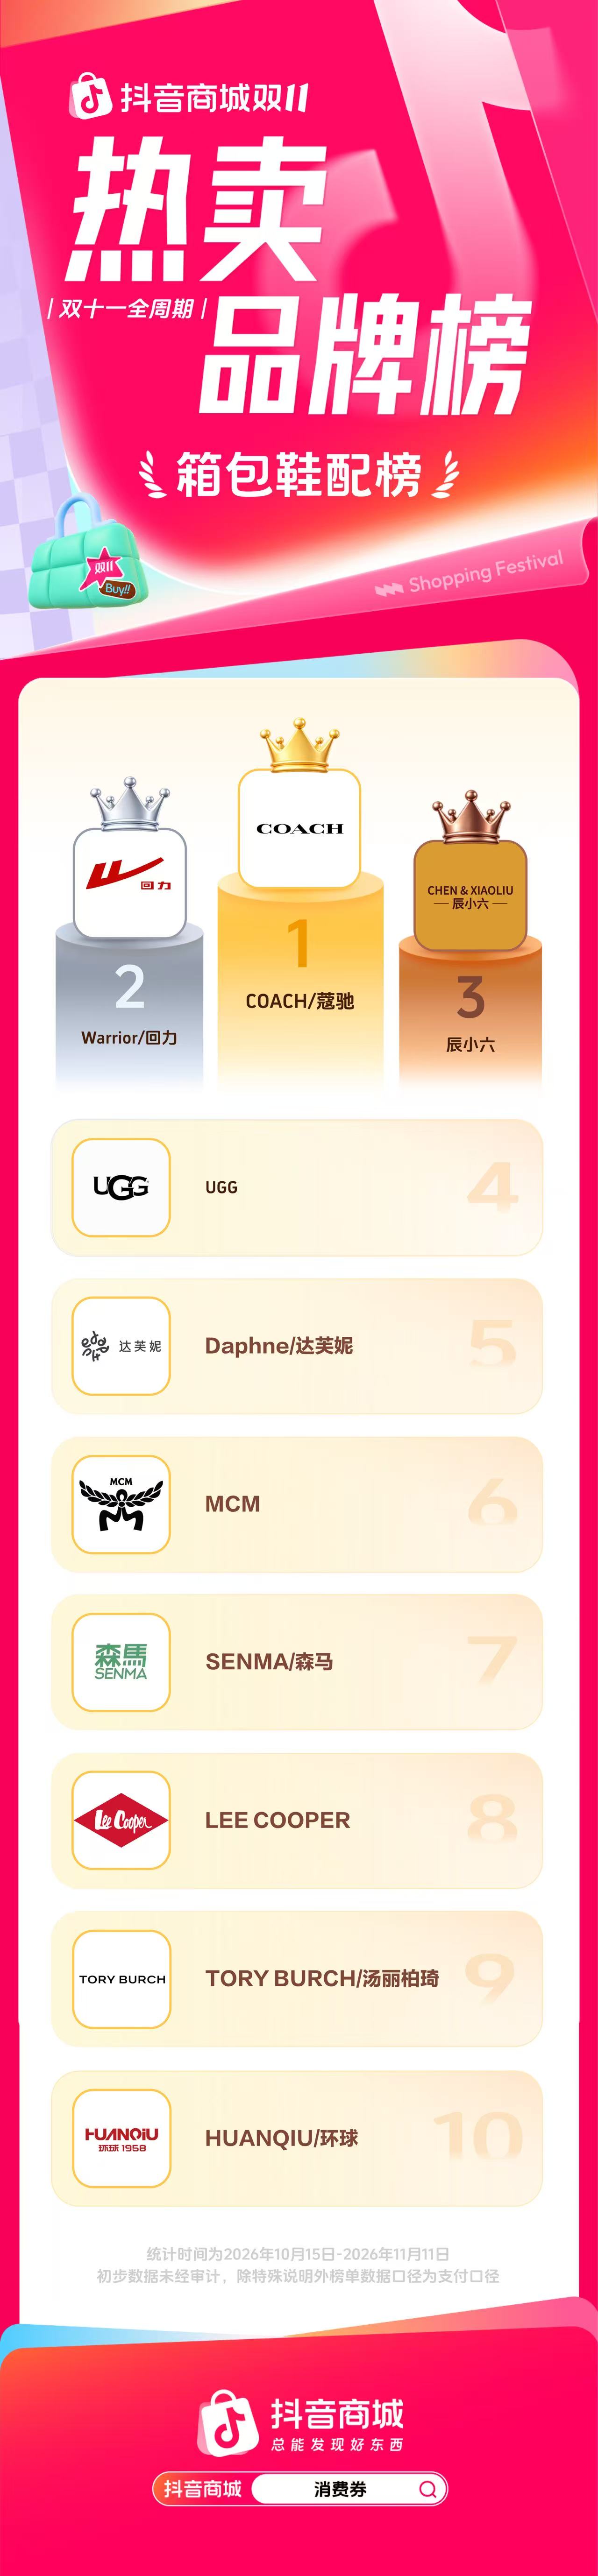
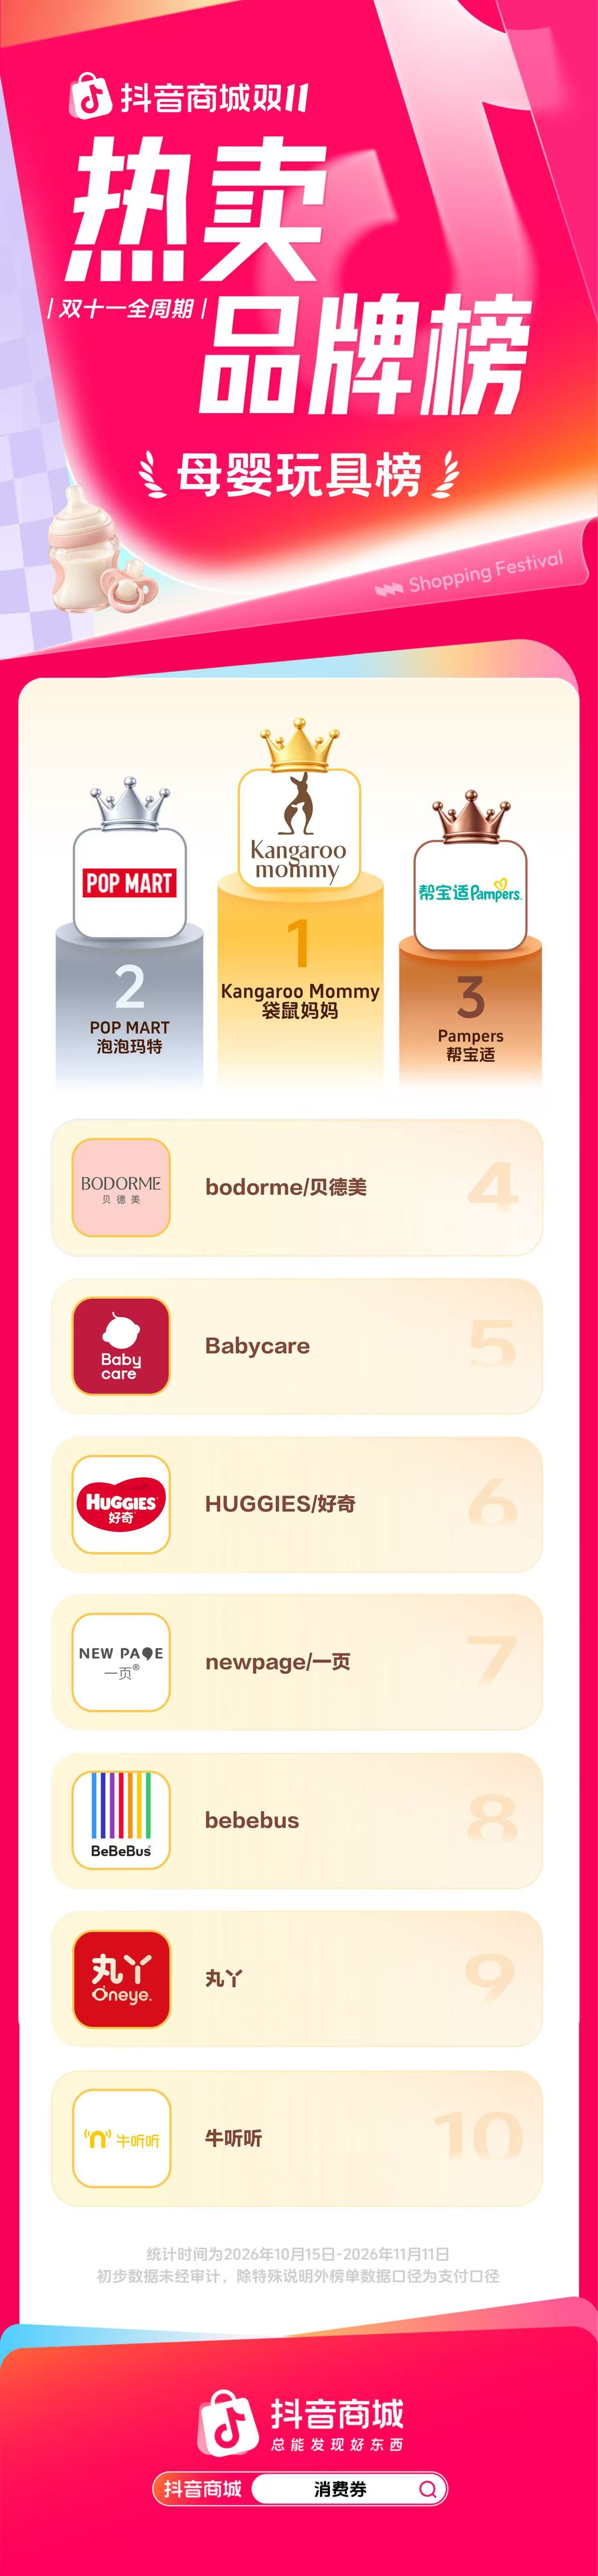
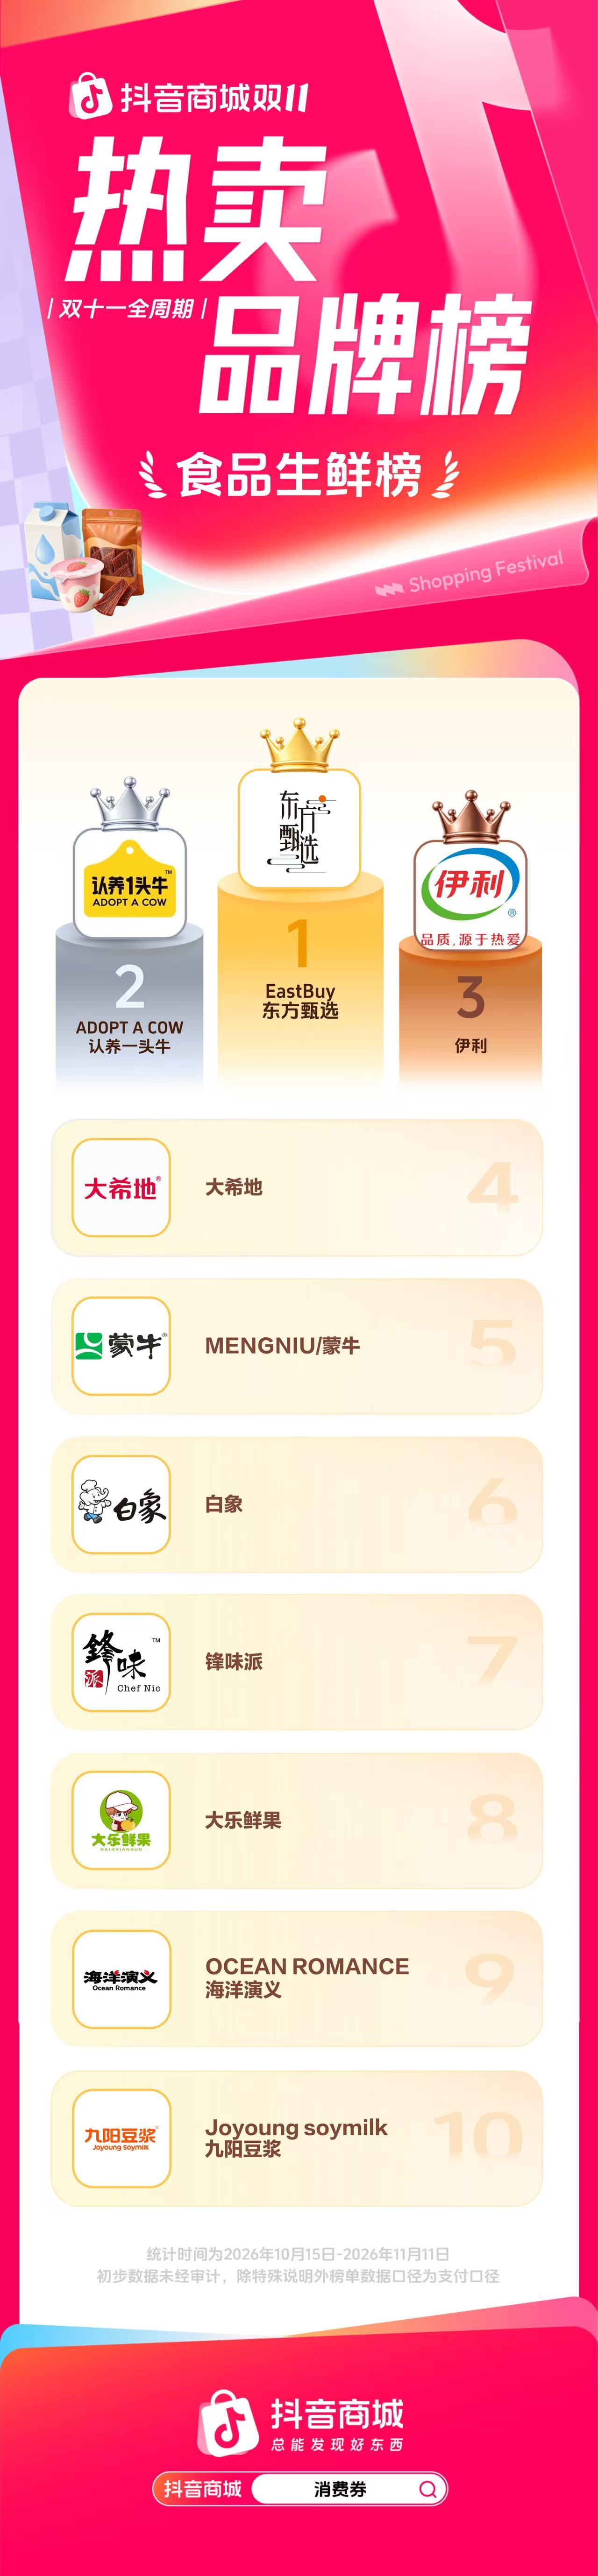
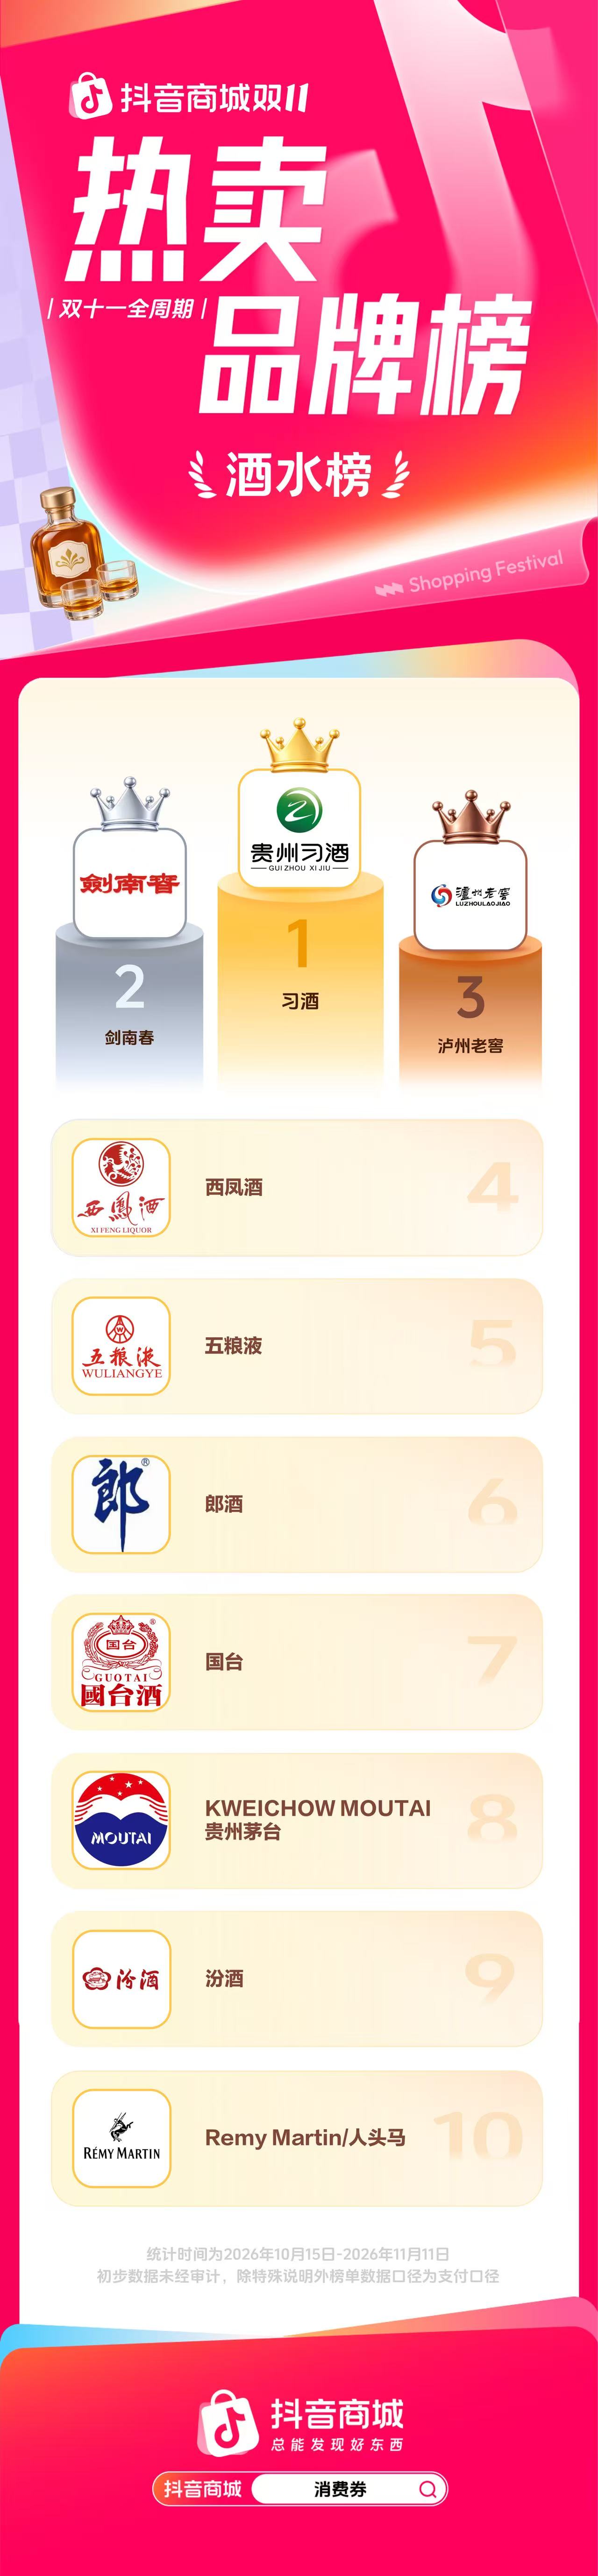
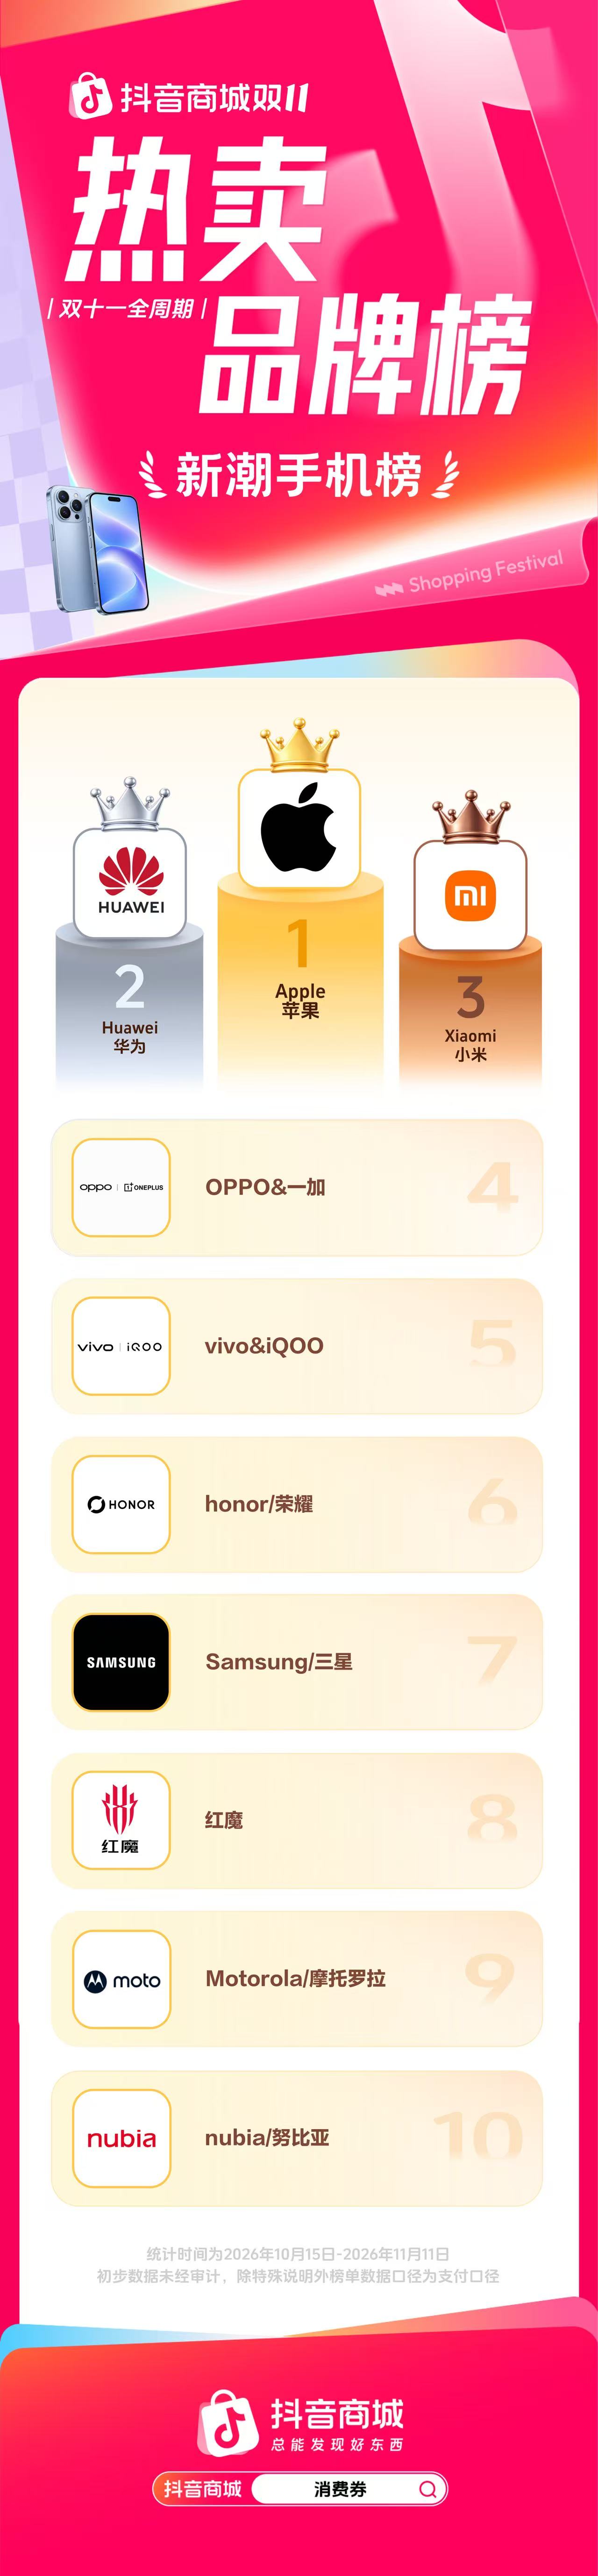
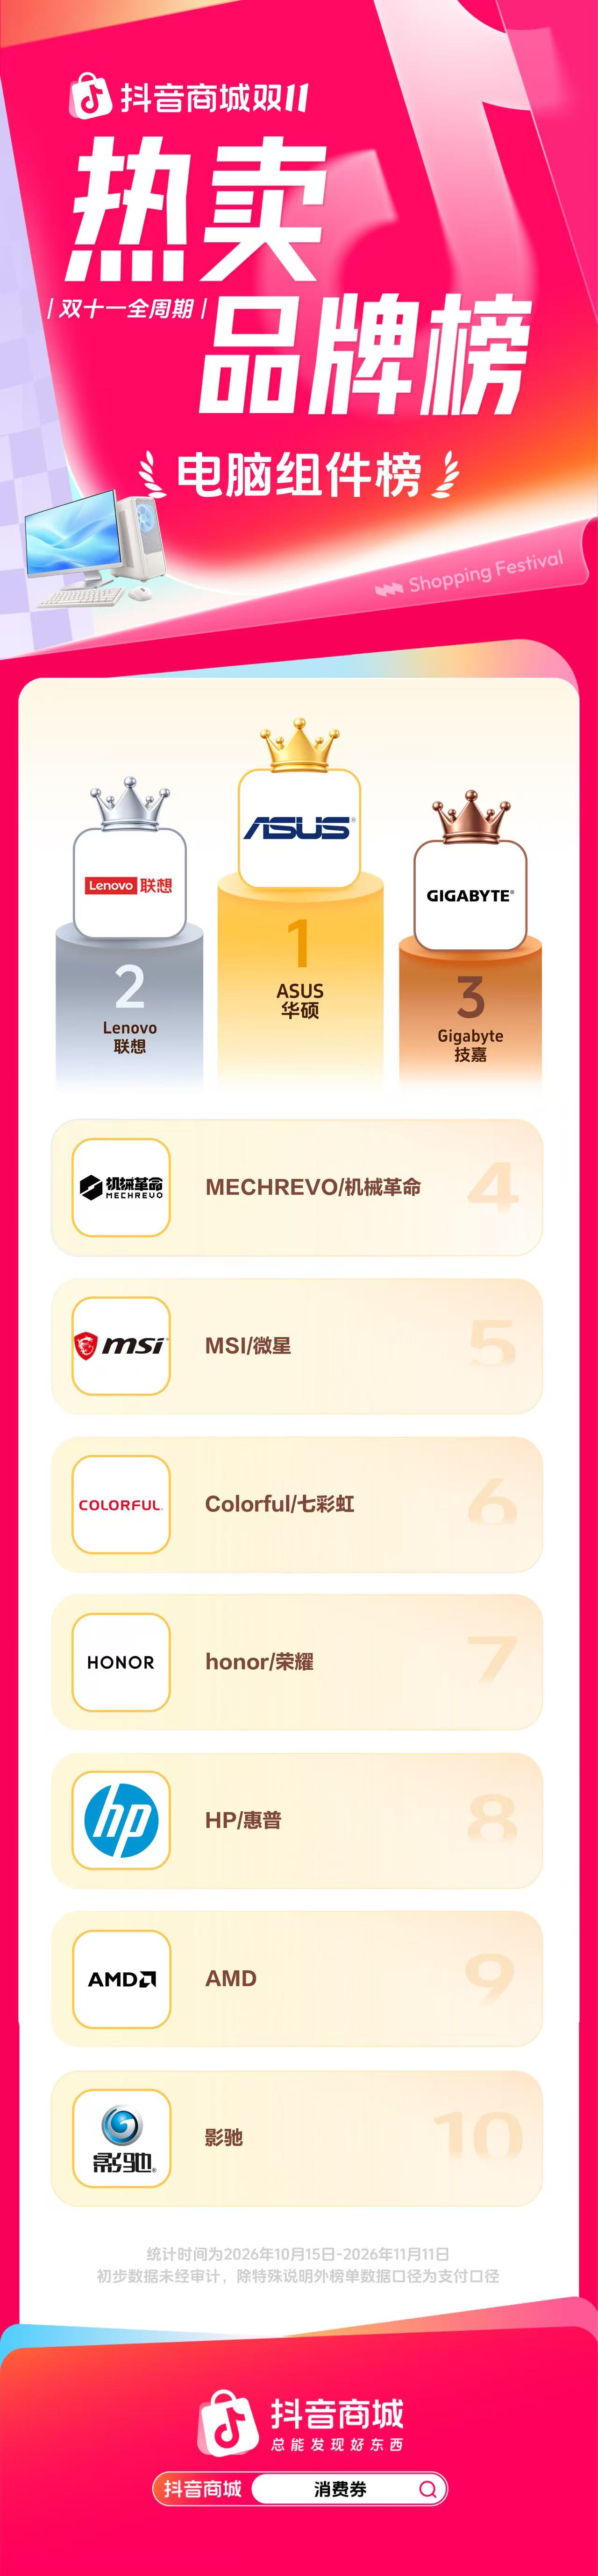
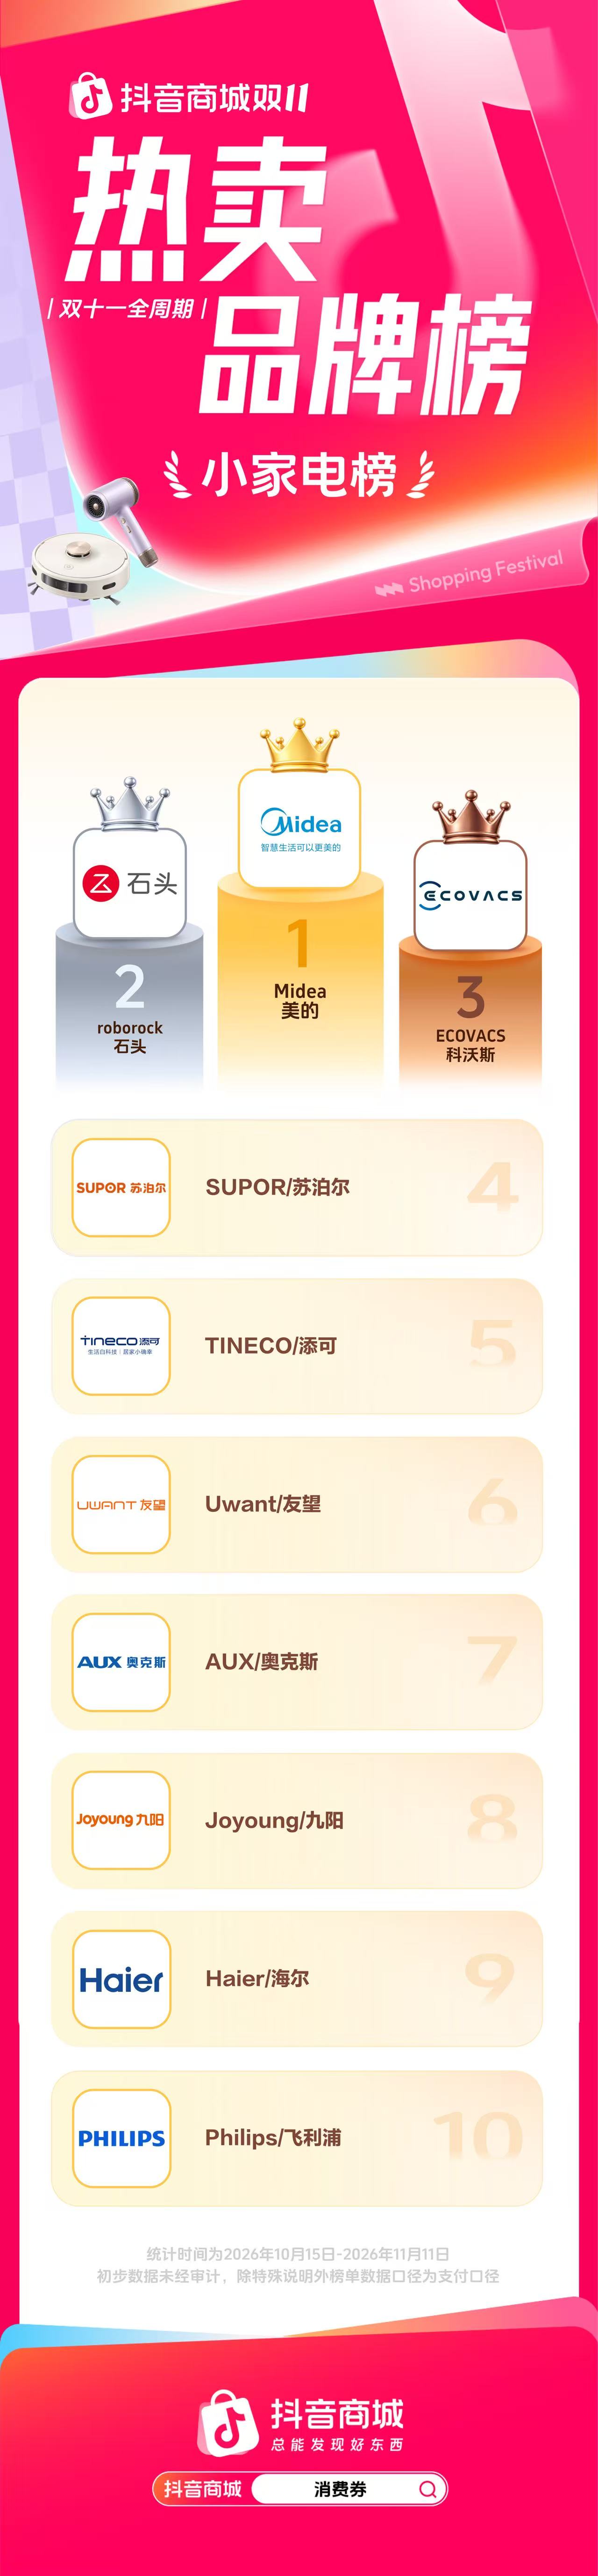
以下为2026年抖音商城双11全周期“热卖品牌榜”,数据统计口径为2026年10月15日至11月11日的支付口径:

亿邦持续追踪报道该情报,如想了解更多与本文相关信息,请扫码关注作者微信。

本文首发于 亿邦动力 官方网站

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

2026年抖音双11哪些行业增长显著?

农产品、宠物、运动户外和护肤行业增长显著,破亿品牌数量分别同比增长200%、100%、45%和35%。大促期间超2万中小商家在消费券带动下成交额破百万元,消费券带动成交额破亿商家数量同比增长15%。

2026年抖音双11美容护肤榜单发生了什么变化?

美容护肤榜首由韩束变为赫莲娜,韩束降至第5名;护肤好物榜中赫莲娜、雅诗兰黛、海蓝之谜等国际品牌占6席且整体排名超过中国品牌。2025年美容护肤榜则有50%国产品牌,韩束、珀莱雅、谷雨排名靠前。

抖音双11趋势男装榜有哪些代表品牌和定位?

秦磊男装第1,依靠主理人IP主打“奢侈品牌设计语言、亚洲身材版型”的平替老钱风;南乙第2,杭州起家的平价快时尚,走韩系简约、极简与中式复古日常实穿路线;悍石第3,来自常熟产业带,转向防水、透湿、耐磨的高性价比国货户外。

抖音双11趋势女装榜有哪些新锐品牌?

TWOI第2,凭主理人“奶油风”审美、限量周边和社群运营吸引用户;WIEI第5,依靠自研面料和版型设计做高级感极简风格;RENATHING第7由武晓娜主理,主打轻懒主义;Z.blues第8依靠丝毛棉麻外贸高货。

抖音双11运动户外与服饰榜单的国潮表现如何?

服饰户外榜有一半以上为中国品牌,骆驼第1、伯希和第3;服饰运动榜仅30%为中国品牌,安踏第3、李宁第4、特步第8。滋补保健榜前10名全部为中国品牌。

这么好看,分享一下?

朋友圈 分享

APP内打开

赞 +1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0