广告
加载中

销售额同比增长超160% 华润啤酒在淘宝闪购跑出即时零售“加速度”

龚作仁 2026-10-16 11:00
龚作仁 2026/10/16 11:00

邦小白快读

EN
全文速览

重点信息:即时零售成为啤酒消费新场景,华润啤酒在淘宝闪购上半年销售额同比增长超160%。

1. 啤酒订单集中在21至23时,占比45.7%,居家微醺、深夜小酌是非现饮场景的增长点。

2. 精酿、果啤等新兴品类在即时零售渠道的客单价较传统渠道高约30%,消费者愿意为特色酒饮多花钱。

3. 一线和新一线城市贡献近半订单,25至40岁人群是主流,高客单消费占比超五成。

消费变化带来的购买提示:酒类即时零售市场2025年已突破500亿元,未来数年预计保持约50%复合增速。

1. 使用淘宝闪购等即时零售渠道,可以更便捷地买到喜力、老雪、红爵等高端啤酒,这些品牌销量增速较猛。

2. 观赛、聚会、独酌等场景下的啤酒消费更加即时,平台还推出冰杯加啤酒等组合体验。

高端化与即时零售深度交汇,成为品牌增长关键。

1. 华润啤酒上半年营业额242.4亿元增1.2%,销量660万千升增1.7%。次高及以上啤酒销量增幅超10%,普高档及以上增约15%,喜力增超20%,老雪超40%,红爵超80%。

2. 即时零售承接高端化红利,华润啤酒在淘宝闪购同比增速超160%。

消费趋势与用户行为。

1. 啤酒消费场景从商务宴请转向居家微醺,2至4人小型餐饮占比升至58%,饮酒动机偏向情绪自愈、独饮小聚、户外和深夜微醺。

2. 啤酒订单21至23时占比45.7%;精酿果啤在即时零售客单价较传统渠道高约30%,淘宝闪购用户年轻化高购买力,高客单消费占比超五成。

可借鉴的场景营销打法。

1. 以消费情绪为锚点,用OAIPL全链路运营将观赛、聚会、独酌转化为营销场景。

2. 欧冠星耀日带动喜力GMV增200%;世界杯橙就时刻品牌GMV增64%,全域曝光超4.6亿次;冰杯加啤酒活动AIPL人群资产环比增14%,广东GMV增127%。

增长市场:即时零售啤酒赛道快速放量。

1. 华润啤酒在淘宝闪购销售额同比增长超160%,淘宝闪购啤酒品类日均销售额大幅增长,消费用户数攀升。

2. 酒类即时零售市场规模2025年已突破500亿元,预计未来数年保持约50%复合增速。

消费需求变化带来新机会。

1. 啤酒消费从社交应酬转向情绪自愈,2至4人小型餐饮场景占比升至58%,居家微醺、深夜喝啤酒等非现饮场景增长。

2. 一线和新一线城市贡献近半订单,25至40岁人群是主流,高客单消费超五成,精酿果啤在即时零售渠道客单价高约30%。

可学习合作模式与风险提示。

1. 与淘宝闪购强强联合,借助平台流量资源、OAIPL全链路运营和阿里生态的高德、飞猪、优酷等触点,实现全域触达。

2. 案例显示,世界杯品牌活动GMV增64%并获4.6亿曝光,冰杯加啤酒活动广东GMV增127%,说明场景化联合营销可复制。

3. 注意啤酒行业已进入存量博弈,传统商务宴席、多人宴席场景持续收缩,需要及时向即时零售和新场景转移。

产品生产设计方向:高端化和特色品类更受即时零售渠道欢迎。

1. 华润啤酒次高及以上啤酒销量增幅超10%,普高档及以上增约15%,喜力、老雪、红爵增速分别超20%、40%、80%。

2. 精酿、果啤等新兴品类在即时零售客单价较传统渠道高约30%,说明高端、特色酒饮能支撑更高售价。

消费场景变化对生产启示。

1. 啤酒消费以居家微醺、独饮小聚、深夜小酌等非现饮场景为主,2至4人小型餐饮场景占58%,产品设计需要匹配小聚、自饮和夜宵需求。

2. 21至23时订单占啤酒品类45.7%,夜宵时段是核心消费场景,适合开发小规格、便捷组合装等即时消费产品。

数字化电商启示。

1. 即时零售平台用户画像清晰:一线新一线贡献近半订单,25至40岁为主,高客单消费超五成,可据此指导产品定位。

2. 平台能通过OAIPL全链路运营沉淀人群资产,工厂可借助平台数据反向优化生产和选品。

行业趋势:酒类即时零售处于快速扩张期。

1. 2025年国内酒类即时零售市场规模已突破500亿元,预计未来数年保持约50%复合增速。

2. 啤酒行业存量博弈下,即时零售正在成为承接高端酒饮消费的核心渠道,华润啤酒在淘宝闪购增速超160%。

客户痛点:啤酒品牌要找存量下的新增长点。

1. 商务佐餐、多人宴席场景持续收缩,2至4人小型餐饮场景已升至58%,品牌需要承接居家、户外、深夜微醺等新场景。

2. 从规模增长转向价值增长,高端化产品需要找到能匹配高消费力的即时场景。

可复用解决方案。

1. 场景营销:把观赛、聚会、独酌等消费时刻转化为可运营营销场景,将场景红利变成商业增量。

2. 数字化运营:用OAIPL全链路运营实现从流量触达到用户沉淀,品牌AIPL人群资产可量化提升。

3. 全域联动:借助阿里生态的高德、飞猪、优酷等触点导入流量,配合地铁、球迷市集等线下触点,实现全域曝光。

4. 案例数据:欧冠星耀日喜力GMV增200%,世界杯橙就时刻品牌GMV增64%和曝光4.6亿,冰杯加啤酒活动广东GMV增127%。

平台增长机会:啤酒即时零售成为平台增量品类。

1. 淘宝闪购啤酒品类快速增长,华润啤酒在平台跑出超160%的销售同比增速,消费用户数持续攀升。

2. 啤酒订单集中在21至23时,占比45.7%,一线和新一线城市贡献近半订单,25至40岁人群为主,高客单占比超五成,平台可围绕这些时段和人群做运营。

平台最新做法。

1. 以消费情绪为分发逻辑,区别于传统电商货架逻辑,将微醺、聚会等时刻转化为即时购买。

2. 使用OAIPL全链路运营,帮助品牌沉淀AIPL人群资产,形成流量触达到用户沉淀闭环。

3. 联动阿里生态业务,在高德地图、飞猪旅行、优酷等触点导入全域流量,并配合线下地铁、球迷市集等品牌触点。

招商与运营启示。

1. 平台可联合品牌做场景营销,例如欧冠星耀日、世界杯橙就时刻、冰杯加啤酒活动,均能显著带动GMV。

2. 高端啤酒在即时零售渠道有更高客单价,精酿果啤比传统渠道高约30%,平台可重点吸引高端酒饮品牌。

3. 平台商还可以帮助品牌实现跨场景全域曝光,例如世界杯活动曝光超4.6亿次,显示流量整合能力是合作价值。

产业新动向:即时零售从补充渠道演变为独立消费场景,成为啤酒行业第二增长曲线。

1. 华润啤酒将高端化战略与即时零售深度融合,上半年营业额242.4亿元增1.2%,销量660万千升增1.7%。

2. 次高及以上啤酒销量增幅超10%,普高档及以上增约15%,高端化在即时零售渠道跑出超160%增速。

消费结构与场景变化。

1. 传统商务宴席收缩,2至4人小型餐饮场景占比升至58%,饮酒动机转向情绪自愈、独饮小聚、居家户外、深夜微醺。

2. 啤酒订单21至23时占比45.7%,精酿果啤在即时零售客单价较传统渠道高约30%,高客单消费占比超五成。

商业模式案例。

1. 平台以消费情绪为锚点,用OAIPL全链路运营将观赛聚会等时刻变成可运营场景,依靠阿里生态跨端导流,形成流量到用户的闭环。

2. 喜力欧冠星耀日GMV增200%,雪花世界杯GMV增64%,冰杯加啤酒活动AIPL人群环比增14%,广东GMV增127%。

启示:酒类即时零售市场2025年突破500亿元,预计未来数年复合增速约50%,为存量竞争下的啤酒高端化提供了新路径,行业应重视非现饮场景和情绪消费的运营。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

Key takeaways: Instant retail has become a new beer consumption scenario. China Resources Beer's sales on Taobao Flash Purchase grew more than 160% year-on-year in the first half.

1. Beer orders are concentrated between 21:00 and 23:00, accounting for 45.7%, with at-home tipsiness and late-night drinking becoming key growth points in off-premise scenarios.

2. Emerging categories such as craft beer and fruit beer command an average order value roughly 30% higher on instant retail platforms than in traditional channels; consumers are willing to pay more for distinctive beer drinks.

3. Tier-1 and new tier-1 cities contribute nearly half of orders, adults aged 25-40 are the main consumers, and high-ticket orders account for more than half of spending.

Shopping implications from changing consumption: The instant retail alcohol market surpassed RMB 50 billion in 2025 and is expected to maintain a compound annual growth rate of about 50% in the coming years.

1. Through instant retail channels such as Taobao Flash Purchase, consumers can more conveniently buy high-end beers including Heineken, Laoxue, and Hongjue, all of which are growing rapidly.

2. Beer consumption in scenarios like watching matches, gathering with friends, and solo drinking has become more immediate; platforms have also introduced combined experiences such as ice-cup beer pairings.

Premiumization and instant retail are converging deeply, becoming key to brand growth.

1. China Resources Beer posted first-half revenue of RMB 24.24 billion, up 1.2%, and sales volume of 6.6 million kiloliters, up 1.7%. Sales of sub-premium and above beers grew over 10%, popular-premium and above rose about 15%, Heineken grew over 20%, Laoxue over 40%, and Hongjue over 80%.

2. Instant retail is capturing the benefits of premiumization: China Resources Beer's sales on Taobao Flash Purchase grew over 160% year-on-year.

Consumer trends and user behavior.

1. Beer consumption is shifting from business dinners to at-home tipsiness; 2-to-4-person small dining occasions have risen to 58%, and drinking motivations are oriented toward emotional self-care, solo drinking and casual gatherings, outdoor settings, and late-night tipsiness.

2. Orders between 21:00 and 23:00 account for 45.7%; craft beer and fruit beer carry an average order value about 30% higher on instant retail than in traditional channels. Taobao Flash Purchase users skew young with high purchasing power, and high-ticket orders account for over half of spending.

Reusable occasion-based marketing playbooks.

1. Use consumption emotions as an anchor and apply OAIPL full-funnel operations to turn watching games, gatherings, and solo drinking into marketing scenarios.

2. The UEFA Champions League Star Day boosted Heineken GMV by 200%; the World Cup Orange Moment campaign lifted brand GMV by 64% with over 460 million omnichannel exposures; the ice-cup-beer campaign increased AIPL audience assets by 14% month-on-month and drove GMV in Guangdong up 127%.

Growth market: The instant-retail beer segment is scaling up quickly.

1. China Resources Beer's sales on Taobao Flash Purchase grew over 160% year-on-year; daily sales of the beer category on Taobao Flash Purchase rose sharply, and the number of consumers climbed.

2. The instant retail alcohol market surpassed RMB 50 billion in 2025 and is expected to maintain about 50% CAGR over the next several years.

New opportunities from changing consumer demand.

1. Beer consumption is shifting from social entertaining to emotional self-care; 2-to-4-person small dining scenarios rose to 58%, and off-premise scenarios such as drinking at home and late-night beer are growing.

2. Tier-1 and new tier-1 cities contribute nearly half of orders, adults aged 25-40 are the mainstream consumers, and high-ticket orders account for over 50%. Craft beer and fruit beer have an average order value about 30% higher on instant retail than in traditional channels.

Cooperation models and risk reminders.

1. Partner with Taobao Flash Purchase to leverage its traffic resources, OAIPL full-funnel operations, and Alibaba ecosystem touchpoints such as Amap, Fliggy, and Youku to achieve omnichannel reach.

2. Cases show that the World Cup brand campaign raised GMV by 64% and secured 460 million exposures, while the ice-cup-beer campaign increased Guangdong GMV by 127%, demonstrating that scenario-based joint marketing is replicable.

3. Note that the beer industry has entered competition over existing market share; traditional business banquets and large-party occasions continue to shrink, so sellers need to shift promptly toward instant retail and new consumption scenarios.

Product design and production direction: Premiumization and specialty categories are more favored by instant retail channels.

1. China Resources Beer's sub-premium and above beer sales grew over 10%; popular-premium and above rose about 15%; Heineken, Laoxue, and Hongjue grew over 20%, 40%, and 80%, respectively.

2. Craft beer and fruit beer have an average order value about 30% higher on instant retail than in traditional channels, showing that high-end and specialty drinks can support higher price points.

Implications of shifting consumption scenarios for production.

1. Beer consumption is dominated by off-premise scenarios such as home tipsiness, solo drinking and small gatherings, and late-night drinking; 2-to-4-person small dining accounts for 58%. Product design should match the needs of small gatherings, self-drinking, and late-night snack occasions.

2. Orders from 21:00 to 23:00 account for 45.7% of beer category orders; late-night snack time is the core consumption scenario, making small-format, convenient bundle packs suitable for immediate consumption.

Digital and e-commerce implications.

1. Instant retail platforms have a clear user profile: Tier-1 and new tier-1 cities contribute nearly half of orders, users aged 25-40 dominate, and high-ticket consumption accounts for over 50%; manufacturers can use this to guide product positioning.

2. Platforms can accumulate audience assets through OAIPL full-funnel operations; factories can use platform data to reverse-optimize production and product selection.

Industry trend: The alcohol instant-retail market is expanding rapidly.

1. In 2025, China's alcohol instant-retail market exceeded RMB 50 billion and is expected to maintain a CAGR of about 50% in the coming years.

2. As the beer industry competes over existing market share, instant retail is becoming the core channel for premium alcohol consumption; China Resources Beer's growth on Taobao Flash Purchase exceeded 160%.

Client pain points: Beer brands need new growth points within an existing-market competition.

1. Business meal drinking and large banquet occasions are shrinking, while 2-to-4-person small dining has risen to 58%; brands need to capture new scenarios such as home drinking, outdoor occasions, and late-night tipsiness.

2. Growth is shifting from scale to value; premium products need to find instant scenarios that match consumers with high purchasing power.

Reusable solutions.

1. Occasion-based marketing: Turn consumption moments such as watching games, gatherings, and solo drinking into operable marketing scenarios, converting scenario dividends into incremental business.

2. Digital operations: Use OAIPL full-funnel operations to move from traffic touchpoints to audience accumulation, with quantifiable growth in brand AIPL audience assets.

3. Omnichannel linkage: Use Alibaba ecosystem touchpoints such as Amap, Fliggy, and Youku to bring in traffic, combined with offline touchpoints like subway ads and fan fairs, to achieve omnichannel exposure.

4. Case data: Heineken GMV rose 200% on UEFA Champions League Star Day; the World Cup Orange Moment campaign lifted brand GMV by 64% and generated 460 million exposures; the ice-cup-beer campaign increased Guangdong GMV by 127%.

Platform growth opportunity: Beer instant retail is becoming an incremental category for platforms.

1. Taobao Flash Purchase's beer category is growing rapidly, with China Resources Beer achieving over 160% year-on-year sales growth on the platform and consumer numbers continuing to climb.

2. Beer orders are concentrated between 21:00 and 23:00, accounting for 45.7%; tier-1 and new tier-1 cities contribute nearly half of orders; users aged 25-40 are the core group; and high-ticket orders account for over 50%. Platforms can design operations around these time periods and consumer segments.

Latest platform practices.

1. Use consumption emotions as the distribution logic, unlike the traditional e-commerce shelf logic, and turn moments such as tipsiness and gatherings into immediate purchases.

2. Use OAIPL full-funnel operations to help brands accumulate AIPL audience assets, forming a closed loop from traffic touchpoint to user retention.

3. Integrate with Alibaba ecosystem businesses, including Amap, Fliggy, and Youku, to bring in omnichannel traffic, combined with offline brand touchpoints such as subway ads and fan fairs.

Implications for merchant recruitment and operations.

1. Platforms can collaborate with brands on occasion-based marketing; campaigns such as UEFA Champions League Star Day, World Cup Orange Moment, and ice-cup-beer all significantly boosted GMV.

2. Premium beer commands higher average order values in instant retail; craft beer and fruit beer are about 30% higher than in traditional channels, so platforms can focus on attracting high-end alcohol brands.

3. Platforms can also help brands achieve cross-scenario omnichannel exposure. For example, the World Cup campaign generated over 460 million exposures, showing that traffic integration capability is a core value of partnership.

Industry trend: Instant retail is evolving from a supplementary channel into an independent consumption scenario, becoming a second growth curve for the beer industry.

1. China Resources Beer deeply combined its premiumization strategy with instant retail; first-half revenue was RMB 24.24 billion, up 1.2%, and sales volume was 6.6 million kiloliters, up 1.7%.

2. Sub-premium and above beer sales grew over 10%, popular-premium and above grew about 15%, and premium products achieved over 160% growth on instant-retail channels.

Changes in consumption structure and scenarios.

1. Traditional business banquets are shrinking; 2-to-4-person small dining scenarios have risen to 58%, and drinking motivations are shifting toward emotional self-care, solo drinking and small gatherings, home and outdoor settings, and late-night tipsiness.

2. Orders between 21:00 and 23:00 account for 45.7% of beer orders; craft beer and fruit beer have average order values about 30% higher on instant retail than in traditional channels; and high-ticket consumption accounts for over half of spending.

Business model cases.

1. Platforms use consumption emotions as an anchor and OAIPL full-funnel operations to turn moments such as watching games and gatherings into operable scenarios, relying on cross-end traffic from the Alibaba ecosystem to form a closed loop from traffic to users.

2. Heineken's UEFA Champions League Star Day drove GMV up 200%; Snow's World Cup campaign raised GMV by 64%; the ice-cup-beer campaign increased AIPL audience assets by 14% month-on-month and lifted Guangdong GMV by 127%.

Implications: The instant-retail alcohol market surpassed RMB 50 billion in 2025 and is expected to grow at about 50% CAGR in the coming years. It provides a new path for beer premiumization amid competition over existing market share, and the industry should focus on off-premise scenarios and emotional consumption.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

在啤酒行业整体步入存量博弈的当下,寻找新的增长极成为所有啤酒企业的必答题。华润啤酒(0291.HK)给出的解法是:将高端化战略与即时零售渠道深度融合,在“到家”场景中开辟出第二增长曲线。

财报显示,华润啤酒今年上半年实现营业额为人民币242.4亿元,同比增长1.2%;啤酒销量约660万千升,同比增长1.7%。在财报利好与增长态势之下,结构优化的信号更为明显。高端化与即时零售两条增长线正在发生深度交汇,成为驱动业绩增长的关键变量。

场景重构:从“商务宴请”到“居家微醺”,即时零售承接高端化消费红利

财报显示,今年上半年,华润啤酒次高及以上啤酒销量同比增幅超10%,普高档及以上啤酒销量增长约15%。喜力销量增长超20%,老雪、红爵销量增速分别超40%和80%。

行业分析认为,支撑华润啤酒高端化提速的,是啤酒消费场景的结构性迁移。太平洋证券研报指出,传统商务佐餐、多人宴席场景持续收缩,2-4人小型餐饮场景占比已升至58%,饮酒动机从社交应酬转向情绪自愈、独饮小聚、居家、户外、深夜微醺等非现饮场景。而这一变化与即时零售消费场景天然契合。数据显示,啤酒品类在21:00-23:00时段的订单占比高达45.7%;精酿、果啤等新兴品类,在即时零售渠道的客单价较传统渠道高出约30%。对啤酒行业而言,即时零售逐渐成为承载高端酒饮消费的核心渠道。

淘宝闪购侧的最新经营数据也印证了这一趋势。当前淘宝闪购啤酒行业快速增长,上半年淘宝闪购啤酒品类日均销售额大幅增长,消费用户数较去年进一步攀升。数据显示,一线和新一线城市贡献了近半订单;25-40岁人群占据主流消费,高客单消费占比超过五成。淘宝闪购用户群体具备年轻化、高购买力特征,与华润啤酒高端化战略方向高度契合。

华润啤酒与淘宝闪购形成强强联合的协同效应。今年上半年,华润啤酒在淘宝闪购跑出超160%的同比增速。以淘宝闪购为代表的即时零售平台,正在成为承接啤酒消费新场景、释放高端化增长潜力的核心阵地,为啤酒行业打开了从规模增长到价值增长的新空间。

营销升维:以“情绪”为锚点,打造“橙就时刻”全域消费闭环

淘宝闪购与华润啤酒围绕场景营销、用户运营、生态联动等多领域展开协作,在新营销与全域触达层面的深度协同。通过借助OAIPL全链路运营模式,淘宝闪购将观赛、聚会、独酌等消费时刻转化为华润啤酒可运营的营销场景,构建起从流量触达到用户沉淀的完整闭环。

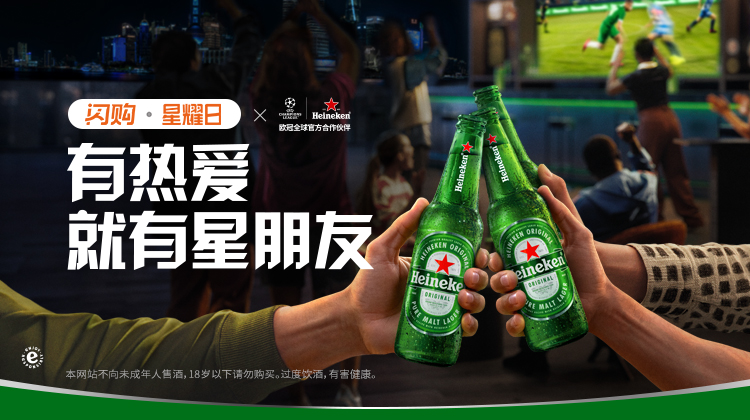
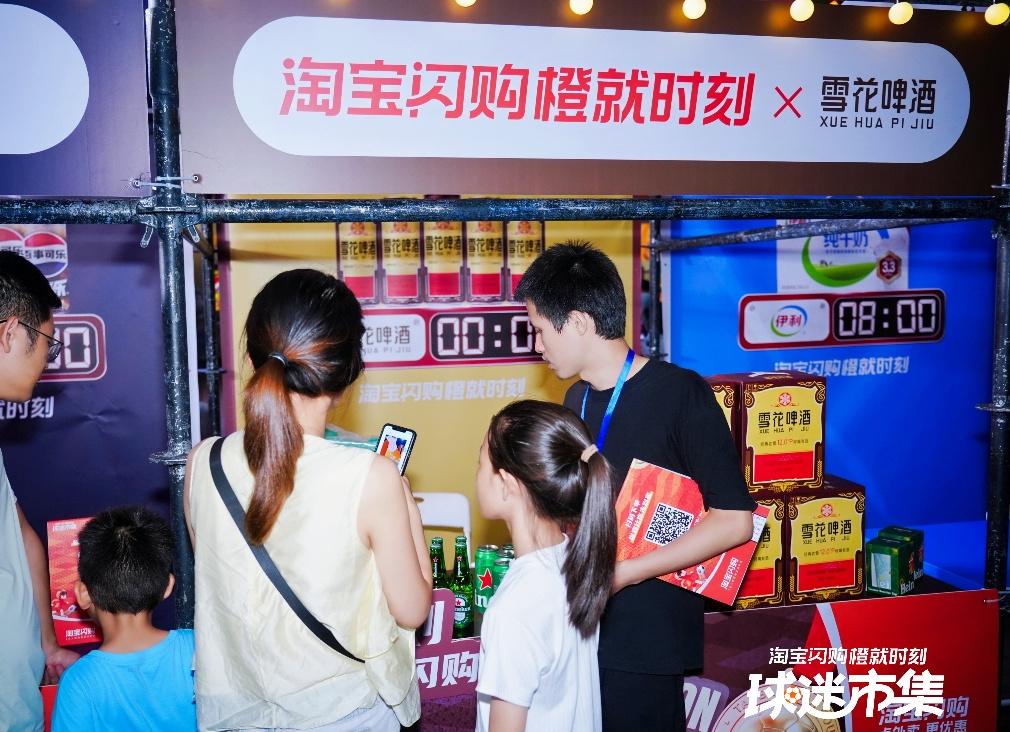
今年5月,淘宝闪购联合喜力打造欧冠主题“星耀日”活动,将观赛场景与啤酒消费结合,项目周期内喜力品牌GMV同比增长200%,小红书站外种草曝光超22万。进入7月世界杯周期,雪花深度参与“橙就时刻”赛事营销,线下在重庆地铁走廊和深圳球迷市集铺设品牌触点,线上联动平台核心流量资源,项目周期内品牌GMV同比增长64%,全域曝光超4.6亿次。8月,双方围绕“冰杯+啤酒”联合体验营销切入夏季夜间高频场景,项目周期内品牌AIPL人群资产环比增长近14%,广东市场GMV同比增长127%。华润啤酒旗下多个啤酒品牌在淘宝闪购销量持续攀升。

这套营销体系的底层逻辑,是淘宝闪购以“消费情绪”为核心的数字化运营能力。平台通过OAIPL全链路运营,将微醺、聚会等消费时刻转化为即时购买;并依托阿里生态,在高德地图、飞猪旅行、优酷等业务的出行导航、酒店住宿、观影观赛等触点导入全域流量。与传统电商以品类或品牌为主的货架逻辑不同,这套“消费情绪为先”的分发方式,更契合啤酒品类高频、即时、场景强关联的消费特征,把场景红利转化为实实在在的商业增量。

行业层面,酒类即时零售仍处于快速扩张期。公开数据显示,2025年国内酒类即时零售市场规模已突破500亿元,行业机构预计未来数年将保持约50%的复合增速。当“到家”从传统的补充渠道演变为独立的消费场景,即时零售正在成为啤酒企业应对存量竞争、重塑增长第二曲线的关键抓手。

注:文/龚作仁,文章来源:Laborer,本文为作者独立观点,不代表亿邦动力立场。

文章来源:Laborer

广告
微信
朋友圈

FAQ回顾

华润啤酒在即时零售渠道表现如何?

2026年上半年,华润啤酒在淘宝闪购渠道销售额同比增长超160%,整体营业额242.4亿元,同比增长1.2%。其高端化战略通过与即时零售渠道深度融合实现加速,次高及以上啤酒销量同比增长超10%,喜力销量增长超20%,成为存量博弈下华润啤酒的第二增长曲线。

即时零售对啤酒行业高端化有什么影响?

即时零售正成为承接啤酒高端化消费红利的核心渠道。啤酒消费从商务宴请转向居家微醺、户外、深夜等非现饮场景,精酿、果啤等新兴品类在即时零售渠道的客单价较传统渠道高出约30%。华润啤酒将高端化战略与即时零售深度融合,在淘宝闪购跑出超160%的同比增速。

啤酒消费场景发生了哪些变化?

传统商务佐餐、多人宴席场景持续收缩,2-4人小型餐饮场景占比已升至58%,饮酒动机从社交应酬转向情绪自愈、独饮小聚、居家、户外、深夜微醺等非现饮场景。啤酒品类在21:00-23:00时段的订单占比高达45.7%,消费呈现场景化、情绪化特征。

淘宝闪购啤酒品类消费有哪些特点?

上半年淘宝闪购啤酒品类日均销售额大幅增长,消费用户数较去年进一步攀升。一线和新一线城市贡献近半订单,25-40岁人群占据主流消费,高客单消费占比超过五成,用户群体呈现年轻化、高购买力特征,与啤酒高端化方向高度契合。

酒类即时零售市场规模有多大?

2025年国内酒类即时零售市场规模已突破500亿元,行业机构预计未来数年将保持约50%的复合增速。即时零售正从传统补充渠道演变为独立消费场景,成为啤酒企业应对存量竞争、重塑增长第二曲线的关键抓手。

这么好看,分享一下?

朋友圈 分享

APP内打开

赞 +1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0