广告
加载中

IDC 报告显示:上半年智元出货规模与营收断层领先

龚作仁 2026-09-30 12:15
龚作仁 2026/09/30 12:15

邦小白快读

EN
全文速览

总:本文最值得普通读者记住的是,人形机器人已从概念展示进入真实工作岗位,判断产业成熟度要看三件事:出货量、部署场景和每日实际工作时长。

1. 看数据:2026上半年全球人形机器人出货约2.5万台,同比增长432.1%;中国出货超1.9万台,占全球77.9%。智元出货超8600台,占全球35%、中国45%,是出货量与营收双第一。

2. 看变化:行业竞争重点已从机器人外形、硬件参数和运动性能,转向对物理世界的理解、任务规划、操作执行和持续学习,机器人是否“聪明好用”比“能走会跳”更重要。

3. 看案例:智元在长隆部署超300台机器人,覆盖文娱商演、科普研学、导览导购、零售服务、智能伴游、酒店、体育等七大场景,每日运营8小时;在爱仕达门店部署100台机器人做导购,每日在岗超10小时。

4. 看趋势:IDC预测2030年全球出货量将突破75万台,人形机器人会进入更多工业、商业服务和消费市场。

总:人形机器人品牌商真正的竞争已经不在发布会参数,而在能否像智元一样用全栈自研技术底座实现大规模出货和真实场景部署。

1. 品牌建设:智元以“三智一体”作为技术品牌,用长隆、爱仕达等标杆项目证明产品能上岗,品牌故事由落地案例而不是概念支撑。

2. 渠道与终端体验:门店部署100台灵犀X2做“硅基导购员”,覆盖货架、收银台和体验区,说明半尺寸人形机器人更适合线下零售空间,品牌商可用它做主动迎宾、商品科普和带路,形成人机协作的门店服务闭环。

3. 产品研发:智元拥有远征、灵犀、精灵、酷拓四类产品,提示品牌商按场景定义产品形态,全尺寸、半尺寸、轮式、四足各有分工。

4. 消费趋势:连续三天直播中机器人主动接待并参与卖货,反映消费者对科技感互动服务的接受度上升;零售工具包的出现,意味着品牌商可以把服务流程标准化并复制到更多门店。

总:本文对卖家最有用的干货是:人形机器人正在成为门店和直播里的新生产力,零售场景已有可复制的工具包,值得关注新的服务和变现机会。

1. 市场机会:2026上半年中国人形机器人出货超1.9万台,占全球77.9%;IDC预测2030年全球出货超75万台,若卖家所在行业涉及机器人租赁、体验式零售或直播内容,增长空间明显。

2. 需求变化:消费者已能在门店接受机器人主动迎宾、商品科普、带路等服务;直播中机器人也能成为吸引观看和互动的内容点,说明“人机协作卖货”是一种可落地的零售表达。

3. 可学习做法:爱仕达用100台机器人在门店做导购,每日在岗超10小时,并连续三天直播;智元沉淀了零售场景工具包,卖家可参考其把迎宾、导购、直播串联成标准流程。

4. 风险和切入建议:大规模部署机器人前期投入高,适合品牌连锁先跑样板;中小卖家可从单店或少数量机器人试水,围绕活动营销和直播内容验证客流带动效果,再决定是否扩大。

总:工厂能从中看到的干货有两层:一是人形机器人本体制造带来新的生产订单,二是工厂引入机器人要从真实岗位出发,而不是买来当展品。

1. 制造与供应链机会:中国人形机器人出货量上半年超1.9万台,智元出货超8600台并强调规模化量产交付能力,这意味着结构件、电机、传感器、整机代工等上游生产需求正在放量。

2. 产品设计需求:智元用全尺寸、半尺寸、轮式、四足四种产品覆盖不同场景,提示工厂若介入机器人相关制造,应按客户实际空间、作业内容和运营时长来设计和配套,不能只卷外观。

3. 数字化与电商启示:智元在爱仕达门店让机器人在岗超10小时,并参与三天直播,工厂可以用类似方式做工厂展厅、生产线直播,把机器人员工变成数字化营销触点。

4. 部署评估:文章强调从产线走向真实岗位,工厂评估机器人时应看它是否能进入实际流程、每日稳定运转并创造价值,而非停留在演示。

总:对服务商来说,文章最核心的信号是客户需要的是能持续上岗的“部署态”机器人,而不是一台硬件;围绕长时运行、场景适配和效果运营会产生大量服务需求。

1. 技术趋势:人形机器人正结合大模型、世界模型、VLA和数据闭环,竞争焦点转向理解物理世界、任务规划、操作执行和持续学习,服务商可在算法调优、数据采集、场景训练等环节提供专业能力。

2. 客户痛点:长隆文旅场景有高客流和强干扰,要求每日8小时持续运营;爱仕达零售场景要求每日超10小时在岗。客户核心痛点是如何保证机器人稳定、不出错、可维护。

3. 解决方案:智元用“三智一体”作为技术底座,并在零售项目中沉淀工具包;服务商可把特定场景的服务流程做成标准化工具包,提供部署、培训、直播运营、远程运维等一站式服务。

4. 商业机会:从主题乐园上百个交互点到门店导购,服务内容已超出卖设备,包含场景策划、内容更新、人机协作流程设计和数据分析,服务商可转向长期运营服务模式。

总:平台商从这篇文章中可以看到,人形机器人正在形成新的商业供给:它既可以是门店服务载体,也可以是直播内容载体;平台应围绕场景工具包、数据闭环和运营规则来搭台。

1. 平台需求:商户需要快速把机器人用起来,而不是自行摸索部署;平台商可整合机器人硬件、场景方案、直播运营和数据监测,提供类似“机器人即服务”的撮合与管理系统。

2. 最新做法:智元和爱仕达用100台机器人组成门店导购团队,并沉淀零售场景工具包;平台可借鉴这种“工具包+门店+直播”的组合,向连锁商家输出标准模板。

3. 招商与运营:长隆乐园这类大型客户一次部署超300台、上百个交互点位,平台商可围绕主题乐园、商业街区和连锁零售招募机器人方案服务商,以项目制方式撮合。

4. 风险规避:行业正从硬件参数竞赛转向具身智能综合能力竞争,平台招商时不能只看运动性能,还要考察机器人的任务规划、场景理解、持续学习和现场服务能力,并用长时运行、高客流干扰等标准验收。

总:文章提供了人形机器人产业进入商业化关键期的实证:市场高速增长、竞争范式转变、商业化模式出现,值得研究者从技术、产业、治理三个层面继续观察。

1. 产业数据:2026上半年全球出货约2.5万台,同比增长432.1%,中国占全球77.9%;智元出货超8600台,全球占比35%、中国占比45%,是首个进入大规模出货与商业化落地阶段的厂商。

2. 技术范式:竞争重点从硬件结构、运动性能转向具身智能综合能力,大模型、世界模型、VLA和数据闭环共同塑造新研究方向,机器人“学习和适应环境”能力比本体硬件更关键。

3. 商业模式:智元以“三智一体”支撑文旅、零售等部署态项目,并通过零售场景工具包形成可复制方案,说明具身智能商业模式正从卖设备转向卖岗位化服务和场景运营。

4. 政策与治理议题:大规模机器人在高客流开放场所长期运营,会带来人机安全、隐私保护、服务标准、数据治理和责任划分等新问题;研究者可结合长隆和爱仕达案例,提出岗位替代评估、机器人上岗规范和数据闭环治理建议。IDC预测2030年出货突破75万台,治理规则需提前布局。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

Overall: The most important takeaway for general readers is that humanoid robots have moved from concept showcases to real jobs. To assess industry maturity, look at three indicators: shipment volumes, deployment scenarios, and actual daily working hours.

1. Shipment data: In the first half of 2026, global humanoid robot shipments reached approximately 25,000 units, up 432.1% year-over-year; China shipped more than 19,000 units, accounting for 77.9% of the global total. Zhiyuan shipped over 8,600 units, representing 35% of the global market and 45% of China's market, making it No.1 in both shipments and revenue.

2. Shifting priorities: The competitive focus has moved from robot appearance, hardware specs, and motion capabilities to understanding the physical world, task planning, manipulation execution, and continuous learning. Whether a robot is "smart and useful" now matters more than whether it can walk or jump.

3. Real-world deployments: Zhiyuan deployed more than 300 robots at Chimelong, covering seven scenarios including entertainment and commercial performances, science education tours, guided navigation and shopping, retail services, intelligent companionship, hotels, and sports, operating eight hours per day. At Aishida store, 100 robots were deployed as shopping guides, each on duty for over 10 hours per day.

4. Outlook: IDC forecasts global shipments will exceed 750,000 units by 2030, as humanoid robots enter more industrial, commercial-service, and consumer markets.

Overall: For humanoid robot brands, the real competition is no longer at the spec-sheet launch event; it lies in whether you can build a full-stack self-developed technology foundation and achieve large-scale shipment and real-world deployment the way Zhiyuan has.

1. Brand building: Zhiyuan uses its "Three Intelligences in One" architecture as a technology brand, validating its products in landmark projects such as Chimelong and Aishida. The brand story is supported by deployed cases, not concepts.

2. Channels and in-store experience: Deploying 100 Lingxi X2 robots as "silicon-based shopping guides" across shelves, checkout counters, and experience zones shows that half-sized humanoid robots are better suited for physical retail space. Brands can use them to proactively greet customers, explain products, and guide them through the store, forming a human-machine collaborative service loop.

3. Product R&D: Zhiyuan offers four product lines---Yuanzheng, Lingxi, Jingling, and Kuto---which suggests that brands should define product forms by scenario: full-sized, half-sized, wheeled, and quadruped robots each serve different roles.

4. Consumer trends: Over three consecutive days of livestreaming, the robots proactively engaged with customers and participated in selling, reflecting rising consumer acceptance of tech-enabled interactive service. The emergence of a retail toolkit means brands can standardize service workflows and replicate them across more stores.

Overall: The most useful insight for sellers is that humanoid robots are becoming a new productivity tool in stores and livestreams. The retail scenario already has replicable toolkits, creating fresh service and monetization opportunities worth watching.

1. Market opportunity: In the first half of 2026, China shipped more than 19,000 humanoid robots, accounting for 77.9% of global shipments; IDC predicts global shipments will exceed 750,000 by 2030. If your business touches robot rental, experiential retail, or livestream content, the growth upside is clear.

2. Demand shift: Consumers are already accepting proactive greeting, product explanation, and wayfinding from robots in stores. Robots can also become a content anchor in livestreams to attract viewers and drive interaction, proving that "human-machine collaborative selling" is a workable retail expression.

3. Practices to adopt: Aishida deployed 100 robots in store as shopping guides, each on duty for over 10 hours daily, and ran livestreams for three consecutive days. Zhiyuan has distilled a retail-scenario toolkit, which sellers can adapt to connect greeting, guidance, and livestreaming into a standardized process.

4. Risks and entry points: Large-scale robot deployment requires significant upfront investment, so it suits branded chains looking to pilot a model first. Smaller sellers can start with a single store or a few robots, testing traffic-driving effects via event marketing and livestream content before deciding whether to scale up.

Overall: For factories, this article offers two takeaways: first, humanoid robot manufacturing itself creates new production orders; second, when factories introduce robots, they should start from real job requirements rather than buying machines as showpieces.

1. Manufacturing and supply-chain opportunity: China shipped more than 19,000 humanoid robots in the first half of the year, with Zhiyuan shipping over 8,600 and emphasizing mass-production delivery capability. This indicates growing demand for structural parts, motors, sensors, and complete-machine OEM services upstream.

2. Product design needs: Zhiyuan uses four product types---full-size, half-size, wheeled, and quadruped---to cover different scenarios. This suggests factories involved in robot-related manufacturing should design and configure around the customer's actual space, task content, and operating hours, rather than competing on appearance alone.

3. Digital and e-commerce implications: Zhiyuan kept robots on duty for over 10 hours per day at Aishida and participated in three days of livestreaming. Factories can apply similar approaches to factory showrooms and production-line livestreams, turning robot employees into digital marketing touchpoints.

4. Deployment evaluation: The article emphasizes moving from production line to real job positions. When evaluating a robot, factories should assess whether it can enter the actual workflow, operate reliably every day, and create value, rather than remaining a demonstration.

Overall: For service providers, the core message is that customers need "deployment-ready" robots that can stay on the job continuously, not just a piece of hardware. This generates extensive service demand around long-duration operation, scenario adaptation, and outcome-based operation.

1. Technology trend: Humanoid robots are integrating large models, world models, VLA, and data loops. The competitive focus has shifted to understanding the physical world, task planning, manipulation execution, and continuous learning, giving service providers opportunities to offer expertise in algorithm tuning, data collection, and scenario training.

2. Customer pain points: Chimelong's cultural tourism scenarios involve high footfall and strong interference, requiring eight hours of continuous daily operation; Aishida's retail scenario demands more than ten hours of on-duty time per day. The core pain point is ensuring stable, error-free, maintainable robot performance.

3. Solution approach: Zhiyuan uses its "Three Intelligences in One" technology foundation and has distilled a toolkit from its retail projects. Service providers can turn specific scenario workflows into standardized toolkits and provide one-stop services spanning deployment, training, livestream operation, and remote maintenance.

4. Business opportunity: From hundreds of interactive points in theme parks to storefront shopping guides, the service scope has moved beyond selling equipment to scenario planning, content updates, human-robot collaboration workflow design, and data analytics. Service providers can pivot to a long-term operational service model.

Overall: For marketplace operators, this article shows that humanoid robots are forming a new commercial supply: they can serve as in-store service carriers and as livestream content carriers. Platforms should build their infrastructure around scenario toolkits, data loops, and operating rules.

1. Platform demand: Merchants need to put robots into use quickly, without figuring out deployment on their own. Marketplace operators can integrate robot hardware, scenario solutions, livestream operations, and data monitoring, offering a "Robot-as-a-Service" matching and management system.

2. Latest practice: Zhiyuan and Aishida built a store shopping-guide team with 100 robots and distilled a retail-scenario toolkit. Platforms can adopt this combination of "toolkit + store + livestream" and export standard templates to chain merchants.

3. Recruitment and operations: A large customer like Chimelong deployed over 300 robots and hundreds of interactive points in one go. Platforms can recruit robot solution providers around theme parks, commercial streets, and chain retail, and match them through a project-based model.

4. Risk mitigation: The industry is moving from a hardware-specs race to a competition in embodied-AI comprehensive capabilities. Platforms should not only look at motion performance when recruiting vendors but also assess task planning, scene understanding, continuous learning, and on-site service ability, and accept projects based on criteria such as long-duration operation and high-footfall interference.

Overall: This article provides empirical evidence that the humanoid robot industry has entered a critical phase of commercialization: rapid market growth, a paradigm shift in competition, and the emergence of business models. Researchers should continue to observe from technological, industrial, and governance perspectives.

1. Industry data: Global shipments in the first half of 2026 were about 25,000 units, up 432.1% year-over-year, with China accounting for 77.9%. Zhiyuan shipped over 8,600 units, representing 35% globally and 45% in China, making it the first company to reach large-scale shipment and commercial deployment.

2. Technology paradigm: The competitive focus has shifted from hardware structure and motion performance to comprehensive embodied-AI capabilities. Large models, world models, VLA, and data loops together shape new research directions. A robot's ability to "learn and adapt to its environment" is now more critical than the physical body itself.

3. Business model: Zhiyuan uses its "Three Intelligences in One" foundation to support deployment-oriented projects in cultural tourism and retail, and forms replicable solutions through retail-scenario toolkits. This indicates that the embodied-AI business model is moving from selling devices to selling job-ready services and scenario operations.

4. Policy and governance issues: Large-scale robots operating long-term in open spaces with high footfall raise new questions around human-robot safety, privacy protection, service standards, data governance, and liability allocation. Researchers can use the Chimelong and Aishida cases to propose impact assessments for job replacement, standards for robot deployment, and governance recommendations for data loops. Given IDC's forecast of over 750,000 shipments by 2030, governance rules need to be prepared in advance.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

国际知名数据公司IDC最新发布的报告显示,全球人形机器人市场延续爆发式增长,2026上半年全球人形机器人出货量接近2.5万台,同比增长432.1%,产业正由技术验证加速迈向商业化应用落地阶段。其中,中国人形机器人市场保持快速增长,出货量超1.9万台,占全球市场比重约77.9%。值得关注的是,作为全球具身智能赛道的头部厂商,中国的智元(AGIBOT)出货量超8600台,在全球排名中实现断层式领先,并且依托全栈自研的“三智一体”技术框架、规模化量产交付能力,正持续落地工厂、文旅、零售等标杆项目,印证了中国厂商在本体制造、大模型、具身智能综合能力与真实场景商业化的领先实力。

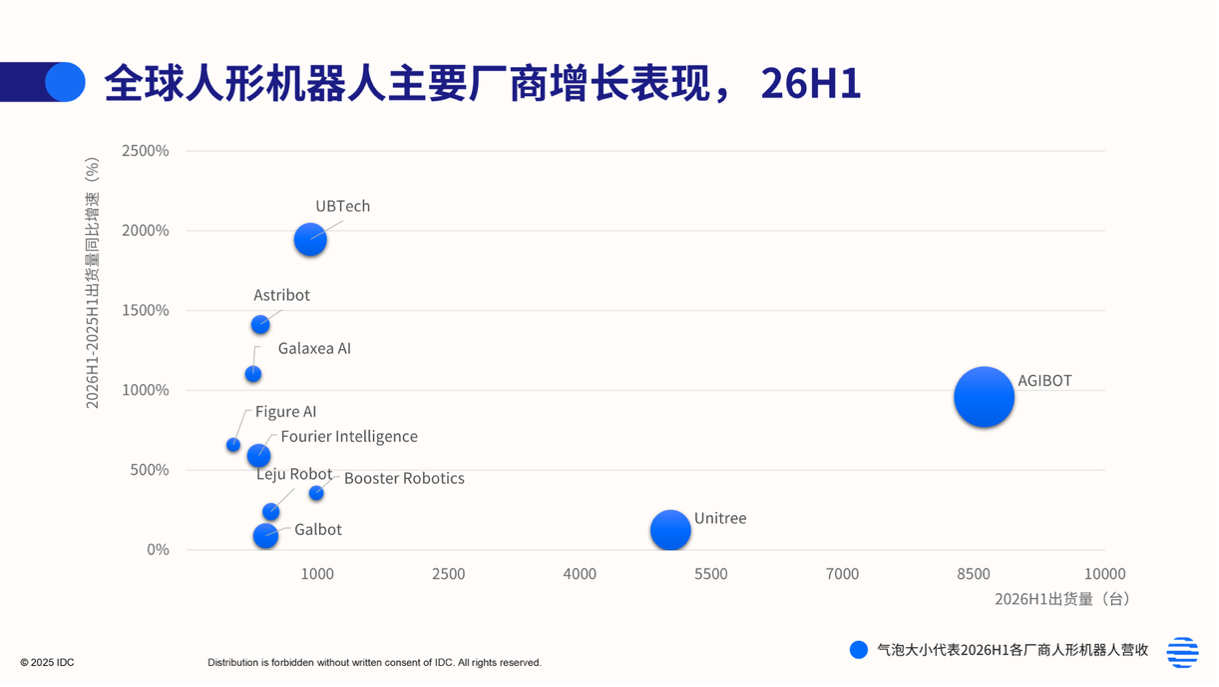
出货规模与营收断层领先,智元引领全球人形机器人发展

IDC 2026上半年人形机器人厂商气泡图直观显示: 智元(AGIBOT)位居全图最右侧,以断层领先的出货规模与最大营收体量,成为全球人形机器人量产交付与商业化营收的双料第一。智元上半年出货量超8600台,占全球市场35%和中国市场45%以上,并且在高基数下保持十倍级增长,率先完成从量产出货向多行业部署态落地。不同于其他厂商高增速、小基数的态势,智元凭借双龙头地位,是全球唯一进入 “大规模出货 + 商业化落地” 阶段的厂商。

行业竞争转向具身智能综合能力,“部署态”加速应用场景落地

IDC报告同时指出,人形机器人正在进入从“硬件能力竞争”向“具身智能综合能力竞争”转变的关键阶段。随着大模型、世界模型、视觉语言动作模型(VLA)以及机器人数据闭环快速发展,行业竞争重点正从机器人结构设计、硬件参数和运动性能,转向机器人对物理世界的理解、任务规划、操作执行和持续学习等综合能力。

人形机器人正进一步从技术验证迈向商业化应用落地,智元以“三智一体”(运动智能 + 交互智能 + 作业智能+可靠本体)作为核心技术底座,持续拓展各类应用场景的“部署态”落地。

在文旅赛道,智元携手长隆打造全球首个大规模具身智能主题乐园。9月24日起,超300台智元机器人在横琴长隆飞船乐园百余个交互点位常态化上岗,覆盖文娱商演、科普研学、导览导购导引、服务零售站、智能伴游、酒店场景、体育竞技等七大核心场景的“部署态”服务,在高客流、强干扰的开放文旅环境中每日8小时持续运营,实现大规模人形机器人文旅部署态落地,证明全尺寸人形机器人可以作为生产力角色深度融入乐园日常运营。

在零售商业赛道,智元部署100台机器人在爱仕达门店担任“硅基导购员”,灵犀X2每日超10小时在岗,依托半尺寸人形的灵活机身,适配货架、收银台、货品体验区。从9月28-30日持续三天的直播中,可以看到机器人主动迎宾接待、商品科普、门店带路等,形成完整人机协作服务闭环。该项目沉淀下来的零售场景工具包,可为人形机器人走进线下实体零售提供可复制样板。

布局产业长期未来,持续拓展人形机器人商业边界

IDC预测,2030年全球人形机器人出货量将突破75万台,市场进入规模化应用加速期,工业、商业服务、消费市场将形成多元驱动格局。智元拥有远征全尺寸人形、灵犀半尺寸人形、精灵轮式作业、酷拓四足机器人完整产品矩阵,可覆盖全场景进行“部署态”商业落地。

规模出货只是起点,把机器真正用起来,持续创造商业价值,才是具身智能产业的核心命题。智元将持续推进更多机器人从产线走向真实岗位,不断拓展工业、商业服务等多元场景边界,为全球具身智能产业的规模化发展贡献中国力量。

注:文/龚作仁,文章来源:Laborer,本文为作者独立观点,不代表亿邦动力立场。

文章来源:Laborer

广告
微信
朋友圈

FAQ回顾

2026年上半年全球人形机器人市场有什么新变化?

2026上半年全球人形机器人出货量接近2.5万台,同比增长432.1%;中国人形机器人出货量超1.9万台,占全球约77.9%。行业竞争正从硬件参数转向具身智能综合能力,产业由技术验证加速迈向商业化应用落地阶段。

智元是一家什么样的公司?主要产品和市场地位如何?

智元是全球具身智能赛道头部厂商,拥有远征全尺寸人形、灵犀半尺寸人形、精灵轮式作业、酷拓四足机器人完整产品矩阵。2026上半年出货量超8600台,占全球市场35%、中国市场45%以上,营收规模全球第一,是唯一进入“大规模出货+商业化落地”阶段的厂商。

人形机器人目前有哪些实际应用场景?

目前典型应用集中在文旅和零售。文旅方面,智元与长隆合作,在横琴长隆飞船乐园部署超300台机器人,覆盖文娱商演、科普研学、导览导购、智能伴游、酒店服务等七大场景,每日运营8小时;零售方面,在爱仕达门店部署100台机器人担任“硅基导购员”,灵犀X2每日在岗超10小时。

人形机器人行业的竞争焦点发生了哪些变化?

行业正从“硬件能力竞争”转向“具身智能综合能力竞争”,竞争重点不再只是结构设计、硬件参数和运动性能,而是机器人对物理世界的理解、任务规划、操作执行和持续学习等综合能力。大模型、世界模型、VLA以及机器人数据闭环是推动转变的关键技术方向。

IDC对2030年人形机器人市场有什么预测?

IDC预测,2030年全球人形机器人出货量将突破75万台,市场进入规模化应用加速期,工业、商业服务、消费市场将形成多元驱动格局。

这么好看,分享一下?

朋友圈 分享

APP内打开

赞 +1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0