广告
加载中

重磅:亿邦智库 × Pattern栢藤联合发布《智赢·共生—品牌全球化加速增长洞察报告》

亿邦智库 2026-09-17 18:16
亿邦智库 2026/09/17 18:16

邦小白快读

EN
全文速览

这份亿邦智库联合Pattern栢藤发布的品牌全球化增长报告,梳理了当前跨境电商发展的核心趋势、常见经营误区和可落地的增长方法,包含不少实用信息。

1. 核心行业基本面方面,2026-2028年全球零售电商销售额将从6.8万亿美元增长至近8万亿美元,保持7%左右的年增速;生成式AI正在改变大众购物路径,2026年一季度美国生成式AI驱动的线上购物流量同比增长393%,引荐转化率比传统渠道高42%,同时全球各区域的合规要求正在持续趋严。

2. 实用经营认知方面,当前靠低价铺货的跨境经营模式压力越来越大,具备产品研发、品牌溢价、敏捷供应链能力的经营主体更有竞争力,全球73%的消费者会跨渠道购物,单纯依赖单一平台很难沉淀长期用户价值。

3. 落地思路参考方面,参与跨境经营不必硬扛自建团队、备货囤货的高成本,要警惕长供应链带来的库存积压风险,可选择能共担风险、整合全链路资源的合作方降低试错成本,目前已有6个国内外品牌通过这类合作实现了品类登顶、收入翻倍的增长结果。

报告明确了当前品牌全球化的核心趋势、经营卡点与体系化增长路径,为品牌开展全球布局提供了清晰的决策参考。

1. 趋势研判层面,全球电商保持7%的年增速,美欧成熟市场是基本盘,亚太、拉美、中东等新兴市场持续释放潜力;73%的消费者习惯跨渠道购物,决策时更看重产品质量、高效履约与个性化服务;流量入口从传统搜索向AI生成式场景转移,品牌流量运营需从传统SEO向GEO(生成式引擎优化)拓展,同时要将税务、环保、数据合规要求前置到选品、上架等全经营环节。

2. 风险提示层面,自建直营团队需承担人力、备货、物流、仓储等多重成本,其中物流仓储成本占比15%-20%、营销成本占10%-15%,资金周转压力大;多头对接不同区域的各类服务商容易导致数据不协同、响应效率低,61.2%的品牌面临库存积压的潜在风险。

3. 落地路径层面,品牌可聚焦产品研发、供应链建设与品牌资产沉淀,搭建覆盖第三方平台、独立站、社交电商、实体零售的全渠道矩阵,选择风险共担的全链路增长伙伴协同运营,借助AI工具提升运营和广告效率,参考报告中芭克、博世、SPANX等品牌的实践经验搭建增长体系。

报告梳理了当前跨境电商领域的政策支持方向、增量市场机会、经营风险提示与创新合作模式,为卖家经营决策提供参考。

1. 机会提示层面,跨境电商双循环政策持续完善,2026年一季度我国跨境电商进出口总额达6184.6亿元,出口规模达4735.5亿元;全球电商保持7%的年增速,美欧基本盘稳固,亚太、拉美、中东等新兴市场增量明显;行业红利持续向具备研发能力、产品溢价能力、敏捷供应链能力的经营主体集中,2025年亚马逊年销超百万美元的卖家已突破10万家,全渠道经营、消费体验升级是新的增长突破口。

2. 风险预警层面,单纯依赖低价供应链、铺货模式的卖家经营压力持续抬升,自建直营模式面临较高的人力、库存、物流成本压力;多头对接不同服务商容易推高管理成本、拉长决策链路,长供应链周期叠加多渠道库存割裂,使得61.2%的卖家面临库存积压风险。

3. 实操建议层面,卖家可选择采销一体、风险共担的全链路增长伙伴合作,降低前期投入与试错成本,借助AI运营、智能广告工具提升经营效率,参考已跑通的品牌案例优化自身经营动作,提升增长确定性。

报告披露的全球电商消费需求变化、渠道趋势与创新合作模式,为工厂对接跨境市场、推进数字化电商转型提供了明确方向。

1. 商业机会层面,全球电商规模将在2028年接近8万亿美元,当前纯低价铺货类商家竞争力持续下滑,消费者决策越来越看重产品质量、履约效率与个性化服务,具备产品研发能力、稳定生产能力、敏捷供应链响应能力的主体更易获得行业红利,工厂的制造端优势将迎来更大的价值释放空间。

2. 生产设计优化层面,工厂需要紧跟前端市场需求做产品创新和品质升级,配合多市场、多渠道的销售节奏调整生产和备货计划,打造柔性供应链能力,降低跨境长链路下的库存积压风险,匹配消费者不断升级的体验需求。

3. 转型路径层面,工厂不必从零搭建完整的跨境运营、营销、客服团队,可聚焦自身生产与产品研发的核心优势,通过与全链路增长伙伴合作的方式对接全球渠道网络,借助伙伴的本地化运营、合规服务、AI数据能力切入海外市场和国内进口渠道,降低转型的前期投入风险,参考博世借助合作18个月进入13个新市场、推出28款新品的路径快速打开市场。

报告清晰呈现了跨境电商行业的发展趋势、品牌客户的核心痛点,以及标杆服务主体的能力构建逻辑,为服务商迭代服务方案提供方向参考。

1. 行业趋势层面,全球电商已从规模扩张阶段转向长效经营阶段,AI正在重构电商流量入口,2026年一季度美国生成式AI驱动的购物流量同比增长393%,引荐转化率比传统渠道高42%,全球各市场的税务、环保、数据合规要求持续趋严,品牌与服务商的合作正从简单的交易型服务,转向价值共创、生态协同的长期伙伴关系。

2. 客户痛点层面,62.5%的品牌将本地化能力作为全球化经营的核心需求,但当前品牌多需要跨区域对接营销、支付、仓储、合规等多类服务商,存在经营目标不统一、数据不协同、管理成本高、市场响应慢的问题;自建直营的品牌普遍面临资金周转压力,61.2%的商家受库存积压风险困扰,客户需要的不是分散的单点服务,而是能统一目标、整合资源、共担风险的全链路支持。

3. 能力升级方向,服务商可探索建立风险共担的合作机制,沉淀数据资产与AI技术能力,搭建覆盖运营、广告投放、履约、合规的全链路服务体系,布局全球本地化服务网络,参考Pattern栢藤凭借海量数据积累、两大自研AI引擎、总经销合作模式打造可复制增长系统的路径,真正帮客户实现可持续增长。

报告梳理了当前跨境电商的渠道演化趋势、平台上商家的真实经营需求,为平台优化服务、开展招商、完善运营管理提供参考。

1. 渠道趋势层面,全球73%的消费者形成了跨渠道购物习惯,未来渠道生态将由第三方平台、独立站、社交电商、实体零售共同组成;AI正在改变消费者的购物入口逻辑,用户从主动搜索转向直接向生成式工具表达需求,品牌流量运营将从传统SEO向GEO拓展,平台需要适配AI时代的流量分发规则。

2. 商家需求层面,当前平台商家普遍面临营销成本、合规成本上升的压力,长供应链带来的库存积压风险、多服务商对接的协同效率低、跨市场本地化能力不足是普遍经营卡点,其中61.2%的商家担忧滞销积压风险,62.5%的商家将本地化能力作为核心经营诉求。

3. 运营与招商方向,平台可联动优质的全链路增长伙伴共同服务商家,为商家提供合规指引、AI运营工具、数据协同支持,降低商家跨区域经营的门槛;招商端重点引入具备产品研发能力、优质供应链的品牌商家,引导商家从低价铺货转向长效经营,同时完善跨渠道的履约、库存协同服务,帮助商家沉淀长期用户价值。

这份亿邦智库联合Pattern栢藤发布的品牌全球化增长报告,系统呈现了跨境电商产业的最新发展动向、现实经营难题与创新商业模式,具备重要的产业研究价值。

1. 产业新动向方面,全球电商已从规模扩张阶段进入长效经营阶段,2026-2028年将保持约7%的年增速,市场规模从6.8万亿美元向近8万亿美元迈进,增长动力从成熟市场向亚太、拉美、中东等新兴区域扩散;AI重构电商流量逻辑,2026年一季度美国生成式AI驱动的线上购物流量同比增长393%,转化率较传统渠道高42%,流量运营范式正从SEO向GEO迭代;政策端跨境电商双循环支持体系持续完善,2026年一季度我国跨境电商进出口额达6184.6亿元。

2. 产业新问题方面,当前品牌全球化经营面临三大普遍卡点:自建直营模式下资金成本高企、多服务商多头管理导致本地化成效被稀释、市场波动叠加长供应链周期推高库存积压风险,6成以上受访商家受上述问题困扰。

3. 商业模式创新方面,行业正在涌现以全链路增长伙伴为核心的共生模式,通过采销一体的风险共担机制、流量-转化-价格-供应的全链路增长指标拆解、AI驱动的智能运营体系、双向连通国内外市场的渠道网络,推动行业合作从交易信任转向系统信任,多个品牌案例已验证该模式的增长有效性,如合作品牌实现两年收入翻倍、一年广告销售额增长120%等成果。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

This brand globalization growth report, released by Ebrun Think Tank in partnership with Pattern, outlines core cross-border e-commerce trends, common operational pitfalls, and actionable growth strategies, packed with practical insights for industry participants.

1. On the industry fundamentals front: Global retail e-commerce sales are projected to grow from $6.8 trillion in 2026 to nearly $8 trillion by 2028, representing an annual growth rate of around 7%. Generative AI is reshaping consumer shopping journeys: in Q1 2026, generative AI-driven online shopping traffic in the U.S. surged 393% year over year, with referral conversion rates 42% higher than those of traditional channels. Meanwhile, regulatory requirements across all global regions continue to tighten.

2. On practical operational takeaways: The low-price, mass-listing cross-border business model is facing growing pressure, while players with product R&D capabilities, brand premium, and agile supply chains hold stronger competitive edges. 73% of global consumers shop across channels, making it difficult for businesses relying on a single platform to build long-term user value.

3. On actionable growth frameworks: Cross-border operators do not need to bear the high costs of building in-house teams and holding large inventory volumes, and should guard against inventory backlog risks caused by long supply chains. They can opt for partners that share risks and integrate end-to-end resources to reduce trial-and-error costs. To date, six domestic and international brands have leveraged such partnerships to become category leaders and double their revenue.

The report identifies core trends, operational bottlenecks, and systematic growth pathways for brand globalization, providing clear decision-making references for brands pursuing global expansion.

1. On trend assessment: The global e-commerce market is growing at an annual rate of 7%, with mature markets in North America and Europe serving as the core base, while emerging markets in Asia-Pacific, Latin America, and the Middle East continue to unlock growth potential. 73% of consumers are accustomed to cross-channel shopping, prioritizing product quality, efficient fulfillment, and personalized services in their purchase decisions. Traffic entry points are shifting from traditional search to generative AI scenarios, requiring brands to expand their traffic operation strategies from conventional SEO to GEO (Generative Engine Optimization). In parallel, tax, environmental, and data compliance requirements must be embedded in end-to-end operational processes from product selection to listing.

2. On risk alerts: Building in-house direct-to-consumer teams incurs stacked costs for labor, inventory, logistics, and warehousing, with logistics and warehousing accounting for 15%-20% of costs and marketing for 10%-15%, creating heavy working capital pressure. Coordinating with multiple service providers across different regions often leads to disconnected data and slow response times, with 61.2% of brands facing potential inventory backlog risks.

3. On implementation pathways: Brands can focus on product R&D, supply chain development, and brand equity building, constructing an omnichannel matrix covering third-party platforms, independent sites, social commerce, and brick-and-mortar retail. They can partner with risk-sharing end-to-end growth partners for collaborative operations, leverage AI tools to improve operational and advertising efficiency, and build their own growth systems by referencing successful practices from brands including ScarAway, Bosch, and SPANX featured in the report.

The report outlines policy support directions, incremental market opportunities, operational risk warnings, and innovative cooperation models in the cross-border e-commerce sector, providing references for sellers’ business decision-making.

1. On opportunity signals: Policies supporting the dual-circulation development of cross-border e-commerce continue to improve. In Q1 2026, China’s total cross-border e-commerce import and export volume reached 618.46 billion yuan, with exports hitting 473.55 billion yuan. The global e-commerce market maintains a 7% annual growth rate, with a stable core base in North America and Europe, and clear incremental growth in emerging markets across Asia-Pacific, Latin America, and the Middle East. Industry dividends are increasingly concentrated among players with R&D capabilities, product premium power, and agile supply chains; as of 2025, the number of Amazon sellers with annual sales exceeding $1 million surpassed 100,000. Omnichannel operation and upgraded consumer experiences are emerging as new growth breakthrough points.

2. On risk warnings: Sellers relying solely on low-price supply chains and mass-listing models face mounting operational pressure, while the in-house direct operation model carries high costs for labor, inventory, and logistics. Coordinating with multiple service providers tends to drive up management costs and lengthen decision-making chains; long supply chain cycles combined with siloed inventory across channels leave 61.2% of sellers exposed to inventory backlog risks.

3. On practical recommendations: Sellers can partner with end-to-end growth partners that integrate procurement and sales and share risks, to reduce upfront investment and trial-and-error costs. They can also leverage AI operation and smart advertising tools to improve operational efficiency, and optimize their business moves by referencing proven brand cases to boost growth certainty.

The report discloses shifts in global e-commerce consumer demand, channel trends, and innovative cooperation models, providing clear direction for factories seeking to access cross-border markets and advance digital e-commerce transformation.

1. On business opportunities: The global e-commerce market is projected to approach $8 trillion by 2028. Pure low-price, mass-listing merchants are seeing continuous declines in competitiveness, as consumers increasingly prioritize product quality, fulfillment efficiency, and personalized services in purchase decisions. Players with product R&D capabilities, stable production capacity, and agile supply chain responsiveness are better positioned to capture industry dividends, creating greater space for factories to unlock value from their manufacturing advantages.

2. On production and design optimization: Factories need to align product innovation and quality upgrades with front-end market demand, adjust production and inventory planning to match sales rhythms across multiple markets and channels, build flexible supply chain capabilities, reduce inventory backlog risks along long cross-border supply chains, and meet consumers’ rising experience expectations.

3. On transformation pathways: Factories do not need to build full in-house cross-border teams covering operations, marketing, and customer service from scratch. Instead, they can focus on their core strengths in production and product R&D, access global channel networks through partnerships with end-to-end growth partners, and leverage partners’ localized operation, compliance, and AI data capabilities to enter overseas markets and domestic import channels, reducing upfront investment risks in transformation. They can reference the path of Bosch, which entered 13 new markets and launched 28 new products within 18 months of partnership to rapidly expand market reach.

The report clearly presents development trends in the cross-border e-commerce industry, core pain points of brand clients, and the capability building logic of leading service providers, offering directional references for service providers to upgrade their solutions.

1. On industry trends: The global e-commerce sector has shifted from the scale expansion phase to long-term sustainable operation. AI is restructuring e-commerce traffic entry points: in Q1 2026, generative AI-driven shopping traffic in the U.S. rose 393% year over year, with referral conversion rates 42% higher than traditional channels. Tax, environmental, and data compliance requirements across global markets continue to tighten, and collaboration between brands and service providers is shifting from simple transactional services to long-term partnerships focused on value co-creation and ecosystem coordination.

2. On client pain points: 62.5% of brands identify localization capabilities as a core requirement for global operation. However, most brands currently need to coordinate with multiple service providers covering marketing, payment, warehousing, and compliance across regions, leading to misaligned operational goals, disconnected data, high management costs, and slow market response. Brands running in-house direct operations generally face working capital pressure, and 61.2% of merchants are troubled by inventory backlog risks. Clients do not need fragmented, single-point services, but end-to-end support that aligns objectives, integrates resources, and shares risks.

3. On capability upgrade directions: Service providers can explore establishing risk-sharing cooperation mechanisms, accumulating data assets and AI technology capabilities, building end-to-end service systems covering operations, advertising, fulfillment, and compliance, and laying out global localized service networks. They can reference Pattern’s approach, which leverages massive data accumulation, two self-developed AI engines, and an exclusive distribution cooperation model to build a replicable growth system, truly helping clients achieve sustainable growth.

The report sorts out cross-border e-commerce channel evolution trends and the real operational needs of merchants on platforms, providing references for platforms to optimize services, carry out merchant recruitment, and improve operation management.

1. On channel trends: 73% of global consumers have formed cross-channel shopping habits, and the future channel ecosystem will consist of third-party platforms, independent sites, social commerce, and brick-and-mortar retail. AI is changing the logic of consumer shopping entry points, as users shift from active search to directly expressing needs to generative tools. Brand traffic operation will expand from traditional SEO to GEO, requiring platforms to adapt to traffic distribution rules in the AI era.

2. On merchant needs: Merchants on platforms generally face rising marketing and compliance costs. Inventory backlog risks from long supply chains, low coordination efficiency from working with multiple service providers, and insufficient cross-market localization capabilities are common operational bottlenecks; 61.2% of merchants worry about unsold inventory backlog, and 62.5% see localization capabilities as a core operational demand.

3. On operation and recruitment directions: Platforms can collaborate with high-quality end-to-end growth partners to jointly serve merchants, providing compliance guidance, AI operation tools, and data collaboration support to lower the threshold for merchants to operate across regions. For merchant recruitment, platforms can prioritize onboarding brand merchants with product R&D capabilities and high-quality supply chains, guide merchants to shift from low-price mass-listing models to long-term operation, and improve cross-channel fulfillment and inventory coordination services to help merchants build long-term user value.

This brand globalization growth report, jointly released by Ebrun Think Tank and Pattern, systematically presents the latest development trends, real operational challenges, and innovative business models in the cross-border e-commerce industry, carrying significant industrial research value.

1. On new industry trends: The global e-commerce sector has moved from the scale expansion stage to a phase of long-term sustainable operation. It is projected to maintain an annual growth rate of around 7% from 2026 to 2028, with market size expanding from $6.8 trillion to nearly $8 trillion, as growth momentum spreads from mature markets to emerging regions including Asia-Pacific, Latin America, and the Middle East. AI is reconstructing e-commerce traffic logic: in Q1 2026, generative AI-driven online shopping traffic in the U.S. jumped 393% year over year, with conversion rates 42% higher than traditional channels, and the traffic operation paradigm is evolving from SEO to GEO. On the policy front, the dual-circulation support system for cross-border e-commerce continues to improve, with China’s cross-border e-commerce import and export volume reaching 618.46 billion yuan in Q1 2026.

2. On new industry challenges: Brand globalization currently faces three widespread bottlenecks: high capital costs under the in-house direct operation model, diluted localization outcomes caused by fragmented management of multiple service providers, and elevated inventory backlog risks driven by market volatility and long supply chain cycles, with over 60% of surveyed merchants affected by these issues.

3. On business model innovation: A symbiotic model centered on end-to-end growth partners is emerging in the industry. Through risk-sharing mechanisms integrating procurement and sales, decomposed end-to-end growth metrics covering traffic, conversion, pricing, and supply, AI-driven intelligent operation systems, and channel networks connecting domestic and international markets bidirectionally, the model is driving industry cooperation from transaction-based trust to system-based trust. Multiple brand cases have verified the model’s growth effectiveness, including partner brands achieving doubled revenue within two years and a 120% increase in ad-driven sales within one year.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

【亿邦原创】当AI重塑消费者的发现与决策路径,平台规则与合规要求日趋复杂,不同区域市场的增长节奏与竞争形态也在加速分化。从成熟市场到新兴区域,全球化探索持续深入,增长的稳定性、效率与可持续性,正成为品牌共同面对的新命题。

为寻找答案,品牌方、创始人、CEO及服务商都在追问同一个核心问题:当商品供给持续增加、销量增长却未能同步,如何通过更精准的营销、更高效的运营和更深入的本地化服务及落地资源,获得更多市场份额?

2026年9月17日,由Pattern栢藤创办的Accelerate 26跨境生态加速大会首次落地中国深圳。这场北美电商领域的年度盛会,旨在将栢藤在北美积累的头部平台方、服务商与品牌决策者资源,与本土最具出海实力的品牌创始人和高管直接链接,助力中国品牌加速全球化布局。

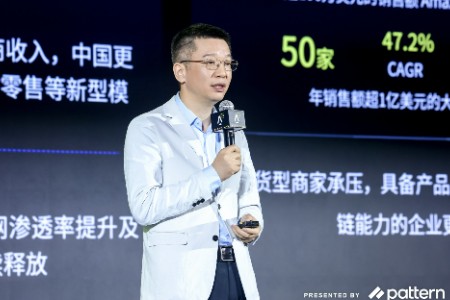
会上,亿邦智库与Pattern栢藤联合发布《智赢·共生—品牌全球化加速增长洞察报告》(以下简称《报告》),亿邦动力董事长、亿邦智库院长郑敏进行现场解读,重点回答三个关键问题:全球增长机会在哪里?品牌需要建立怎样的经营体系?什么样的合作模式能够将市场机会持续转化为商业结果?

点击链接下载完整报告

01

全球市场持续扩容,增长逻辑发生了什么变化?

洞察一:全球电商从“规模扩张”转向“长效经营”

全球电商大盘持续扩容。eMarketer数据指出,2026年至2028年全球零售电商销售额预计将从6.8万亿美元增长至近8万亿美元,仍保持约7%的年增长水平。美国、欧洲等成熟市场继续构成重要基本盘,亚太地区持续发挥全球电商规模增长极作用,拉美、中东等新兴市场也在进一步释放潜力。与此同时,不同区域在消费需求、渠道生态与经营规则上的差异更加显著,品牌竞争也从单一商品和流量竞争,迈向综合经营能力的比拼。

洞察二:政策护航跨境电商双循环发展

政策体系持续支撑跨境电商双循环发展。进口端,通关便利化与进口商品清单优化不断扩充国内优质供给;出口端,出口退税、海外仓建设及跨境电商发展等相关政策持续完善。2026年一季度,我国跨境电商进出口总额达6184.6亿元,其中出口4735.5亿元、进口1449.1亿元。这一政策框架既助力中国品牌拓展海外市场,也为海外品牌进入中国营造了更成熟的经营环境。

洞察三:AI与合规双变量重塑跨境电商运营逻辑

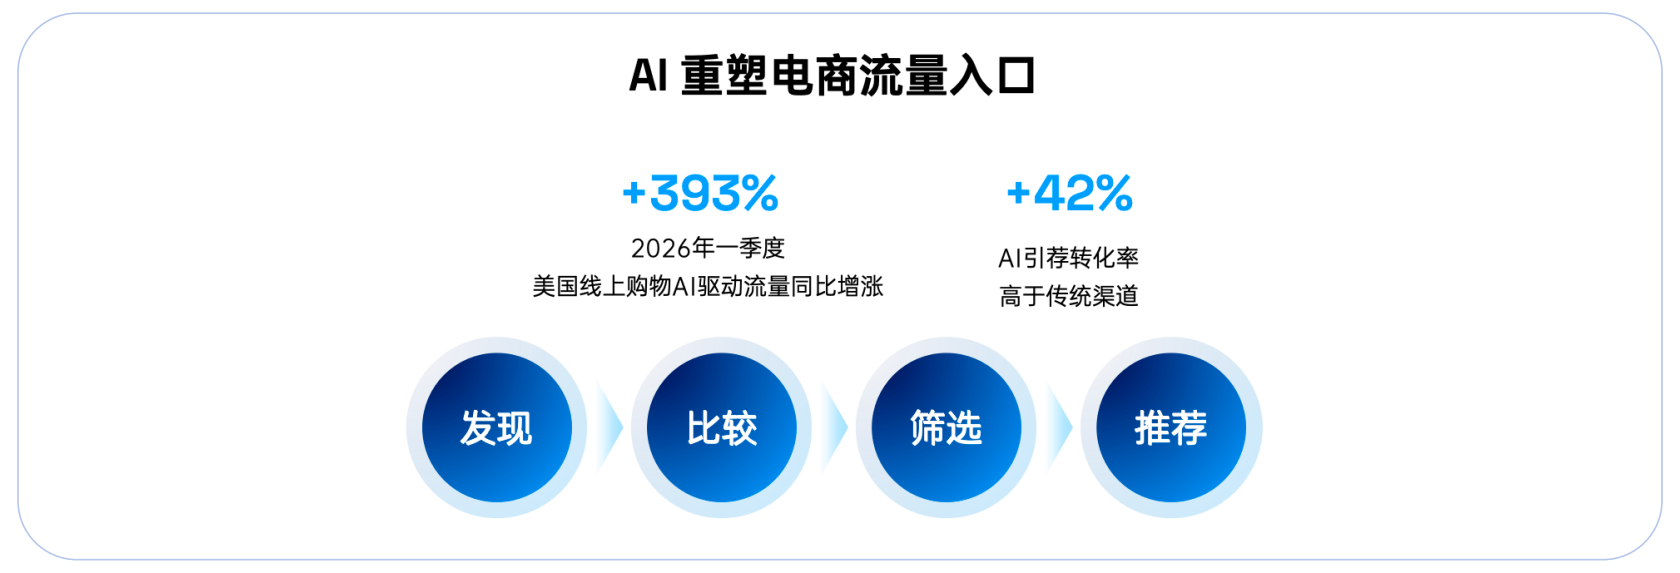
AI重塑电商流量入口。Adobe Analytics数据显示,2026年一季度,生成式AI驱动的美国线上购物流量同比增长393%,其引荐转化率比传统渠道高出42%。消费者购物入口正从“主动搜索”向“表达需求”延伸,推动品牌流量运营从传统SEO进一步向GEO(生成式引擎优化)拓展。

与此同时,全球税务、环保和数据合规要求持续趋严。品牌需要将合规审查前置至选品、上架、营销和物流等环节,并建立覆盖不同市场的动态监测体系。

AI抬高效率上限,合规要求明确经营底线,两者共同推动全球电商更加重视长期经营质量。

02

品牌全球化机会扩大,经营复杂度同步上升

机会一:行业红利向品牌企业集中

随着流量红利释放趋缓、合规成本和营销成本提高,主要依赖低价供应链和铺货模式获得增长的商家面临更高的经营压力,而具备技术研发、产品溢价与敏捷供应链能力的品牌企业迎来新的发展机会。Marketplace Pulse数据显示,2025年亚马逊全球站点销售额超过百万美元的卖家数量由2021年的6万家增至超过10万家,年销售额超过亿美元的大卖家数量也由50家增至235家。

机会二:全渠道覆盖盘活用户长效价值

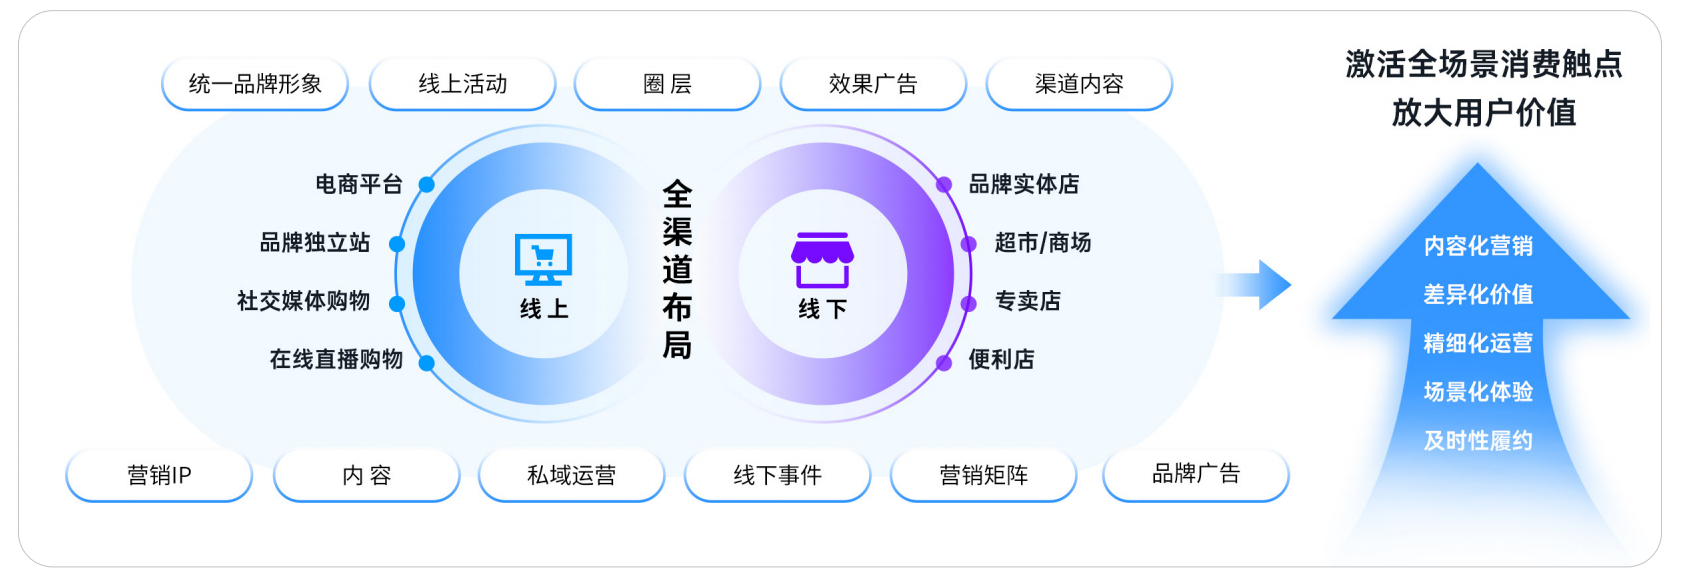
数据显示,全球73%的消费者会选择跨渠道购物。随着消费者购物路径更加非线性,品牌经营不再局限于单一电商平台,而是逐步形成由第三方平台、独立站、社交电商与实体零售共同组成的渠道矩阵。品牌通过用户行为和销售数据识别个性化需求,并结合本地化服务持续深化消费者连接,有机会进一步释放用户长期价值。

机会三:消费体验升级打开供应链价值空间

高效履约、产品质量与个性化服务正在更加显著地影响消费者购买决策。品牌不仅需要在制造端持续提升产品创新和质量能力,也需要在交付端以更加高效、安全和便捷的物流、支付与相关服务,回应消费者对速度和体验的更高要求。

三大机会加速释放的同时,全球化运营也面临三大卡点。

卡点一:传统直营模式面临资金成本压力

品牌自建运营、营销和客服等团队,不仅需要承担持续的人力与市场投入,还需自行完成全球备货,并承担库存、物流与仓储成本。数据显示,跨境电商供应链业务成本中,产品成本约占20%—30%,广告营销成本约占10%—15%,物流仓储成本约占15%—20%,重投入运营模式进一步加大资金周转压力。

卡点二:服务商多头管理稀释本土化成效

亿邦智库调研显示,62.5%的品牌认为本土化能力是全球化过程中最需要具备的能力。但在实际经营中,品牌往往需要跨区域对接营销、支付、仓储和合规等多家服务商。各环节缺少统一的经营目标与数据协同,不仅增加管理成本,也会延长决策链路,降低品牌响应市场变化的效率。

卡点三:市场波动加剧库存积压风险

跨境供应链周期较长,当销售预测与实际需求产生偏差,在途库存和海外仓库存容易出现积压;多渠道库存割裂及逆向物流能力不足,又进一步增加库存消化难度。亿邦智库调研显示,61.2%的商家对滞销积压风险表示担忧。

全链路增长伙伴赋能成为破局关键

三大机会与三大卡点共同说明,品牌需要的不只是更多服务商,而是能够统一经营目标、整合全球资源并共同承担结果的增长伙伴。《报告》认为,这类伙伴需要具备四项核心能力:风险共担、全链路整合、数据驱动与本地化运营。判断其价值,也不能只看单项服务能力,而要看其能否将利益机制、经营目标、数据系统和市场执行真正连接起来。

基于此,《报告》以Pattern栢藤全球电商平台加速器为研究样本,观察这套模式如何转化为具体经营结果。

03

Pattern栢藤如何构建品牌全球化增长系统?

一套体系化方法论,贯穿增长全链路

品牌全球化需要的不只是分散的能力模块,而是一套能够持续运转的经营系统。

围绕这一判断,《报告》将Pattern栢藤(以下简称“栢藤”)全球电商平台加速器的增长方法论概括为四个层次:

第一层,以品牌全球化总经销模型明确责任与利益机制;

第二层,以电商业务增长方程式拆解核心经营杠杆;

第三层,以两大AI引擎驱动运营决策智能化与自动化;

第四层,以双向增长通道连接中国与全球市场。

四个层次分别回答“谁来负责”“经营什么”“如何执行”和“如何进入不同市场”,共同构成一套可以复制和持续进化的品牌全球化增长系统。

第一层:以总经销模型明确责任与利益机制

在传统服务采购关系中,服务商通常按照项目或服务内容收费,品牌则承担主要的库存、市场和经营风险。双方虽然存在合作关系,但经营目标未必完全一致。

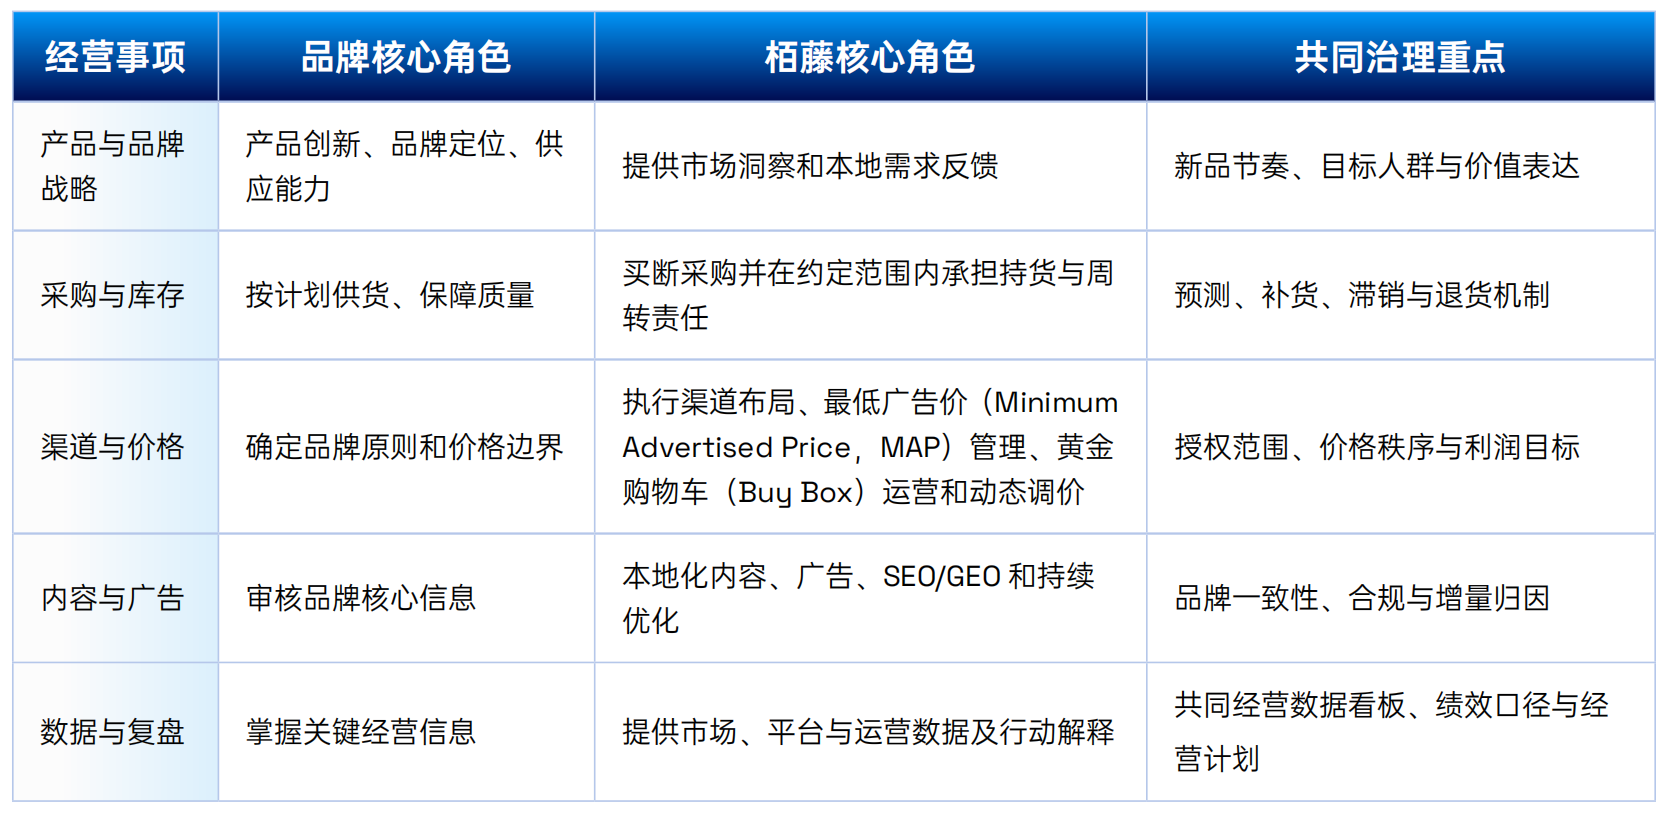
栢藤在品牌授权范围内承接经销与运营职责,通过采销一体、风险共担、全链路整合和本地化执行,将传统服务关系升级为围绕经营结果展开的深度协同。

这一模式主要包含三项机制。

机制一:角色协同,聚焦优势

品牌聚焦产品创新、供应链建设和品牌资产沉淀;栢藤负责授权范围内的市场执行、合规、客服和履约,并将当地市场洞察持续反馈给品牌。双方由简单的服务采购关系,转向围绕同一经营目标展开专业分工。

机制二:采销一体,风险共担

传统代运营模式下,库存、退货和市场波动风险主要由品牌承担;栢藤则通过买断式采销,在约定范围内承担采购、持货与库存周转责任,缓解品牌全球扩张过程中的资金占用和试错压力。双方围绕销售、库存周转与利润表现等指标形成更一致的利益机制。

机制三:共同治理,权责清晰

品牌保留核心战略决策权,栢藤在授权范围内负责具体运营执行;双方围绕价格、渠道、广告和库存等关键事项建立共同治理机制,明确决策边界、信息共享与效果归因,在保持品牌长期价值的同时提升市场响应效率。

总经销模型首先解决“谁来负责”的问题。只有责任、利益和决策边界得到明确,品牌才能从分散的日常运营中抽身,把核心精力放回产品创新与品牌建设。

第二层:以电商业务增长方程式拆解核心经营杠杆

合作机制明确了谁来负责,电商业务增长方程式则进一步回答双方应该管理什么。

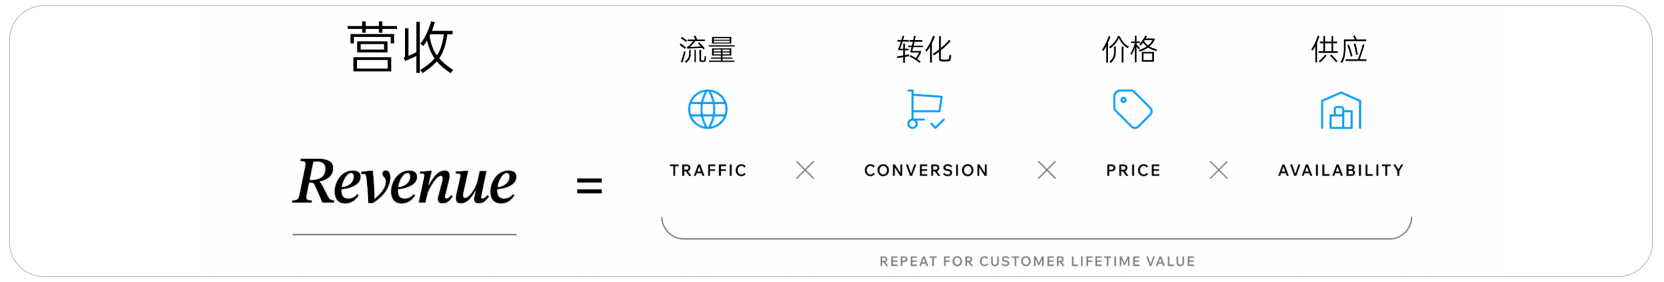
基于全景式运营思维,栢藤将影响营收增长的核心变量概括为:

营收=流量×转化×价格×供应

流量决定有多少消费者看到商品,转化决定其中有多少需求形成订单,价格决定每笔订单能够实现的价值,供应则决定商品能否保持可售并按时交付。这里的供应不仅指库存数量,也包括备货、库存周转和履约保障能力。

四个杠杆共同构成一条完整的增长链路。任何一个环节出现短板,都会影响最终营收。流量不足,品牌难以获得有效需求;转化不足,流量无法形成订单;价格与市场不匹配,会影响转化和价值获取;供应不足,则可能造成缺货、交付延迟和销售损失。

通过电商业务增长方程式,品牌可以在营收发生变化时判断问题来自哪个环节,并据此确定资源投入和优化重点。增长管理由此从笼统的业绩目标,转化为可以衡量、执行和持续改进的经营任务。

第三层:以两大AI引擎驱动运营决策智能化与自动化

在明确合作机制与增长路径后,品牌还需要将其落实到日常运营中,通过数据与AI持续识别增长机会、优化运营决策,并自动执行具体任务。

截至2026年9月,Pattern栢藤已沉淀逾91万亿个数据点,并拥有44项专利(含已授权及申请中)。依托这一数据与技术底座,公司将人工智能深度应用于品牌增长的每个环节,并借助自研模型与全栈技术体系,打造AI自主电商执行引擎Pattern Intelligence(Pi)和智能广告引擎Destiny,助力品牌以更高效率及更强可预测性实现全球化增长。

Pi AI自主电商执行引擎构建“感知—决策—执行—反馈”的智能运营闭环。Pi通过持续监测产品报价、广告、内容、定价和库存,在识别机会或风险后自动执行优化或修复操作;当需要品牌判断时,则将决策项推送至人工审批。自部署以来,Pi已在其品牌组合中执行数百万次自动操作,包括恢复产品推荐位、调整价格和修复内容,并实现24/7全天候运行。

Destiny智能广告引擎则专注于广告的真实增量价值。它融合广告、消费者行为和产品表现数据,通过自动竞价与预算调整优化资源配置,帮助品牌从关注曝光和广告销售,进一步转向衡量广告对实际增长的贡献。

第四层:以双向增长通道连接中国与全球市场

AI引擎为品牌提供决策与执行能力,栢藤的渠道网络和本地化运营体系,则负责将这些能力转化为具体市场中的经营成果。

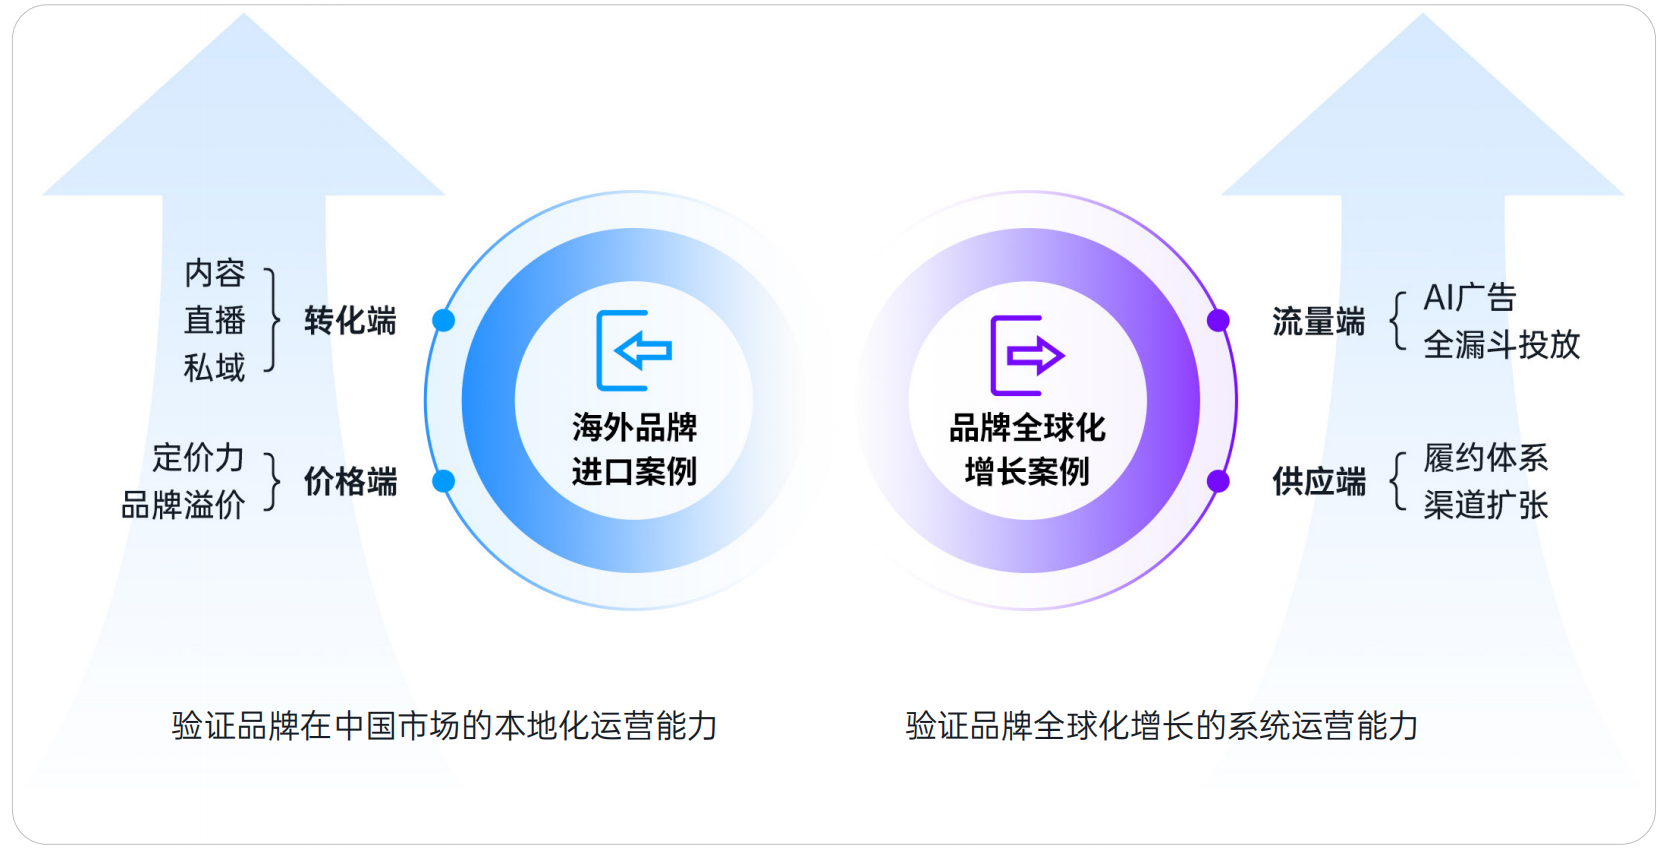
在进口端,栢藤覆盖天猫、京东、抖音和小红书等主要渠道,并结合中国消费者的购买路径,为海外品牌提供渠道布局、内容运营、进口合规、仓储履约和售后服务,帮助品牌进入并持续经营中国市场。

在全球市场拓展端,栢藤依托全球主流电商平台合作网络和本地化运营能力,帮助品牌进入北美、东南亚、日韩、拉美和中东等市场,并将渠道运营、营销增长、库存履约和合规管理纳入统一经营体系,降低品牌进入新市场的前期投入和经营风险。

两条增长通道共享同一套总经销模型、数据能力和技术体系。通过不同市场的本地化执行,栢藤将全球资源转化为具体的经营成果。

04

六大品牌实践验证全球化增长成效

《报告》从海外品牌进入中国与品牌拓展全球市场两个方向,选取六个代表性案例,呈现不同品牌如何借助栢藤的全链路能力突破具体经营难题。

海外品牌进口案例:

案例一|KELO-COTE芭克:围绕平台运营、价格治理、内容增量与本地化直播构建增长体系,一年内跃居天猫国际品类领导者

案例二|THORNE悦恩:合作仅6个月,核心单品挺进天猫品类销量TOP10

案例三|Swanson斯旺森:在强化传统货架电商基本盘的同时,通过KOL、KOC种草矩阵与差异化平台运营拓展社交电商

全球化品牌增长案例:

案例四|Balance of Nature:通过广告与内容优化、品牌保护、物流体系和系统化运营支持,合作两年内收入实现翻倍

案例五|Bosch舒适科技:18个月内进入13个新市场并推出28款新品,相关产品不到6个月登上亚马逊热水器品类第一

案例六|SPANX:通过Destiny智能广告引擎识别广告带来的真实增量价值,合作一年内推动SPANX广告销售额同比增长120%

05

品牌全球化进入“共生时代”,从交易信任走向生态协同

全球化经营复杂度持续提升,品牌与合作伙伴之间的关系正在被重新定义。《报告》将这种变化概括为三个方向:合作基础从“交易信任”走向“系统信任”,合作目标从“服务交付”走向“价值共创”,竞争单元从“单点能力”升级为“经营生态”。

系统信任来自持续的信息共享和清晰的责任边界。品牌保留产品、品牌与长期战略的主导权,合作伙伴基于市场、价格、库存和增长数据参与渠道规划与日常经营,双方共同面对市场变化并承担经营结果。

无论是海外品牌进入中国,还是中国品牌拓展全球市场,全球化下一程所比拼的,不只是进入市场的速度,而是能否将目标、数据、资源和执行连接成一个整体,并将这套协作能力复制到更多市场。当经营目标、全球资源和增长责任真正贯通,品牌才能以更轻的投入和更低的系统性风险,获得更加稳定、可持续的全球增长。

这正是“智赢·共生”的真正内涵。

欲了解更多《报告》内容,洞察品牌全球化发展趋势,深入了解Pattern栢藤如何以全球电商平台加速器助力品牌长效增长,请点击链接获取完整版报告

本文首发于 亿邦动力 官方网站

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

品牌开展全球化经营会遇到哪些核心难点?

品牌全球化经营主要面临三大卡点:一是传统直营模式需承担人力、备货、物流仓储等重投入,资金周转压力大;二是多头对接不同区域服务商,协同效率低,稀释本土化运营成效;三是跨境供应链周期长,库存易出现积压风险。

当前全球电商行业的核心发展趋势是什么?

2026-2028年全球零售电商年增速约7%,规模将从6.8万亿美元增长至近8万亿美元,发展逻辑从规模扩张转向长效经营;生成式AI重塑流量入口,全球合规要求趋严,行业竞争从商品、流量比拼转向综合经营能力竞争。

品牌全球化需要选择什么样的合作伙伴?

品牌全球化需要的不是零散服务商,而是具备风险共担、全链路整合、数据驱动、本地化运营四项核心能力的增长伙伴,这类伙伴可统一经营目标、整合全球资源、共同承担经营结果,帮助品牌降低扩张风险。

Pattern栢藤能为全球化品牌提供哪些核心支持?

Pattern栢藤通过总经销模式与品牌风险共担,缓解品牌资金压力;依托自研Pi自主电商执行引擎、Destiny智能广告引擎提升运营效率;同时覆盖中国及海外多区域渠道,提供运营、合规、履约等全链路本地化服务。

这么好看,分享一下?

朋友圈 分享

APP内打开

+1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0