广告
加载中

亿邦动力郑敏:全球化新品牌进入“物种爆发期” 供应链+工程师+审美形成新交叉点

亿邦动力 2026-09-17 15:34
亿邦动力 2026/09/17 15:34

邦小白快读

EN
全文速览

本文为跨境生态大会上发布的行业核心报告解读,包含了解全球消费趋势、跨境相关务实参考的关键信息。

1. 核心行业走向:未来两到三年全球零售电商仍将保持约7%的增速,但市场份额会加速向规模化、可持续增长的企业集中,其中亚马逊平台年销售额超1亿美元的卖家年复合增速达47%,远高于行业平均水平;当前用户消费机会的发现路径已经从搜索、社交推荐进入AI发现阶段,AI带来的流量转化率比传统方式高42%,超七成网购用户会跨平台流转下单。

本文也给出了实用的行动参考。

1. 无论是参与跨境创业还是做消费类业务,不必从零搭建所有运营能力,可选择靠谱的合作伙伴共担库存、运营压力,共同建设全域运营能力。

2. 品牌价值分为三层,做好质量可获得20%左右的信任溢价,做好功能能获得用户信赖,做好审美与价值观共鸣能获得更高的用户忠诚度,中国供应链、工程师能力与审美的交叉优势正催生大量新品牌机会。

本文包含品牌全球化布局的趋势判断、渠道模式参考、品牌建设路径等核心决策参考信息。

1. 市场与用户趋势:未来两到三年全球零售电商仍保持7%左右增速,但份额向头部规模化企业集中;73%的用户会跨平台购物,消费触点高度分散,AI带来的流量转化率较传统方式高42%,消费发现路径已进入AI发现阶段。

2. 行业共性痛点:当前品牌出海有两大突出难题,61.2%的商家面临海外库存滞销风险,近6成商家难以统筹协调本土化服务商,单一渠道运营很难承接全域流转的用户。

品牌商可参考新型合作模式与品牌建设逻辑优化经营。

1. 可探索共同治理的零供合作关系,选择类似Pattern这类能采销买断分担库存风险、全量回传销售与用户数据的合作伙伴,将供应能力纳入传统流量增长公式,跳出流量成本高企、价格战的恶性循环,标杆案例显示这类合作可帮助品牌实现150%-200%的销售额增长,维持稳定品牌溢价。

2. 品牌建设沿信任、信赖、信仰三层推进,做好质量支撑20%左右溢价,做好功能获得用户信赖,结合极简科技、东方美学等成熟审美流派打造价值共鸣,可实现长期品牌增值。

本文梳理了跨境电商领域的增长机会、风险提示、新型合作模式与可落地的经营方法,对出海卖家有较强实用价值。

1. 机会与风险提示:未来两三年全球零售电商仍有7%左右的增速,AI带来的流量转化率比传统方式高42%,消费发现进入AI阶段,依托中国供应链、工程师、审美能力交叉优势打造新品牌正处在窗口期;但市场份额正向规模化、可持续增长的企业集中,缺乏核心能力的中小卖家会面临份额挤压,当前超6成卖家存在海外库存滞销风险,近6成难以协调本土化服务商,73%的用户跨平台购物,单一渠道运营很难承接用户。

卖家可参考新经营逻辑与合作方式降本提效。

1. 传统流量×转化率×客单价的增长公式已显现流量贵、价格战的弊端,需将供应能力纳入增长逻辑,沿着质量、功能、审美三层路径积累品牌价值。

2. 不必强行自建全链路全域运营能力,可选择类似Pattern这类能采销买断分担库存风险、具备AI运营与全球合规能力、可回传全量数据的合作伙伴共同拓市。

本文包含了跨境品牌爆发期的产品设计生产需求、工厂可把握的商业机会、数字化触电的实用启示。

1. 市场机会与产品方向:当前中国全球化新品牌进入物种爆发期,核心支撑是中国供应链、工程师能力、审美表达的交叉优势,工厂可依托自身供应链能力,对接具备全球化运营能力的品牌方、类似Pattern这类专业服务商,切入全球跨境赛道。

2. 产品设计生产的需求层次:品牌端对产品的需求对应三层价值,首先要稳定品质支撑品牌的信任溢价,其次要优化功能设计带来良好使用体验,获得用户信赖,还要匹配极简科技、东方美学、潮玩萌系、阳光松弛等主流审美方向,支撑品牌的价值观共鸣。

工厂对接电商渠道可参考新的协同逻辑。

1. 可参与构建共同治理的零供关系,与渠道、运营方共享供应信息,同时获取前端销售、用户偏好的回传数据,按需调整生产计划,降低库存滞销风险。

2. 可借助合作方的AI电商工具捕捉市场机会、识别风险、了解用户偏好,提升生产端数字化响应能力,不必独立搭建全链路电商团队。

本文梳理了品牌全球化服务领域的行业趋势、客户核心痛点、标杆服务商的模式经验,对服务商发展有较强参考价值。

1. 行业趋势与技术方向:未来两三年全球零售电商保持7%左右增速,市场份额向规模化品牌集中,品牌出海必须具备全域运营能力,服务市场空间广阔;技术层面AI带来的流量转化率比传统方式高42%,消费发现进入AI阶段,AI技术在电商服务领域有明确的提效价值。

2. 客户核心痛点:品牌客户的普遍难题集中在两方面,61.2%的商家面临海外库存滞销压力,近6成商家难以统筹协调本土化服务商,同时用户跨平台流转比例达73%,全域触点运营难度高。

服务商可借鉴标杆经验打磨解决方案。

1. 参考Pattern的共同治理零供服务模式,采用采销买断制为客户分担库存风险,打破传统经销的数据壁垒,全量回传销售、用户数据,将供应服务纳入客户增长逻辑。

2. 打造基于海量数据与自研模型的AI电商执行引擎,形成机会发现、广告优化、全球合规的全链路服务能力,参考其服务多品类品牌的成功经验,为客户提供定制化落地服务。

本文包含了跨境电商领域的商家真实需求、行业发展风向、平台运营优化方向等核心参考内容。

1. 行业风向变化:未来两三年全球零售电商保持7%左右增速,份额向规模化、可持续增长的商家集中,消费发现路径进入AI阶段,AI带来的流量转化率较传统方式高42%,73%的网购用户会跨平台流转,单一渠道很难完整承接用户需求。

2. 商家核心诉求:当前商家的普遍痛点集中在两方面,超6成商家面临海外库存滞销压力,近6成商家难以统筹协调各类本土化服务商,对全域运营支持、风险分担机制、数据反馈链路有明确需求。

平台可从运营、招商两方面优化布局。

1. 运营层面可完善AI导购、AI流量匹配功能提升转化效率,将类似Pattern的新型优质服务商纳入生态,搭建商家与各类服务商的对接通道,探索风险共担、数据互通的零供协同机制,帮助商家降低库存压力,避免流量成本过高引发的低价竞争问题。

2. 招商方向可重点关注依托中国供应链、工程师能力、审美优势的新品牌,引导商家从卖货思维转向品牌思维,实现长期可持续增长。

本文呈现了跨境电商产业的最新发展动向、新型商业模式、产业演进逻辑,具备较强的研究参考价值。

1. 产业新动向与新问题:增长结构方面,未来两三年全球零售电商仍将保持约7%的增速,但市场份额加速向规模化经营主体集中,亚马逊平台年销超1亿美元的卖家年复合增速达47%,远高于行业平均和百万级卖家增速,头部集中趋势明显;消费端,消费机会发现路径从搜索、社交发现进入AI发现阶段,AI引流转化率比传统方式高42%,73%的用户跨平台购物,触点高度分散;产业端仍存在传统零供博弈的固有矛盾,以及库存滞销、本土服务商协调难等普遍痛点。

产业领域涌现的新模式与新判断值得关注。

1. 以Pattern为代表的新型服务商探索出区别于传统代运营、经销代理的第三种模式,即共同治理的零供关系,通过采销分担库存、数据双向打通,将供应纳入传统增长公式破解增长瓶颈。

2. 中国全球化新品牌进入物种爆发期,供应链、工程师能力、审美形成新交叉点,品牌价值沿信任、信赖、信仰三层递进,已形成四类辨识度较高的审美流派,跨境电商正从卖货阶段全面转向品牌阶段。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

This article breaks down a core industry report released at the Cross-Border E-Commerce Ecology Conference, sharing key insights on global consumer trends and practical takeaways for cross-border business participants.

1. Core industry trajectory: Global retail e-commerce is set to grow at around 7% annually over the next two to three years, but market share will increasingly concentrate among large-scale, sustainably growing operators. On Amazon, for example, sellers with annual revenue of over $100 million are posting a compound annual growth rate of 47%, far outpacing the industry average. Consumers’ path to product discovery has also shifted beyond search and social recommendations to the AI-powered discovery stage, where AI-driven traffic delivers a 42% higher conversion rate than traditional channels, and more than 70% of online shoppers browse and purchase across multiple platforms.

The report also lays out practical action guidance for practitioners:

1. For cross-border entrepreneurship or consumer business operators, there is no need to build all operational capabilities from scratch. Reliable partners can be brought in to share inventory and operational burdens, and jointly build full-funnel, cross-channel operational capabilities.

2. Brand value falls into three tiers: solid product quality delivers roughly 20% trust-based price premium; strong functional performance earns user reliability; and aligned aesthetics and shared values drive higher user loyalty. The intersecting strengths of China’s supply chain, engineering talent pool, and design capabilities are creating massive opportunities for new brand launches.

This article provides core decision-making references for brands pursuing global expansion, covering trend forecasts, channel model options, and brand-building pathways.

1. Market and user trends: Global retail e-commerce will maintain around 7% annual growth over the next two to three years, with market share concentrating among large-scale leading players; 73% of consumers shop across multiple platforms, leading to highly fragmented consumer touchpoints; AI-driven traffic delivers a 42% higher conversion rate than traditional channels, as product discovery enters the AI-led era.

2. Common industry pain points: Brands expanding overseas face two prominent challenges: 61.2% face risks of unsold overseas inventory, nearly 60% struggle to coordinate local service providers, and single-channel operations are unable to capture users who flow across multiple platforms.

Brands can leverage new cooperation models and brand-building frameworks to optimize operations:

1. Explore collaborative, co-governed retailer-supplier partnerships. For example, partners such as Pattern, which purchase inventory outright to share stock risk and fully share back sales and user data, can help brands integrate supply capabilities into the traditional traffic-driven growth formula, breaking the vicious cycle of rising traffic costs and price wars. Benchmark cases show this cooperation model can deliver 150%–200% sales growth for brands while sustaining stable brand premiums.

2. Brand building progresses across three tiers: trust, reliance, and advocacy. Quality supports an approximately 20% price premium, strong functional performance earns user reliance, and value resonance built around established aesthetic schools such as minimalist tech and Eastern aesthetics drives long-term brand value appreciation.

This article outlines growth opportunities, risk warnings, new cooperation models, and actionable operational strategies for cross-border e-commerce, offering high practical value for sellers expanding globally.

1. Opportunities and risk alerts: Global retail e-commerce will grow at around 7% annually over the next two to three years; AI-driven traffic delivers a 42% higher conversion rate than traditional channels as product discovery enters the AI era; there is a clear window to build new brands leveraging the intersecting strengths of China’s supply chain, engineering talent, and design capabilities. However, market share is concentrating among large-scale, sustainably growing operators, squeezing small and mid-sized sellers without core competencies. Currently, more than 60% of sellers face risks of unsold overseas inventory, nearly 60% struggle to coordinate local service providers, and 73% of consumers shop across platforms, making single-channel operations insufficient to capture user demand.

Sellers can adopt new operational logics and cooperation models to reduce costs and improve efficiency:

1. The traditional growth formula of traffic × conversion rate × average order value has exposed flaws including surging traffic costs and price wars. Operators need to integrate supply capabilities into their growth logic, and build brand value across the three tiers of quality, functionality, and aesthetic appeal.

2. There is no need to force full-stack, cross-channel operational capabilities in-house. Sellers can partner with providers such as Pattern – which purchases inventory outright to share stock risk, offers AI operations and global compliance capabilities, and shares full transaction and user data – to jointly expand into global markets.

This article covers product design and manufacturing demands amid the boom of cross-border brands, actionable business opportunities for factories, and practical insights for digital engagement in the e-commerce space.

1. Market opportunities and product directions: China’s new global brands are entering a period of explosive growth, supported by the intersecting advantages of domestic supply chains, engineering capabilities, and aesthetic expression. Factories can leverage their own supply chain strengths to partner with globally capable brand operators and specialized service providers such as Pattern, to tap into the global cross-border e-commerce track.

2. Hierarchy of product design and production demands: Brand demand for products maps to three value tiers: first, stable quality to underpin brands’ trust-based price premiums; second, optimized functional design to deliver strong user experience and earn user reliance; third, alignment with mainstream aesthetic trends including minimalist tech, Eastern aesthetics, cute pop-culture design, and relaxed, sunlit lifestyle themes, to support brands’ value resonance with consumers.

Factories working with e-commerce channels can reference new collaboration frameworks:

1. Participate in building co-governed retailer-supplier relationships, sharing supply information with channel and operation partners while receiving front-end data on sales performance and user preferences, to adjust production plans on demand and reduce unsold inventory risks.

2. Leverage partners’ AI e-commerce tools to capture market opportunities, identify risks, and understand user preferences, improving digital response capabilities on the production side without building a full in-house e-commerce team independently.

This article maps industry trends, core client pain points, and benchmark service provider model experiences in the global brand services space, offering strong reference value for service provider development.

1. Industry trends and technology directions: Global retail e-commerce will grow at around 7% annually over the next two to three years, with market share concentrating among large-scale brands. Brands expanding overseas must build cross-channel, full-funnel operational capabilities, creating broad market space for service providers. On the technology front, AI-driven traffic delivers a 42% higher conversion rate than traditional channels, as product discovery enters the AI era, giving AI clear efficiency-boosting value across e-commerce service scenarios.

2. Core client pain points: Brand clients face two widespread challenges: 61.2% face pressure from unsold overseas inventory, nearly 60% struggle to coordinate local service providers, while 73% of users flow across platforms, making cross-touchpoint full-funnel operations highly complex.

Service providers can reference benchmark experiences to refine their solutions:

1. Draw on Pattern’s co-governed retailer-supplier service model, which uses outright inventory purchasing to share stock risk for clients, breaks down data silos common in traditional distribution models, fully shares back sales and user data, and integrates supply services into clients’ growth logic.

2. Build AI-powered e-commerce execution engines based on massive datasets and self-developed models, to deliver full-stack service capabilities covering opportunity identification, ad optimization, and global compliance. Drawing on the successful experience of serving multi-category brands, providers can deliver tailored, implementation-ready services for clients.

This article offers core references for cross-border e-commerce platforms, including real merchant needs, industry development trends, and directions for platform operation optimization.

1. Shifting industry trends: Global retail e-commerce will maintain around 7% annual growth over the next two to three years, with market share concentrating among large-scale, sustainably growing merchants. Product discovery has entered the AI era, with AI-driven traffic delivering a 42% higher conversion rate than traditional channels; 73% of online shoppers browse and purchase across platforms, meaning single channels cannot fully capture user demand.

2. Core merchant demands: Merchants currently face two widespread pain points: more than 60% face pressure from unsold overseas inventory, nearly 60% struggle to coordinate various local service providers, creating clear demand for cross-channel operational support, risk-sharing mechanisms, and closed-loop data feedback.

Platforms can optimize layout across operations and merchant acquisition:

1. On the operations side, platforms can improve AI-powered product recommendation and AI traffic matching functions to boost conversion efficiency, bring high-quality new service providers such as Pattern into the platform ecosystem, build matchmaking channels between merchants and various service providers, and explore co-governed retailer-supplier collaboration mechanisms featuring risk sharing and data interoperability, to help merchants reduce inventory pressure and avoid low-price competition triggered by excessive traffic costs.

2. For merchant acquisition, platforms can prioritize new brands built on the intersecting strengths of China’s supply chain, engineering capabilities, and design advantages, guiding merchants to shift from a pure transaction mindset to a long-term brand-building mindset for sustainable growth.

This article presents the latest development trends, emerging business models, and industrial evolution logic of the cross-border e-commerce sector, offering strong reference value for research.

1. New industry dynamics and emerging issues: In terms of growth structure, global retail e-commerce will maintain around 7% annual growth over the next two to three years, but market share is accelerating its concentration among large-scale operators. On Amazon, sellers with annual revenue of over $100 million record a 47% compound annual growth rate, far outpacing both the industry average and the growth rate of million-dollar-level sellers, pointing to a clear trend of head concentration. On the consumer side, product discovery paths have evolved from search and social discovery to AI-powered discovery, with AI-driven traffic delivering a 42% higher conversion rate than traditional channels; 73% of users shop across platforms, leading to highly fragmented touchpoints. On the industry side, longstanding frictions in traditional retailer-supplier dynamics persist, alongside widespread pain points including unsold inventory and difficulties coordinating local service providers.

Emerging models and new judgments in the sector warrant close attention:

1. A new type of service provider represented by Pattern has developed a third model distinct from traditional shop operation agencies and distribution agents: co-governed retailer-supplier relationships, which share inventory risk through outright procurement, enable two-way data connectivity, and integrate supply capabilities into the traditional growth formula to resolve growth bottlenecks.

2. China’s new global brands are entering a period of explosive growth, as supply chain capabilities, engineering talent, and design strengths form new intersections. Brand value progresses across three tiers of trust, reliance, and advocacy, with four highly recognizable aesthetic schools already emerging, as cross-border e-commerce shifts comprehensively from a transaction-focused stage to a brand-building stage.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

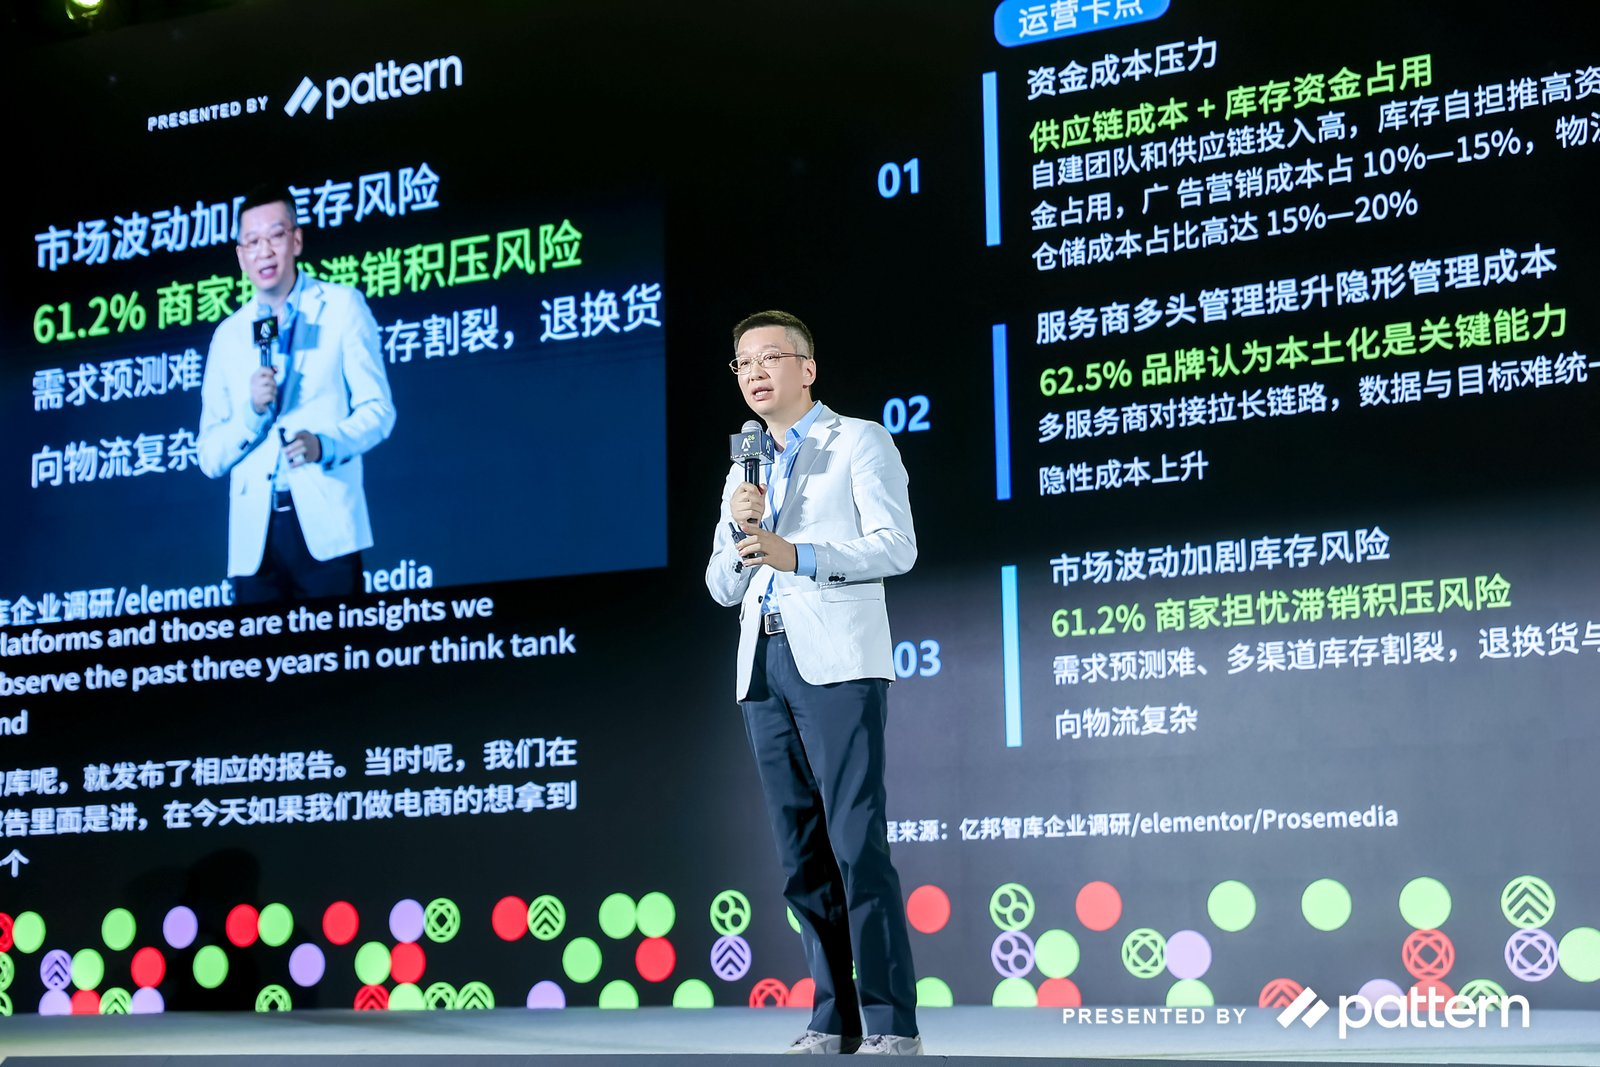
【亿邦原创】9月17日,在“Accelerate 2026 China跨境生态加速大会”上,亿邦动力董事长、亿邦智库院长郑敏解读了由Pattern栢藤与亿邦动力联合发布的《品牌全球化加速增长洞察报告》。他判断,全球零售电商未来两至三年仍将保持增长,但市场结构正在发生变化,更多份额将向可持续、规模化增长的企业集中。

与此同时,“消费机会发现”的历程从以往的信息搜索、电商搜索转向后来的社交发现,再到今天进一步转向“AI发现。用户在全渠道、全域流转,以至于品牌并不知道他会在哪一个触点停下来并完成下单。由此,品牌出海必须具备面向全球市场的全域运营能力——可以自己建设这种能力,也可以寻找优秀的合作伙伴共同建设。

以Pattern为研究样本,郑敏提出,它区别于传统代运营和传统经销代理,形成了一种“共同治理的零供关系”。在这种关系下,品牌与经销商共同服务消费者,并通过数据回传、库存周转和全球运营形成更健康的分工。在传统的“流量×转化率×客单价”增长公式下,“供应”也需要被纳入其中。

在此基础上,郑敏进一步提出,中国全球化新品牌已经进入“物种爆发期”。中国供应链、工程师能力与审美表达正在形成新的交叉点,而品牌建设的核心则是从信任、信赖走向信仰。

(本文根据嘉宾现场演讲整理,在不影响原意的基础上有所删改。)

以下为郑敏演讲实录:


01 全球电商仍在增长,但市场份额正在加速集中

今天上午,大家可能已经感受到了,Pattern是一家非常专业的公司。刚才Dave在分享时有一句话让我非常触动:他们一直在思考,如何让世界上最好的品牌获得成功。我们也非常高兴,这次能够和Pattern联合发布《品牌全球化加速增长洞察报告》。下面,我对报告做一个简要解读。

首先来看趋势。

从2020年以后,中国电商增速已经低于全球零售电商的平均增速。但我们有一个非常重要的判断:未来两至三年,全球零售电商的增速没有明显放缓的迹象,仍将保持约7%的增长,只是增长的结构正在发生变化。这也解释了为什么企业需要走向全球化。

再看亚马逊的数据。2021年至2025年,年销售额超过100万美元的卖家从约6万家增加到10万家以上,数量年复合增长率超过13%;年销售额超过1亿美元的卖家,则从2021年的50家增加到2025年的235家,年复合增长率达到47%。

全球零售电商的平均增速约为7%,百万美元卖家的数量增速超过13%,而销售额超过1亿美元的卖家数量增速达到47%。这说明,接下来市场会把更多份额让给可持续、规模化增长的企业。这是我们的第一个洞察。

第二个洞察与AI有关。

很多朋友已经开始使用AI。我们在报告中特别关注了AI带来的流量转化变化:由AI带来的流量,转化率比传统方式高42%。

今天上午,John在分享中还梳理了一个非常重要的“消费机会发现”历程:最早是以搜索引擎为代表的信息搜索,之后是电商搜索,再后来是社交发现。到了今天,我们看到的是“AI发现”,也第一次听到了“意图电商”这个概念。

第三个趋势洞察,是品牌出海将面临哪些挑战,以及需要建立什么样的能力。

调研显示,品牌出海企业存在两个突出的“60%”:61.2%的商家非常担心海外库存中的商品滞销;另有接近60%的商家担心,应该如何综合协调和管理本土化的各类服务商。

另一项调查显示,全球已有73%的网购用户会进行跨平台购物。三年前,亿邦智库就在报告中提出,今天做电商,想拿到一个用户的订单,就像赌轮盘概率一样。用户在全渠道、全域流转,品牌并不知道他会在哪一个触点停下来并完成下单。

因此,品牌出海必须具备面向全球市场的全域运营能力。企业可以自己建设这种能力,也可以寻找优秀的合作伙伴共同建设。这是我们对品牌全球化能力需求的判断。


02 把“供应”加入增长公式,形成共同治理的零供关系

基于以上洞察,我们对Pattern的商业模式进行了研究。它有两个非常独特的地方。

首先,区别于传统电商代运营,Pattern采取采销买断制。对品牌商来说,这意味着不需要独自承担过多的库存风险。这是它与传统电商代运营的本质区别。其次,Pattern与传统经销代理制也有很大不同。

做过传统商业的朋友都知道,在传统经销代理体系中,渠道合作伙伴往往会把产品如何卖出、以什么价格卖出等信息保护得非常严密,不会轻易把这些数据交给品牌商。但Pattern不会这样。

像Pattern这样的运营服务商,会通过各种方式,尽可能快速地把产品以什么价格卖出、通过什么渠道卖出,以及用户的意图和关注点在哪里等信息反馈给品牌商。

我们一直在思考这个问题。在国内,也有很多批评电商的声音。为什么会批评电商?这背后其实是一个古老的话题——“零供矛盾”。

品牌商、供应商与零售经销商之间始终存在矛盾和博弈。今天我们看到,Pattern在区别于传统代运营和传统经销代理的基础上,跑出了第三种模式:一种共同治理的零供关系。

在这种关系下,品牌与经销商可以形成更加良性的分工,共同服务好消费者,为消费者研发出更好的产品。海量的市场信息和用户诉求能够快速传导给品牌商,经销商同时又能帮助品牌商分担运营和库存周转的压力。

这是我们在研究这份报告时感受到的一个积极变化:品牌方和经销商之间的零供关系正在被重新构建。

电商领域有一个“万能增长公式”,即流量乘以转化率,再乘以客单价。但在Pattern的电商运营增长公式中,还加入了“供应”。

传统增长公式已经暴露出一些问题,例如流量被炒得越来越贵,商品价格被压得越来越低。只有把供应和零供关系放进增长公式,才有可能形成有品牌、可持续的健康增长。这是我们看到的Pattern增长方程式。

在AI方面,Pattern基于海量数据和自研模型,形成了系统化的Agent应用。从应用层面看,它是一个AI自主电商执行引擎,可以发现机会、识别风险,也可以捕捉用户偏好。

既然品牌出海面对的是全球化运营的挑战和需求,就势必要借助AI提高效率。现在看来,Pattern既能把中国品牌带向全球,也能把全球品牌带到中国。进一步来说,它是一家全球电商运营服务商。

我们可以通过几个案例来看这种能力。

Thorne是一个营养补充剂品牌。在Pattern的帮助下,Thorne以天猫国际为主阵地,用六个月时间进入Top 10,其天猫销售额同比增长接近200%,同时保持了较高的品牌溢价。

Kelo-cote是一款祛疤产品,同样以天猫国际为主阵地,其销售额同比增长约150%,品牌溢价达到30%左右。

Spanx是一家塑身衣品牌。Pattern通过Destiny智能广告优化引擎,从广告优化到全漏斗投放,再到数据驱动决策,形成了完整闭环。其排名进入前四的关键词数量同比增长138%。

第四个案例是Bosch,也就是中国消费者熟悉的博世。案例涉及博世的热力产品。由于世界各国对热力产品有很高的安全要求,这个案例更能体现Pattern在全球化运营和合规方面的能力。Pattern用18个月时间,帮助相关产品进入全球13个市场,其中最关键的能力就是合规。

这些案例也进一步解释了,为什么Pattern的增长公式一定要把“供应”纳入其中。只有把供应加进去,才有可能真正把品牌做起来。


03 全球化新品牌进入“物种爆发期”

最后,我想分享亿邦智库今年的一个判断:中国全球化新品牌已经进入“物种爆发期”。

为什么这样判断?因为我们在报告中观察的五条线,最终指向了同一个交叉点:以中国的“供应链+工程师+艺术家”能力为基础形成的新品牌、新品类,即将在全球范围内获得更多用户的喜欢和欢迎。

与此同时,中国跨境电商正在从“卖家”走向“品牌”,品牌意识已经开始觉醒。

亿邦智库认为,品牌的核心是“可信”,并且可以分成三个层次:第一层是信任,第二层是信赖,第三层是信仰。

如果能够获得消费者的信任,产品价格比同类产品高20%是没有问题的;如果产品功能能够为用户带来良好体验,品牌就能形成信赖;如果品牌在价值观和审美上获得用户认可,就能赚到“信仰的钱”。

把质量做好,可以获得信任;把功能做好,可以获得信赖;把价值观和审美做好,才能走向信仰。

经过多年与全球文化和审美流派的交流,中国品牌也已经初步形成了极简科技、东方美学、潮玩萌系、阳光松弛等具有辨识度的审美流派。

以上就是我对亿邦智库与Pattern联合发布的《品牌全球化加速增长洞察报告》的简要分享。祝大家生意兴隆,谢谢大家!

本文首发于 亿邦动力 官方网站

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

品牌出海需要具备哪些核心能力?

当前全球73%的网购用户会进行跨平台购物,用户在全渠道、全域流转,品牌出海必须具备面向全球市场的全域运营能力,可选择自建能力或联合优质合作伙伴搭建,同时需做好库存管理、本土服务商协调,将供应环节纳入增长公式。

全球零售电商市场的份额变化呈现什么特征?

未来两至三年全球零售电商仍将保持约7%的增速,市场份额正加速向可持续、规模化增长的企业集中;2021-2025年亚马逊平台年销售额超1亿美元的卖家年复合增长率达47%,增速远高于行业平均水平。

共同治理的零供关系和传统渠道合作模式有什么区别?

传统代运营模式下服务商不承担库存风险,传统经销代理模式下渠道方不会向品牌开放全量销售与用户数据;共同治理的零供关系下,合作方采取采销买断制分担库存压力,同时回传全链路数据,双方良性分工共同服务消费者。

中国全球化新品牌的发展优势是什么?

中国全球化新品牌已进入物种爆发期,核心发展优势来自中国供应链、工程师能力与审美表达三者形成的新交叉点;品牌建设可沿信任、信赖、信仰三个层级推进,从质量、功能、价值审美多维度获得用户认可与品牌溢价。

AI对品牌全球化运营有什么作用?

当前消费机会发现已经进入AI发现阶段,由AI带来的流量转化率比传统方式高42%,品牌全球化运营可借助AI相关应用识别市场机会、捕捉用户偏好、优化广告投放,有效提升全链路运营效率。

这么好看,分享一下?

朋友圈 分享

APP内打开

+1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0