广告
加载中

商品供给竞争开启 即时零售到了新赛点

姜琪 2026-09-25 16:04
姜琪 2026/09/25 16:04

邦小白快读

EN
全文速览

总1:即时零售已成为确定性增长赛道,规模超万亿,用户超5亿。

1.2025年即时零售规模达11936亿元,同比增长48.3%,预计2030年达2万亿元。

2.全国闪电仓近10万家,白天营业点位超百万,夜间超35万,用户规模超5亿。

总2:商品时代到来,消费者能买到更丰富、更有品质的商品。

1.平台与品牌商正在推进每个商圈新增百万好商品,未来日常购物选择会更丰富。

2.具体场景已实现30分钟内送达品牌床品、冰啤酒、无醇啤酒、出行应急用品等,商品正在精准满足用户即时需求。

3.一人食场景催生小规格粮油调料,相关小规格商品用户数同比增长超40%,单人消费也能获得便利。

总1:即时零售进入商品时代,品牌商应告别流量内卷和低价竞争,转向场景与商品。

1.用户行为:即时零售已成为确定性生活方式,水星家纺入驻后搜索转化率增长210%,销售额增长530%。

2.场景机会:出行场景多品类爆发,如13.9元出游包增146%、2489元运动相机增183%,证明商品型需求巨大。

总2:品牌商可从以下路径拿到新增量。

1.渠道建设:入驻闪电仓、官旗闪电仓等,蕉下官旗内物占比24%,单仓月交易突破15万,效率是常规店4倍。

2.产品研发:做替代升级和定制,如Babycare替代白牌母婴,小规格粮油调料商品用户数增长超40%。

3.平台支持:用商品魔方选品、闪电帮帮升级货盘,参与商品NEXT计划获300亿资源。

总3:全球零售回归商品力,奥乐齐自有品牌占比90%,山姆少而精并反向定义产品,品牌应强化品质与匹配度。

总1:行业拐点已至,仓店配网络趋于饱和,卖家不能再靠猛开仓和价格战赚钱。

1.风险:全国闪电仓已近10万家,同一商圈同质化严重,单仓利润被摊薄,爬坡回本周期拉长。

2.增长逻辑变化:即时零售进入商品时代,商品创新、扩容、提质是最大增长空间,未来每个商圈将新增百万好商品。

总2:卖家可重点把握四类商品机会。

1.未被充分满足的需求、潜在替代升级、需求持续延展、渠道精准定制,都是重要的增量方向。

2.案例:Babycare在闪电仓铺货后替代白牌母婴,小规格商品用户数增长超40%;蕉下官旗闪电仓单仓效率是常规店4倍。

总3:平台提供了成体系的扶持和工具。

1.商品魔方可按LBS颗粒度挖掘本地需求,上架周边缺失商品可获定向流量扶持,已扶持700多万款商品,新品动销时间缩短25%。

2.闪电帮帮支持货盘从白牌升级为品牌,相关品类增长30%以上,并带来更多新客。

3.商品NEXT计划投入300亿,共建30分钟百万商品圈;酒饮闪电仓可低成本切入,平台未来三年计划助力5个连锁品牌获超10亿增量,10个名酒品牌官旗破亿。

总1:即时零售进入商品时代,为工厂带来面向场景的新生产需求。

1.商品扩容和提质是行业增长第一动力,供需缺口意味着工厂有机会围绕未被满足的消费需求开发新品。

2.渠道催生小规格、一人食、出行便携等定制化产品需求,如小规格粮油调料商品用户数增长超40%。

总2:品质和品牌化趋势要求工厂向更高标准升级。

1.全球零售巨头回归商品力,奥乐齐自有品牌占比达90%,沃尔玛聚焦鲜食和自有品牌,工厂可争取成为优质代工或自有品牌供应商。

2.平台推出的闪电帮帮供应链服务,重点支持品质、合规、稳定的供应链能力,帮助商家从白牌向品牌货盘升级,工厂需按此标准组织生产。

总3:即时零售数字化工具带来电商化启示。

1.商品魔方工具能以LBS颗粒度挖掘本地需求,工厂可借平台数据反哺产品设计,从“我产什么卖什么”转向“商圈要什么我产什么”。

2.在即时零售体系下,生产端更靠近消费数据,新品上架到动销时间可缩短25%,倒逼工厂提升快速反应能力。

总1:即时零售正从仓店配竞争转向商品竞争,服务商面对新市场空间。

1.行业进入商品时代,未来每个商圈将新增百万好商品,商品丰富度和品质是增长核心。

2.全球零售业回归商品力,中国即时零售也不例外,服务商的角色要从帮商家铺货扩展到帮商家选好品、组好货。

总2:商家当前的痛点集中在选品和供应链。

1.闪电仓货盘同质化严重,价格战和流量采买难以为继,单仓利润被摊薄;商家急需差异化选品能力。

2.即时零售是LBS、场景和商品逻辑的叠加,铺货门槛高、本地化营销难度大。

总3:服务商可提供的解决方案与机会。

1.借鉴商品魔方模式,为商家提供LBS颗粒度商机发现、选品和复盘服务,挖掘本地未满足需求。

2.围绕品质和合规搭建供应链服务,帮助商家把白牌货盘升级为品牌货盘,提高动销概率。

3.结合出行、聚会、一人食等场景策划商品组合,并提供新品测试、流量运营和库存优化等配套服务。

总1:行业拐点显现,平台需要从流量驱动转向商品供给驱动。

1.仓店配网络饱和,闪电仓近10万家,同商圈同质化严重,商家开仓边际效益递减,价格战难以持续。

2.即时零售用户超5亿,需求从方便升级为对的时间和好商品,平台需把商品作为增长第一动力。

总2:平台最新做法与招商方向。

1.发布商品NEXT计划,投入300亿支持资源,共建30分钟百万商品圈,以新计划吸引品牌商和零售商合作。

2.推出商品魔方工具,以LBS颗粒度帮商家发现本地需求,上架缺失商品可获定向流量扶持,降低选品门槛。

3.开放多层次酒类即时零售基建:名酒官方旗舰店、美团名酒行、酒饮闪电仓,分别面向品牌、经销商和轻资产零售商。

总3:运营管理与风向规避。

1.用闪电帮帮等供应链服务帮助商家迭代货盘,从白牌向品牌升级,形成平台服务闭环。

2.平台应避免单纯比拼仓店密度,而是扶持商品创新和场景化供给,规避价格战和同质化风险,实现持续增长。

总1:产业新动向:即时零售从渠道扩张进入商品供给竞争阶段。

1.2025年即时零售规模11936亿元,同比增长48.3%,预计2030年达2万亿元;闪电仓近10万家,用户超5亿,网络趋于饱和。

2.美团提出即时零售增长本质是消费需求、店仓配网络、商品创新的正向循环,当前商品是最大增长空间。

总2:新问题涌现:同质化竞争与利润摊薄。

1.同一商圈闪电仓货盘同质化严重,价格战和流量采买难以为继,单仓利润被摊薄,开仓边际效益递减。

2.供给端丰富度和品质仍有巨大缺口,出行、聚会、一人食等新需求未被充分满足。

总3:商业模式与治理启示。

1.平台通过商品魔方LBS选品、对缺失商品定向流量扶持、闪电帮帮供应链升级,形成数据驱动的商品供给治理机制;新品动销时间缩短25%。

2.商品NEXT计划(300亿)代表平台与品牌商、零售商共建商品生态的模式创新。

3.全球零售巨头回归商品力(沃尔玛、奥乐齐、盒马、山姆)为中国即时零售提供参照;酒类即时零售预计2027年破千亿,需兼顾品质保障与渠道创新。

4.政策启示:应重视即时零售供应链的品质、合规与稳定性建设,引导平台建立相应扶持和监管机制。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

Instant retail has become a proven high-growth sector, with a market size exceeding one trillion yuan and more than 500 million users.

1. In 2025, the instant retail market reached 1.19 trillion yuan, up 48.3% year-on-year, and is expected to hit 2 trillion yuan by 2030.

2. There are nearly 100,000 lightning warehouses nationwide, with over one million daytime operating points and over 350,000 nighttime points, serving more than 500 million users.

The product era has arrived, giving consumers access to a wider and better-assorted range of goods.

1. Platforms and brands are working to add one million quality products in each commercial district, making everyday shopping choices significantly richer.

2. Specific scenarios now deliver branded bedding, ice-cold beer, non-alcoholic beer, and travel emergency essentials within 30 minutes, showing that products are precisely matching consumers' instant needs.

3. The solo-dining trend has driven demand for small-pack grain, oil, and seasoning products; the number of users buying such small-size SKUs has grown over 40% year-on-year, making convenience possible even for one-person consumption.

Instant retail has entered the product era. Brands should move away from traffic wars and low-price competition and pivot to scenario- and product-driven growth.

1. User behavior: Instant retail has become a definitive lifestyle. After Mercury Home Textiles launched on the platform, its search conversion rate grew 210% and sales grew 530%.

2. Scenario opportunity: Multiple categories in travel scenarios boomed—a 13.9-yuan travel pack increased by 146% and a 2,489-yuan action camera by 183%—demonstrating the huge potential of product-driven demand.

Brands can find new growth through the following paths.

1. Channel building: Join lightning warehouses and official flagship lightning warehouses. At Beneunder's official flagship lightning warehouse, its products accounted for 24% of the assortment, with monthly transaction volume per warehouse exceeding RMB 150,000 and efficiency four times that of a conventional store.

2. Product development: Focus on replacement upgrades and customization. For example, Babycare replaced white-label mother-and-baby products, and users of small-size grain, oil, and seasonings grew over 40%.

3. Platform support: Use Product Cube for assortment selection and Lightning Help to upgrade the product portfolio, and join the Product NEXT Program to access RMB 30 billion in resources.

Global retail has returned to product power: Aldi's private label accounts for 90%; Sam's Club adopts a "fewer but better" approach and reverse-defines products. Brands should strengthen product quality and fit with demand.

The industry has reached a turning point. The warehouse-store-delivery network is approaching saturation, and sellers can no longer make money simply by opening more warehouses and engaging in price wars.

1. Risk: There are nearly 100,000 lightning warehouses nationwide, with severe homogenization within the same commercial district. Per-warehouse profits are being diluted, and the payback period is extending.

2. Changing growth logic: Instant retail has entered the product era. Product innovation, assortment expansion, and quality improvement represent the biggest growth space; each commercial district will add one million quality products in the future.

Sellers should focus on four types of product opportunities.

1. Unmet demand, potential replacement upgrades, continuously extending demand, and channel-specific customization are all important incremental directions.

2. Cases: After Babycare stocked lightning warehouses, it replaced white-label mother-and-baby products, and the number of users buying small-size products grew over 40%; Beneunder's official flagship lightning warehouse achieved four times the per-warehouse efficiency of a conventional store.

The platform offers a systematic set of support and tools.

1. Product Cube can identify local demand at LBS granularity. Sellers listing missing products in their surrounding area receive targeted traffic support. It has supported more than 7 million products and shortened the time from listing to sales by 25%.

2. Lightning Help supports upgrading product portfolios from white-label to branded, driving category growth of over 30% and bringing more new customers.

3. The Product NEXT Program has invested RMB 30 billion to build a 30-minute, million-product ecosystem. Alcohol beverage lightning warehouses offer a low-cost entry point; in the next three years, the platform plans to help five chain brands gain more than RMB 10 billion in incremental sales, and help 10 famous liquor brand official flagship stores surpass RMB 100 million.

Instant retail has entered the product era, creating new scenario-oriented production demand for factories.

1. Assortment expansion and quality improvement are the primary growth drivers of the industry. The supply-demand gap means factories have the opportunity to develop new products around unmet consumer needs.

2. The channel is creating demand for customized products such as small packs, solo-dining portions, and travel-portable items. For example, users of small-size grain, oil, and seasoning products grew over 40%.

Quality and branding trends require factories to upgrade to higher standards.

1. Global retail giants have returned to product power. Aldi's private label accounts for 90% and Walmart focuses on fresh food and private label. Factories can seek to become high-quality OEM or private-label suppliers.

2. The platform's Lightning Help supply-chain service emphasizes quality, compliance, and stable supply capabilities, helping merchants upgrade from white-label to branded product portfolios. Factories need to organize production to meet these standards.

Instant retail's digital tools offer e-commerce insights.

1. The Product Cube tool can identify local demand at LBS granularity. Factories can leverage platform data to inform product design, shifting from "I produce what I sell" to "I produce what the commercial district demands."

2. In the instant-retail system, the production side is closer to consumption data, and the time from new product listing to sell-through can be shortened by 25%, forcing factories to improve rapid-response capabilities.

Instant retail is shifting from warehouse-store-delivery competition to product competition, opening new market space for service providers.

1. The industry has entered the product era. Each commercial district will add one million quality products in the future, making product breadth and quality the core of growth.

2. Global retail has returned to product power, and China's instant retail is no exception. Service providers' role should expand from helping merchants stock products to helping them choose and assemble the right assortment.

Merchants' current pain points are concentrated in assortment selection and supply chain.

1. Lightning warehouse product portfolios are highly homogenized; price wars and traffic buying are unsustainable, and per-warehouse profits are diluted. Merchants urgently need differentiated assortment capabilities.

2. Instant retail combines LBS, scenario, and product logic, making listing barriers high and localized marketing difficult.

Solutions and opportunities for service providers:

1. Draw on the Product Cube model to offer merchants LBS-granularity opportunity discovery, assortment selection, and review services, uncovering unmet local demand.

2. Build supply-chain services around quality and compliance, helping merchants upgrade from white-label to branded product portfolios and improve sell-through rates.

3. Design product bundles around scenarios such as travel, social gatherings, and solo dining, and provide supporting services like new-product testing, traffic operations, and inventory optimization.

A turning point is emerging in the industry. Platforms need to shift from traffic-driven growth to product-supply-driven growth.

1. The warehouse-store-delivery network is saturated: nearly 100,000 lightning warehouses and severe homogenization within the same commercial district mean the marginal benefit of opening new warehouses is declining, and price wars are unsustainable.

2. Instant retail has over 500 million users. Demand has evolved from convenience to the right product at the right time; platforms must make product the primary growth driver.

The platform's latest moves and merchant recruitment directions:

1. Launch the Product NEXT Program with RMB 30 billion in support resources to build a 30-minute, million-product ecosystem, attracting brands and retailers to cooperate.

2. Introduce the Product Cube tool to help merchants identify local demand at LBS granularity. Listing missing products earns targeted traffic support, lowering the threshold for product selection.

3. Open a multi-tiered alcohol instant-retail infrastructure: official flagship stores for famous liquor brands, Meituan Famous Liquor Store, and alcohol beverage lightning warehouses, targeting brands, distributors, and asset-light retailers respectively.

Operations management and risk avoidance:

1. Use supply-chain services like Lightning Help to help merchants iterate their product portfolios, upgrading from white-label to branded products, forming a closed-loop platform service.

2. Platforms should avoid simply competing on warehouse/store density. Instead, they should support product innovation and scenario-based supply, avoiding price wars and homogenization risks and achieving sustainable growth.

Industry trend: instant retail has moved from channel expansion to product-supply competition.

1. In 2025, the instant retail market reached 1.19 trillion yuan, up 48.3% year-on-year, and is expected to reach 2 trillion yuan by 2030. With nearly 100,000 lightning warehouses and more than 500 million users, the network is approaching saturation.

2. Meituan argues that the essence of instant-retail growth is a virtuous cycle of consumer demand, store-warehouse-delivery networks, and product innovation; currently, product is the greatest source of growth.

New issues have emerged: homogenized competition and profit dilution.

1. Lightning warehouses in the same commercial district are highly homogenized; price wars and traffic buying are unsustainable, per-warehouse profits are diluted, and the marginal benefit of opening new warehouses is diminishing.

2. There remains a large gap in supply-side breadth and quality. Emerging needs for travel, social gatherings, and solo dining are not fully met.

Implications for business models and governance:

1. Platforms have formed a data-driven product-supply governance mechanism through the Product Cube LBS-based assortment tool, targeted traffic support for missing products, and Lightning Help supply-chain upgrades. The time from new product listing to sell-through has been shortened by 25%.

2. The Product NEXT Program (RMB 30 billion) represents a model innovation of co-building the product ecosystem with brands and retailers.

3. Global retail giants returning to product power (Walmart, Aldi, Hema, Sam's Club) provide a benchmark for China's instant retail. Alcohol instant retail is expected to exceed 100 billion yuan by 2027, requiring both quality assurance and channel innovation.

4. Policy implications: more attention should be paid to the quality, compliance, and stability of instant-retail supply chains, and platforms should be guided to establish corresponding support and regulatory mechanisms.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

即时零售从“店仓配时代”跨入“商品时代”。

文丨姜琪      编辑丨石磊

【亿邦原创】在近两年消费大盘进入存量博弈的背景下,即时零售成为了零售业极少数具备确定性增长的“破局赛道”。商务部流通产业促进中心披露的数据显示,2025年我国即时零售规模达11936亿元,同比增长48.3%,预计2030年将达到2万亿元。

然而,任何高增长赛道在历经资本与玩家的狂飙突进后,都会迎来新的分水岭。过去几年,行业入局者疯狂开仓、铺店、扩密度。数据显示,截至目前,全国闪电仓数量已接近10万家,如果看全业态口径,在即时零售平台,白天营业点位已超百万个,夜间超35万个,用户规模增长至超5亿。

当“店仓配”的履约网络逐渐趋于饱和,零售商与品牌商们开始遭遇瓶颈:爬坡和回本周期不断拉长,单仓利润被摊薄,同一商圈内的闪电仓货盘同质化严重,靠价格战和流量采买越来越难赚钱,如此一来,继续猛开仓的边际效益将大幅递减。

美团闪购在2026即时零售产业大会上也给出了这样一个判断:即时零售已告别“仓店配时代”,进入“商品时代”。未来3年,全国每个商圈将新增百万好商品,这将是行业增长的第一动力,也是品牌商和零售商的最大增量。

抛开平台立场,这个判断本身也是一种信号。当仓网成为基础设施,“跑什么货、供给什么商品”,开始成为决定玩家生死存亡的分水岭。这是即时零售演进到成熟阶段后,所有从业者都无法回避的必然转变。

01

即时零售拼商品时代到了

如今,一二线城市的年轻人正在加速流动,“择城迁居”成为一种常态化的生存节奏。每一次落脚,都要对空荡的房子重新装置一番。床品在此场景下变得尤为重要,它不需要像大家具那样反复挑选、比价、等待物流,越来越多年轻人习惯确定住处后,打开App,选一套信得过的品牌床品,30分钟内送到,当晚就能睡个好觉。

对于这些人来讲,他们下单时,想象的是一个具体的、有品质预期的商品。水星家纺捕捉到这一需求后,2025年11月入驻美团闪购,至2026年8月,商品搜索转化率增长210%,销售额增长530%。

还有一个比较典型的是酒类,美团闪购数据显示,世界杯开赛后,无醇啤酒销量同比增长292%,精酿啤酒同比增长251%,啤酒订单量也跃居世界杯最热单品。在观赛聚会这类即时性、场景化的消费中,用户不仅想要下单后尽快送到,还希望拿到手里就是冰的,开瓶就能喝。这种需求不提前规划、不需要囤货,也不为了“冰”而妥协品质。

两类商品,两种场景,指向的是,即时零售已经变成一种确定性生活方式,用户想要的不止是方便快捷,还想要在对的时刻拿到好的商品。

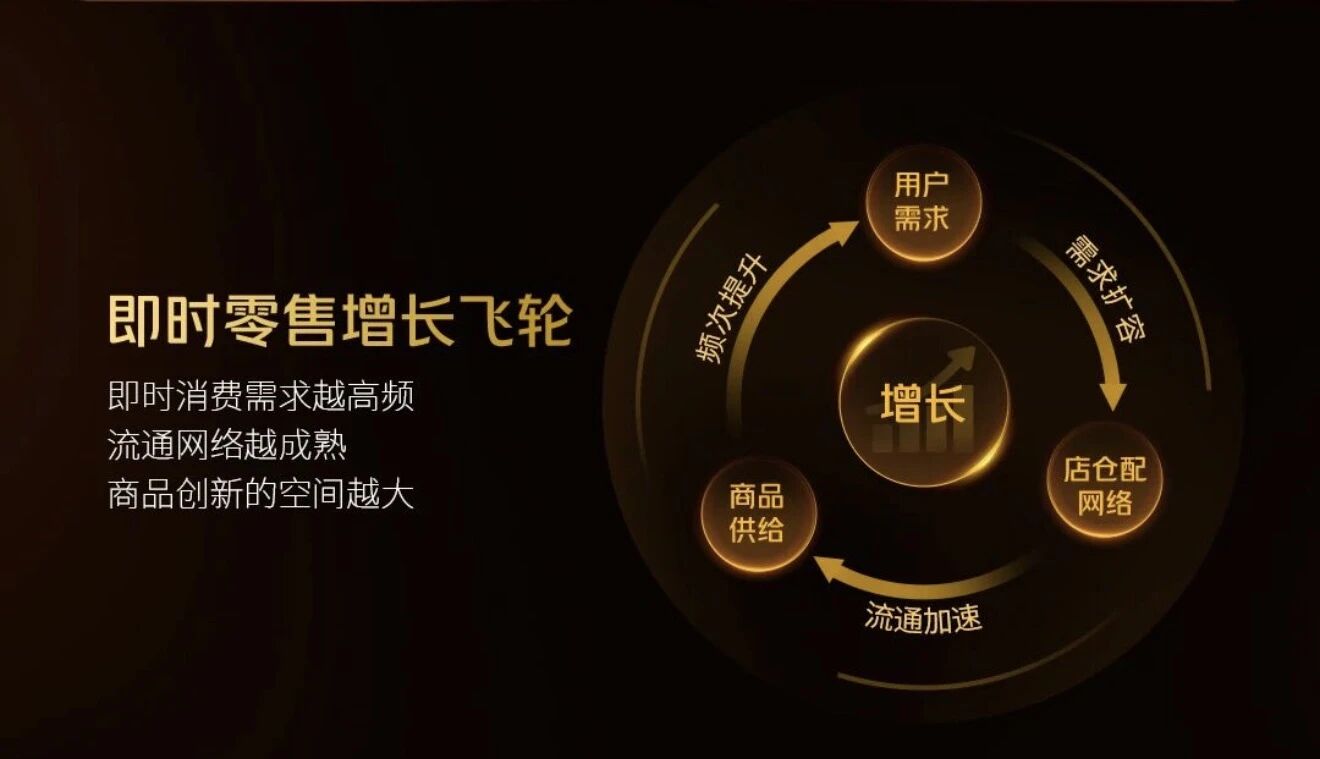
美团核心本地商业CEO王莆中在大会上提到,即时零售增长的本质,来自“消费需求”“店仓配网络”“商品创新”三者之间的正向循环——即时消费需求越高频,流通网络越成熟,商品创新的空间就越大。如今来看,前两者已得到充分发展,“商品”则是当前增长空间最大的一环,商品创新、扩容、提质的时机到了。

过去一年,美团闪购出行场景订单月均从4380万增至6880万,同比提升57%。增长由多类贴合场景的单品拉动:薇诺娜保湿面膜(45元)五一期间涨62%,名创优品一次性出游包(13.9元)增146%,影石Insta360运动相机(2489元)增183%。

从13块9到2489块,价格带跨度接近200倍,但都在出行场景下都展现了强劲爆发力,也就是说,飞轮的第三环——商品——一旦开始转动,它释放的需求将超出想象。

但供给端的丰富度和品质仍有巨大缺口。平台提到,未来每个商圈将新增百万好商品,这侧面说明即时零售的商品丰富度,远未达到用户期待,也远未达到商家可发挥的上限,而缺口也就意味着机会。

02

商品时代,如何拿到新增量?

对于品牌商而言,过去在传统电商里习惯的是流量内卷逻辑——买流量、冲排名、做爆款。但这套逻辑在即时零售里不完全适用,因为即时零售是LBS逻辑、场景逻辑与商品逻辑的叠加。用户打开App,看到的是身边几公里内能买到的东西,决策发生在具体场景里,而非搜索框里。

这意味着品牌商不能再靠一套货盘打天下,而要更好地铺货、直达消费者,把新品铺给合适的用户和场景,追求更稳定的转化。换句话说,品牌商要解决的是,怎么在对的场景里被对的人看到。

零售商同样需要重新思考货盘结构、自有品牌和场景适配。围绕商品,有几个机会方向值得关注:消费者尚未被很好满足的需求、潜在的替代升级、需求的持续延展,以及基于渠道特点的精准定制。

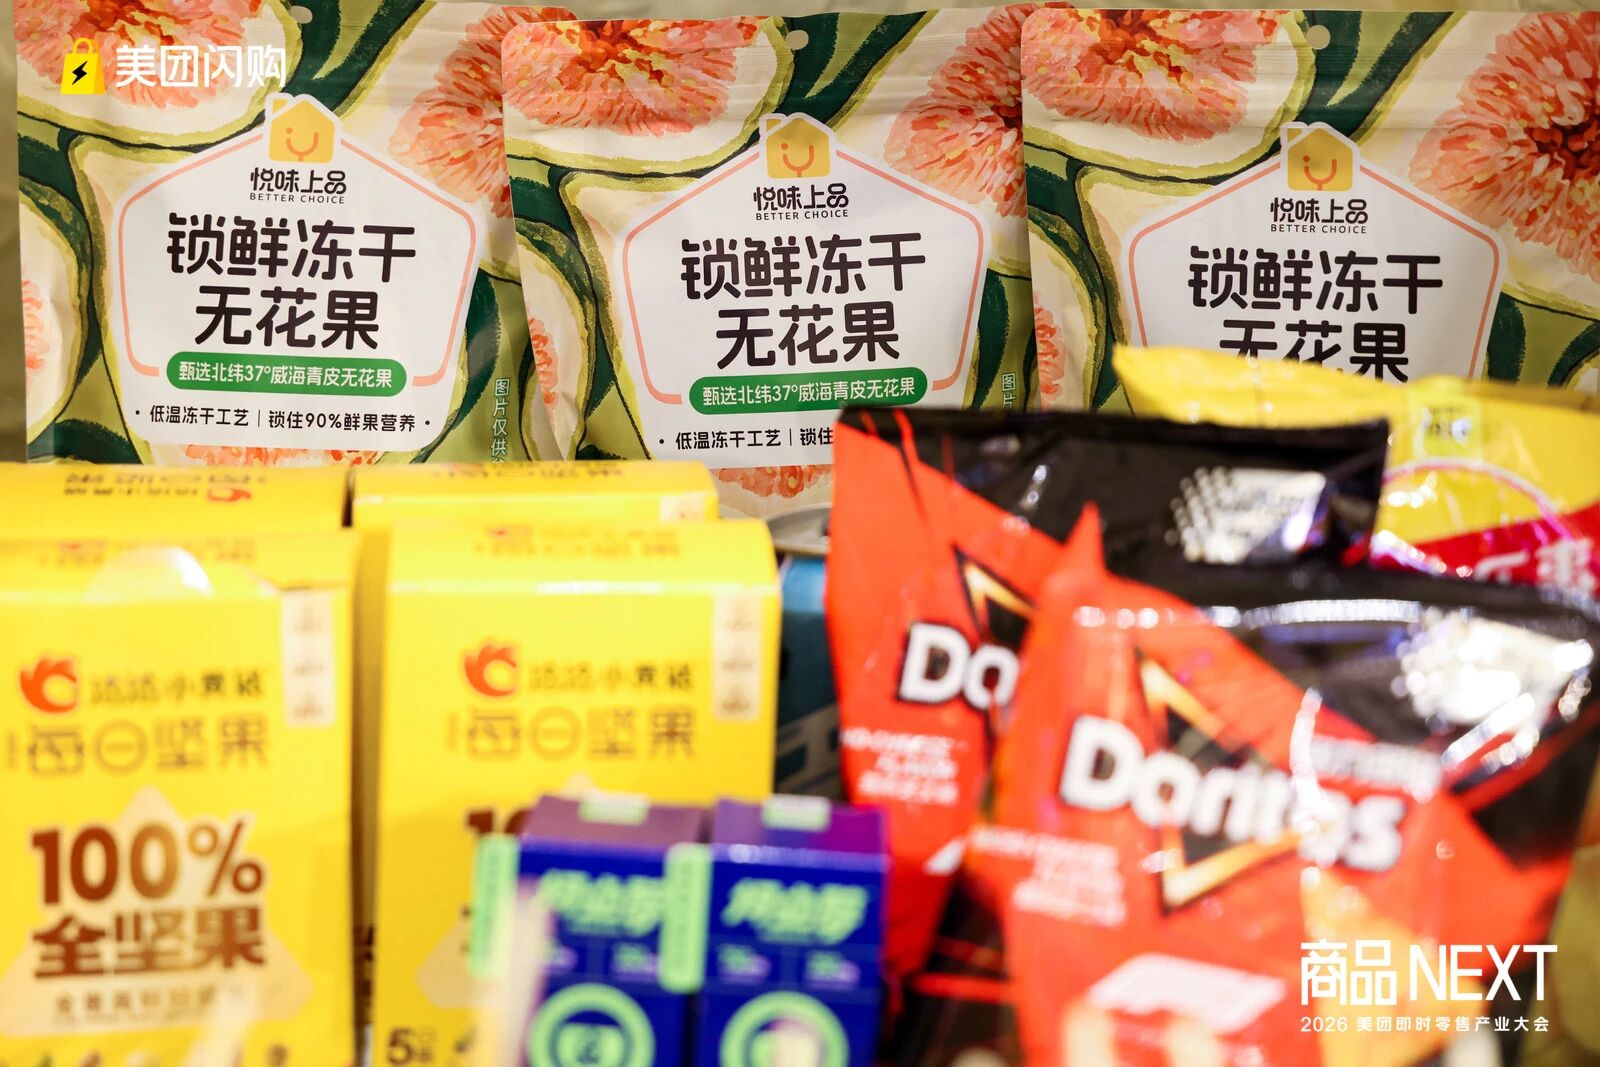
比如Babycare,在美团闪电仓广泛铺货后,对原本的白牌母婴商品形成替代和升级,销量与客单价同样实现了明显提升。另外,在即时零售独特的“一人食场景”,越来越多品牌联合平台定制更小规格的粮油、调料商品,而相关小规格商品用户数同比增长超40%。

方向有了,落地并不容易。即时零售新场景下,铺货门槛较高,基于LBS的营销难度也大。平台能否提供成体系的支持方案,成为商家能否顺利切入的关键。

选品是第一个门槛。一家闪电仓经营着数千甚至上万商品,如何选出真正有差异化竞争力的品,从而获得平台流量与销量增长。在实践中,有商家反馈称,“商品魔方”这一工具帮助其挖掘本地未被满足的需求,效果显著。

商品魔方是美团将商机发现、新品上线、复盘分析等功能集一体的工具,具体可落到LBS颗粒度去抓本地需求商家。还有一个特别功能是,如果商家上架的商品恰好是周边此前没人提供的,还会获得定向流量扶持。据了解,商品魔方已扶持700多万款商品,新品从上架到动销的时间缩短25%,已覆盖26个一级品类。

谈到商品就绕不开供应链,美团还推出了闪电仓商家专属的供应链服务平台——闪电帮帮,帮助商家迭代升级货盘,提高动销概率,并提供品质,合规,稳定的供应链能力。某闪电仓商家借助闪电帮帮推动货盘从白牌向品牌升级,新锐品牌与品牌货盘商品在相应品类实现30%以上的类目增长,不仅带动了交易额提升,也带来了更多新客。

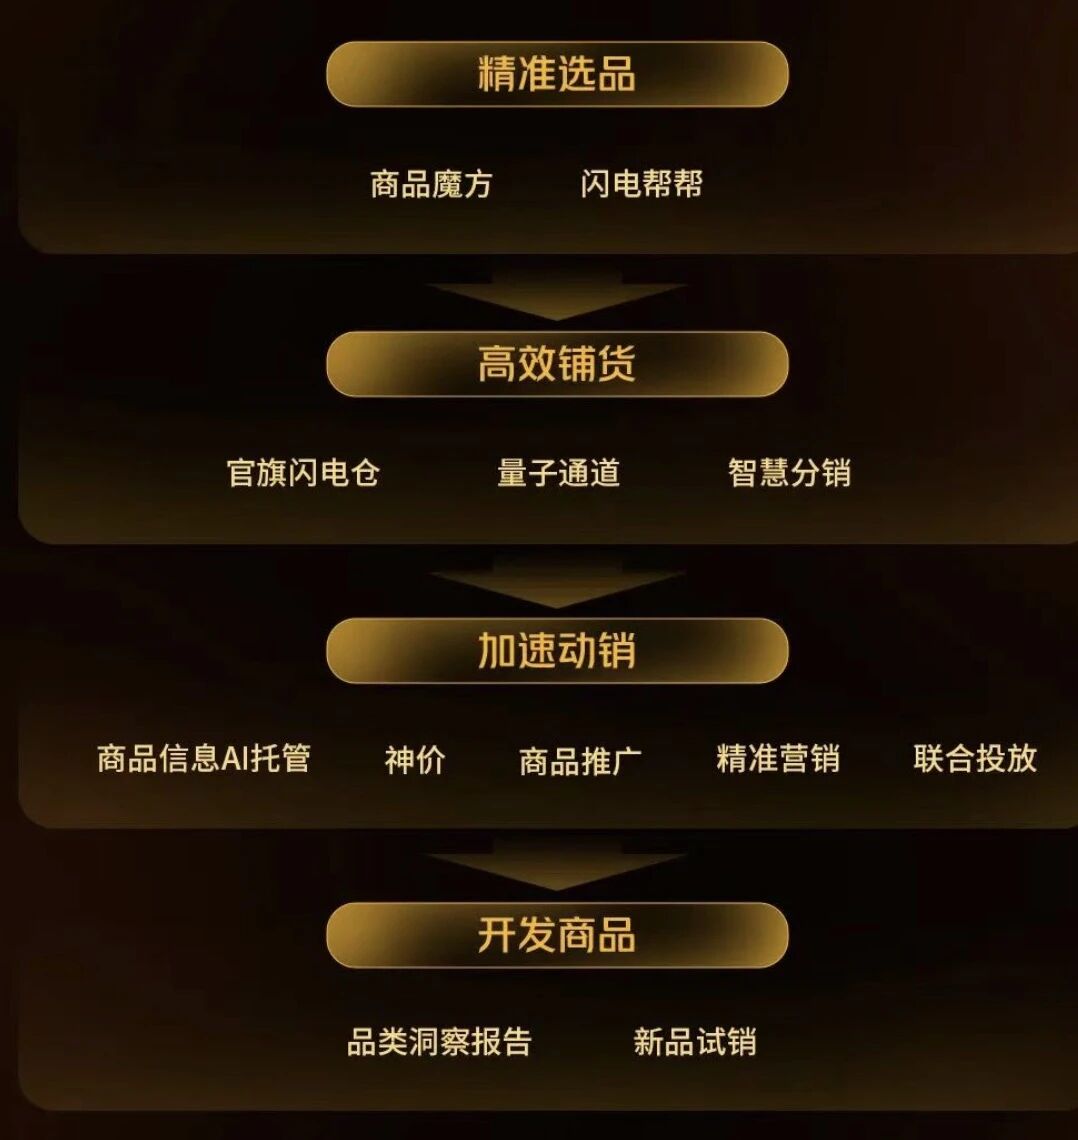
实际上,除了选品环节,在如何高效铺货、加速动销、商品开发等后续环节上,美团都有对应的工具和资源支持,9月22日,美团闪购发布“商品NEXT”计划,提出投入300亿支持资源,与品牌商、零售商共建“30分钟百万商品圈”,致力于把更多好商品搬到用户身边。

03

多元业态创新背后,即时零售开始回归商品本质

放到更大的坐标系里看,我们或许更能体会美团所传达的信号。即时零售进入商品时代,是与全球零售业“回归商品本质”的大趋势同频共振。

过去几年,全球零售业经历了一轮从渠道扩张到商品力回归的调整。无论是线下商超还是电商平台,都在重新把注意力放回“商品”本身。

沃尔玛在成都落地新一代门店模型,约3000平方米,聚焦鲜食与食品杂货,自有品牌Marketside成为差异化的重要抓手。沃尔玛中国CEO将这一调整概括为“以顾客为中心”的回归,沃尔玛全球CFO也在最新财报电话会上提出,会员“对品质、价值和新鲜感抱有极高期待”。

折扣零售巨头奥乐齐则在欧洲市场进一步收缩SKU,将自有品牌占比推至90%,并主动砍掉绝对小众的商品,把资源集中在“顾客真正需要的东西”上。

国内零售商也在同一条路径上加速。盒马将80%的新品开发聚焦用户核心需求,以健康食品与创新生鲜方案作为商品力的落点。山姆继续坚持“少而精”的选品策略,约4000款SKU覆盖家庭全场景,近期还基于会员“想吃又怕甜腻”的反馈反向定义产品形态,推出高纤杂粮月饼等产品。

电商同样如此。当低价竞争难以为继,品牌开始把重心转向商品创新和运营。从电商生长起来的新锐品牌,也在进入线下渠道,把商品推向离用户更近的地方。

以防晒衣被消费者熟知的蕉下,捕捉到即时零售场景需求后,ALL IN美团官旗闪电仓,从防晒品类延伸到差旅出行品类,内物品类成为官旗支柱,占比24%。同时反哺线下渠道,指导品牌进行品类结构调整,常规店新增内物品类铺货。五一期间,蕉下电商下滑20%,官旗闪电仓却增长36%。

目前,蕉下单仓交易突破15万/月,单仓效率是常规店4倍,官旗精准人群营销增量订单贡献占比超20%。由此可以看出,美团官旗闪电仓打开的不只是一个新渠道,还是一个可以重新组织货盘、重新触达人群的增量场。

除了单个品牌,也有更多行业集体涌入即时零售,在新渠道找增量。中国酒类流通协会预计,到2027年即时零售酒类市场规模有望突破千亿。但以哪种方式切入,是酒饮行业共同的课题。

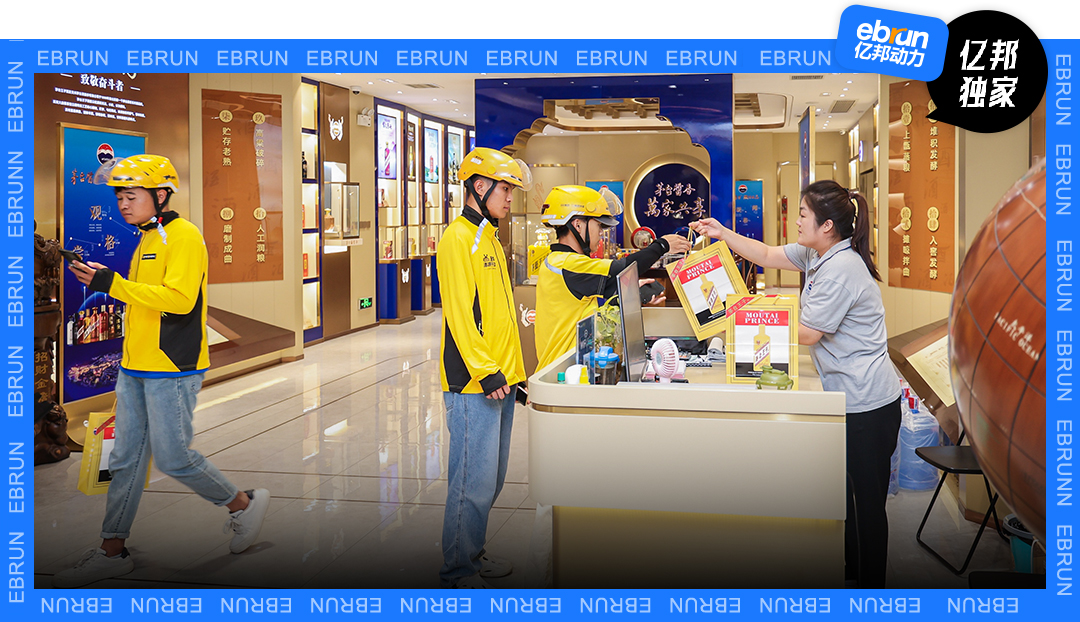
美团闪购开放多层次即时零售基建网络:名酒品牌可开官方旗舰店,实现门店数字化;经销商可入驻官方集合店“美团名酒行”,凭官方严选保真加速动销;轻资产零售商可开设酒饮闪电仓,精准触达年轻客群。亿邦动力了解到,未来三年,计划助力5个连锁品牌获超10亿即时零售增量,10个名酒品牌官旗销售破亿。

从宏观上零售巨头纷纷回归“商品力”,到微观上官旗闪电仓等模式的具体落地,都在验证一个零售业的百年铁律:渠道创新决定了商品的流通效率,而商品的品质与匹配度,才决定了渠道的终局。

即时零售的下半场,绝非简单的物理履约比拼。当“30分钟送达”变为基础门槛,竞争的终点必然回归到商品本身——谁能提供更丰富、更精准、更有品质的商品,谁就能抢先拿到下一轮增量。

本文首发于 亿邦动力 官方网站

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

即时零售是什么?有哪些特点?

即时零售是以LBS(本地地理位置)为基础,通过“店仓配”网络在30分钟至1小时内将商品送达用户的零售模式。2025年中国即时零售规模达11936亿元,用户规模超5亿,已成为零售业确定性增长赛道。其特点是消费决策发生在具体场景中,用户追求的是“在对的时刻拿到好的商品”。

即时零售市场规模有多大?

商务部流通产业促进中心数据显示,2025年我国即时零售规模达11936亿元,同比增长48.3%,预计2030年将达到2万亿元。目前全国闪电仓数量接近10万家,白天营业点位超百万个,夜间超35万个,用户规模增长至超5亿。

即时零售行业现在拼什么?

即时零售已从“仓店配时代”进入“商品时代”。当仓网成为基础设施,“跑什么货、供给什么商品”成为决定玩家生死存亡的分水岭。行业增长第一动力从开仓扩密度转向商品创新、扩容和提质,未来3年每个商圈将新增百万好商品。

品牌商如何通过即时零售获得增长?

品牌商需适应即时零售LBS场景逻辑,在对的场景里被对的人看到。例如水星家纺2025年11月入驻美团闪购,至2026年8月搜索转化率增长210%、销售额增长530%;蕉下入驻官旗闪电仓后单仓月交易突破15万元,效率是常规店4倍。

美团闪购“商品NEXT”计划是什么?

2026年9月22日,美团闪购发布“商品NEXT”计划,投入300亿支持资源,与品牌商、零售商共建“30分钟百万商品圈”。同时配套“商品魔方”选品工具,已扶持700多万款商品,新品上架到动销时间缩短25%,覆盖26个一级品类。

这么好看,分享一下?

朋友圈 分享

APP内打开

赞 +1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0