广告
加载中

从“地理名片”到“品牌矩阵”,贺兰山东麓葡萄酒的数字化破圈之路

亿邦动力 2026-09-21 23:26
亿邦动力 2026/09/21 23:26

邦小白快读

EN
全文速览

你可以从文中获取贺兰山东麓葡萄酒产业的核心信息,以及线上选购葡萄酒的实用参考。

1. 产业基本面信息:贺兰山东麓位于北纬38度黄金酿酒带,是全国最大的酿酒葡萄集中连片产区,截至2025年种植开发面积达60.6万亩,年灌装产量1.4亿瓶,占国产酒庄酒酿造总量近50%,产区品牌价值达350.86亿元,品质获国礼宴席级认可。

你还能掌握实用的葡萄酒消费参考。

1. 当前线上100-300元是葡萄酒主销价格带,300-600元中高端产品增速领先,选购时可重点关注标注宁夏产区、单一葡萄园,以及符合低度、易饮、果香浓郁等个人口感偏好的产品。

2. 如今葡萄酒已适配露营烧烤、家庭聚餐、火锅家宴等日常场景,无需局限于西餐搭配;目前贺兰山、木兰朵、西鸽等不同定位的酒庄均在天猫开设旗舰店,覆盖自饮、聚餐、收藏全需求,活动期还有政府消费券与平台补贴可享。

贺兰山东麓葡萄酒的数字化破圈实践,为地域特色品牌的成长提供了可参考的成熟经验。

1. 消费趋势层面:线上葡萄酒消费者正从“低价尝试型”转向“品质与产区认知型”,100-300元是主销价格带,300-600元中高端区间增速高于整体,用户搜索不再唯大牌论,产区属性、具体口感卖点的搜索热度显著提升,消费场景从特定礼赠向日常高频场景延伸。

2. 用户特征层面:25-40岁中青年是核心消费群体,女性消费者占比达46.11%,是低度易饮、高颜值产品线的核心增量,除东南沿海核心市场外,安徽、新疆等内陆省份消费增速分别达16.64%、33.46%,全国渗透空间充足。

可供借鉴的品牌建设路径清晰明确。

1. 渠道上可将主流电商平台作为数字化核心阵地,搭建全场景产品矩阵,实现线上用户沉淀反哺线下动销;营销上可通过场景破圈打破消费刻板印象,借助溯源内容、会员体系、文旅融合等方式沉淀用户,提升品牌溢价。

当前线上葡萄酒市场存在明确的结构性增长红利,政企平台三方联动的扶持政策为卖家提供了低门槛的发展机会。

1. 增长机会层面:100-300元是成熟主流价格带,300-600元中高端区间增速更高;产区词、具象口感卖点词搜索热度攀升,干白、甜型葡萄酒等细分品类需求上涨;露营、家宴、火锅聚餐等日常场景用酒需求快速释放,女性用户贡献近半消费,安徽、新疆等内陆省份消费增速分别达16.64%、33.46%,是尚待挖掘的核心增量。

你可直接借鉴经过验证的运营方法,对接可用的扶持资源。

1. 运营上可参考三类成熟成长路径:头部品牌靠全场景产品矩阵实现线上线下双向动销,新锐品牌靠场景破圈、头部直播间合作快速打造爆品,精品酒庄靠精细化用户运营、会员体系提升复购与溢价。

2. 平台端有AI商机中心的赛道指引,还有秒杀、百亿补贴等分层流量渠道支持,配合“新产地计划”配套的政府消费券、平台亿级资源补贴,可借力打造爆款、沉淀长期品牌资产。

线上葡萄酒消费的需求变化为生产端指明了产品设计与产能布局方向,电商数智化生态为工厂对接终端市场提供了可行路径。

1. 产品设计方向明确:价格带以100-300元主流价位为基本盘,兼顾布局300-600元中高端产品线;品类上除传统干红外,加大干白、甜型葡萄酒等细分品类开发,重点打磨低度、易饮、果香浓郁的口感,可配套高颜值包装适配女性用户偏好。

2. 场景适配要跳出“红酒配西餐”的固化思路,开发适配露营烧烤、家庭聚餐、火锅家宴等日常中餐场景的产品。

生产端可借力数字化能力提升经营效率。

1. 可对接电商平台AI商机中心精准捕捉终端需求,通过平台分层流量渠道集中打造爆款;依托平台溯源类内容IP,将自身风土优势、严苛生产标准转化为消费者信任点,也可结合文旅体验、会员权益设计高附加值产品,提升盈利空间。

线上葡萄酒市场的结构性变革与贺兰山东麓等核心产区的数字化转型需求,为服务商指明了服务方向与解决方案切入点。

1. 行业趋势层面:国产葡萄酒线上市场正处于复苏增长期,贺兰山东麓等核心产区近3年连续保持两位数增长,是带动国产葡萄酒线上增长的核心引擎,产区内大量酒庄存在数字化转型的专业服务需求。

服务商可围绕客户核心痛点搭建服务体系。

1. 当前酒庄类客户普遍存在难以精准捕捉消费需求、爆品打造能力不足、品牌信任传递效率低、用户复购率待提升的共性痛点。

2. 可配套提供数智化商机研判服务,帮助客户匹配细分赛道需求;提供场景化内容营销服务,通过溯源直播、场景化内容帮助品牌传递价值;提供用户精细化运营服务,帮助品牌搭建会员体系、沉淀高净值用户;还可帮助客户对接平台流量渠道、政府消费券等扶持资源,降低客户获客成本。

贺兰山东麓葡萄酒新产地的运营实践,为平台运营产业带、助力地域品牌破圈提供了可复制的范式,也明确了平台商家的核心需求。

1. 已被验证的平台有效做法包括:联合地方政府、产业园区发布产业研究报告、启动专项新产地扶持计划,整合平台资源系统性赋能产业带;通过AI商机中心为商家提供赛道方向指引,搭配秒杀、百亿补贴等分层渠道承接需求,帮助商家精准打造爆款。

平台运营与招商可顺着明确的方向优化。

1. 招商端可重点引入覆盖全价格带、全场景、全品类的葡萄酒商家,兼顾传统头部品牌、新锐国潮品牌、高端精品酒庄等多元主体;运营端要顺应消费升级趋势,重点扶持中高端产品线、产区属性明确、适配日常消费场景的产品,挖掘女性用户、内陆市场的增量空间,引导商家跳出单纯低价竞争的路径。

2. 可联动平台S+级内容IP打造沉浸式溯源内容,配合政府消费券、平台资源补贴培育标杆产地与爆款商品,帮助商家沉淀长效品牌资产。

贺兰山东麓葡萄酒的数字化破圈实践,折射出中国传统农业向高附加值品牌产业转型的新动向,具备典型研究价值。

1. 产业新变化:线上葡萄酒市场发生结构性变革,消费端从低价尝鲜、大牌导向转向品质导向、产区认知导向,消费场景从小众礼赠转向大众日常消费,女性群体、内陆市场成为核心增长来源,贺兰山东麓等核心产区近3年保持两位数增长,成为带动国产葡萄酒线上复苏的核心引擎。

政企商三方联动的产业发展新模式具备研究参考意义。

1. 当前贺兰山东麓探索出政府整合产业资源、电商平台输出数智化能力与流量基础设施、不同定位酒庄走差异化路径的联动模式,形成头部品牌全场景覆盖、新锐品牌场景破圈、精品酒庄深耕高净值用户的多元品牌矩阵。

2. 该模式证明地理标志型农产品要突破区域壁垒,不能仅依赖自然禀赋,需借力数字化渠道完成消费者认知教育、需求精准匹配、品牌资产沉淀,为其他农产品产区升级提供了可参考的样本。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

This article provides core insights into the wine industry on the eastern foothills of Helan Mountain, as well as practical guidance for buying wine online.

1. Industry fundamentals: Located at the 38th parallel north, the world’s golden winemaking belt, the eastern foothills of Helan Mountain is China’s largest contiguous wine grape growing region. As of 2025, it covers 606,000 mu (about 40,400 hectares) of planted area, with an annual bottled wine output of 140 million bottles, accounting for nearly 50% of China’s total domestic winery wine production. The region’s brand value stands at 35.086 billion yuan, and its wine quality has earned recognition at state banquet and official gifting levels.

The article also offers practical consumer tips for purchasing wine.

1. The 100–300 yuan price range is currently the mainstream segment for online wine sales, while the 300–600 yuan mid-to-premium segment is posting the fastest growth. When shopping, consumers are advised to prioritize products labeled as from the Ningxia production region or single vineyards, and select options that match personal taste preferences such as low alcohol content, easy drinkability, and rich fruit aromas.

2. Wine is now widely consumed in everyday scenarios including camping and barbecues, family gatherings, and hot pot meals, and is no longer limited to pairing with Western food. Wineries across different positioning tiers, such as Helan Mountain, Mulan Duo, and Xige, have opened official flagship stores on Tmall, covering all needs from casual drinking and group meals to collection. Consumers can also access government consumption vouchers and platform subsidies during promotional periods.

The digital market breakthrough of wine from the eastern foothills of Helan Mountain offers a mature, replicable reference for the growth of region-specific specialty brands.

1. Consumer trends: Online wine consumers are shifting from “low-price trial purchasers” to “quality and region-aware buyers.” The 100–300 yuan range is the core sales segment, while the 300–600 yuan mid-to-premium range outpaces overall category growth. Users no longer prioritize big international brands exclusively; search interest in regional origin attributes and specific taste selling points has risen significantly, and consumption scenarios are expanding from dedicated gifting to high-frequency everyday use.

2. User profile: Consumers aged 25–40 form the core customer base, and women, who account for 46.11% of buyers, are the key incremental demographic for low-alcohol, easy-drinking, and aesthetically packaged product lines. Beyond core markets in the southeast coastal region, inland provinces such as Anhui and Xinjiang are seeing consumption growth of 16.64% and 33.46% respectively, indicating substantial untapped national penetration potential.

A clear, actionable brand building pathway is available for reference.

1. On the channel front, brands can position mainstream e-commerce platforms as their core digital hub, build full-scenario product matrices, and leverage online user accumulation to drive offline sales turnover. On the marketing front, brands can break long-held consumption stereotypes through scenario-based outreach, and build user loyalty and brand premium through traceability content, membership systems, and integrated wine-tourism experiences.

The current online wine market presents clear structural growth dividends, with coordinated support from government, enterprises, and platforms offering sellers low-barrier development opportunities.

1. Growth opportunities: The 100–300 yuan range is the mature mainstream price segment, while the 300–600 yuan mid-to-premium tier delivers higher growth rates. Search volume for region-specific terms and concrete taste-related keywords is rising, alongside growing demand for niche categories such as dry white and sweet wine. Demand for wine for everyday scenarios including camping, family banquets, and hot pot gatherings is expanding rapidly; female users contribute nearly half of total consumption, while inland provinces such as Anhui and Xinjiang, which post 16.64% and 33.46% consumption growth respectively, represent key untapped incremental markets.

Sellers can directly apply proven operational strategies and access available support resources.

1. Operationally, three mature growth pathways are available for reference: leading brands drive two-way online-offline sales turnover via full-scenario product matrices; emerging brands quickly build hit products through scenario-based audience expansion and collaborations with top livestream channels; boutique wineries lift repurchase rates and price premiums through refined user operations and membership systems.

2. Platform support includes track guidance from the AI Opportunity Center, tiered traffic channels such as flash sales and the 10-billion-yuan subsidy program, plus government consumption vouchers and hundreds of millions of yuan in platform resource subsidies under the “New Origin Plan,” which sellers can leverage to build hit products and accumulate long-term brand equity.

Shifts in online wine demand provide clear guidance for product design and capacity planning for production players, while the digitally intelligent e-commerce ecosystem offers a viable path for factories to connect directly with end markets.

1. Product design priorities are well defined: take the 100–300 yuan mainstream price range as the core business base, while also developing product lines for the 300–600 yuan mid-to-premium segment. In terms of categories, in addition to traditional dry red wine, expand development of niche categories including dry white and sweet wine; prioritize taste profiles featuring low alcohol, easy drinkability, and rich fruit aromas, and offer aesthetically pleasing packaging to cater to female user preferences.

2. Scenario adaptation should move beyond the rigid assumption that “red wine only pairs with Western food,” with products developed to fit everyday Chinese dining scenarios such as camping and barbecues, family gatherings, and hot pot meals.

Production players can leverage digital capabilities to improve operational efficiency.

1. Factories can connect to e-commerce platforms’ AI Opportunity Centers to accurately capture end-market demand, and focus resources on building hit products via platforms’ tiered traffic channels. They can also leverage platform traceability content IP to translate their terroir advantages and strict production standards into consumer trust, as well as develop high-value-added products through integrated cultural tourism experiences and membership benefits to improve profit margins.

The structural transformation of the online wine market and the digital transformation demand of core production regions such as the eastern foothills of Helan Mountain clarify service directions and solution entry points for service providers.

1. Industry trends: China’s domestic online wine market is in a recovery and growth phase. Core producing regions including the eastern foothills of Helan Mountain have maintained double-digit growth for three consecutive years, serving as the core engine driving online growth for domestic wine, and a large number of wineries in these regions have unmet demand for professional digital transformation services.

Service providers can build their service systems around core client pain points.

1. Common pain points among winery clients include difficulty accurately capturing consumer demand, insufficient hit product development capabilities, low efficiency in communicating brand trust, and room for improvement in user repurchase rates.

2. Providers can deliver digital intelligence business opportunity research services to help clients match demand in niche market segments; provide scenario-based content marketing services to help brands communicate value through traceability livestreams and scenario-oriented content; offer refined user operation services to help brands build membership systems and retain high-net-worth users; and support clients in accessing platform traffic channels and support resources such as government consumption vouchers to reduce customer acquisition costs.

The operational practice of the Helan Mountain eastern foothills wine origin program provides a replicable model for platforms to operate industrial belts and support regional brands in breaking into mainstream markets, while also clarifying core merchant needs.

1. Proven effective platform practices include jointly releasing industry research reports with local governments and industrial parks, launching dedicated new origin support programs, and integrating platform resources to systematically empower industrial belts; providing track direction guidance for merchants via the AI Opportunity Center, paired with tiered channels such as flash sales and the 10-billion-yuan subsidy program to capture demand and help merchants accurately build hit products.

Clear directions are available to optimize platform operations and merchant recruitment.

1. On the recruitment front, platforms can focus on bringing in wine merchants covering full price ranges, scenarios, and categories, balancing diverse players including traditional leading brands, emerging domestic trend brands, and high-end boutique wineries. On the operation front, platforms should align with consumption upgrading trends, prioritize support for mid-to-premium product lines, products with clear regional origin attributes, and offerings tailored to everyday consumption scenarios, tap into incremental potential from female users and inland markets, and guide merchants to move away from pure low-price competition.

2. Platforms can collaborate with their S-tier content IP to create immersive traceability content, and cultivate benchmark origins and hit products in tandem with government consumption vouchers and platform resource subsidies, helping merchants build long-term brand equity.

The digital market breakthrough of wine from the eastern foothills of Helan Mountain reflects new trends in the transformation of China’s traditional agriculture toward high-value-added branded industries, holding strong representative research value.

1. New industry shifts: The online wine market is undergoing structural change. On the demand side, consumers are moving away from low-price trials and big-brand orientation toward quality-focused and region-aware purchasing; consumption scenarios are expanding from niche gifting to mass everyday consumption; female consumers and inland markets have become core growth drivers. Core producing regions such as the eastern foothills of Helan Mountain have maintained double-digit growth for three consecutive years, serving as the core engine driving the online recovery of domestic wine.

The new industry development model featuring tripartite collaboration between government, enterprises, and e-commerce platforms holds notable research reference value.

1. The eastern foothills of Helan Mountain has developed a collaborative model in which the government integrates industrial resources, e-commerce platforms provide digital intelligence capabilities and traffic infrastructure, and wineries of different positioning pursue differentiated growth paths, forming a diversified brand matrix where leading brands deliver full-scenario coverage, emerging brands break into new consumer scenarios, and boutique wineries focus on serving high-net-worth users.

2. This model demonstrates that for geographical indication agricultural products to break through regional barriers, they cannot rely solely on natural endowments; they must leverage digital channels to complete consumer awareness education, accurately match demand, and accumulate brand equity, providing a replicable reference for upgrading in other agricultural production regions.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

【亿邦原创】在北纬38度的“黄金纬度带”上,贺兰山阻挡风沙,黄河滋养沃土。宁夏贺兰山东麓凭其得天独厚的风土禀赋,已发展成为全国最大的酿酒葡萄集中连片产区。截至2025年,全区酿酒葡萄基地种植和开发面积达60.6万亩,年灌装产量1.4亿瓶,占据国产酒庄酒酿造总量的近50%。

尽管“贺兰山东麓葡萄酒”品牌价值已跃升至350.86亿元,并频繁亮相国礼宴席,但如何打破区域壁垒,将产区的影响力转化为直达终端的商业价值,实现从“好酒”到“好品牌”的跨越,始终是产区升级的核心课题。

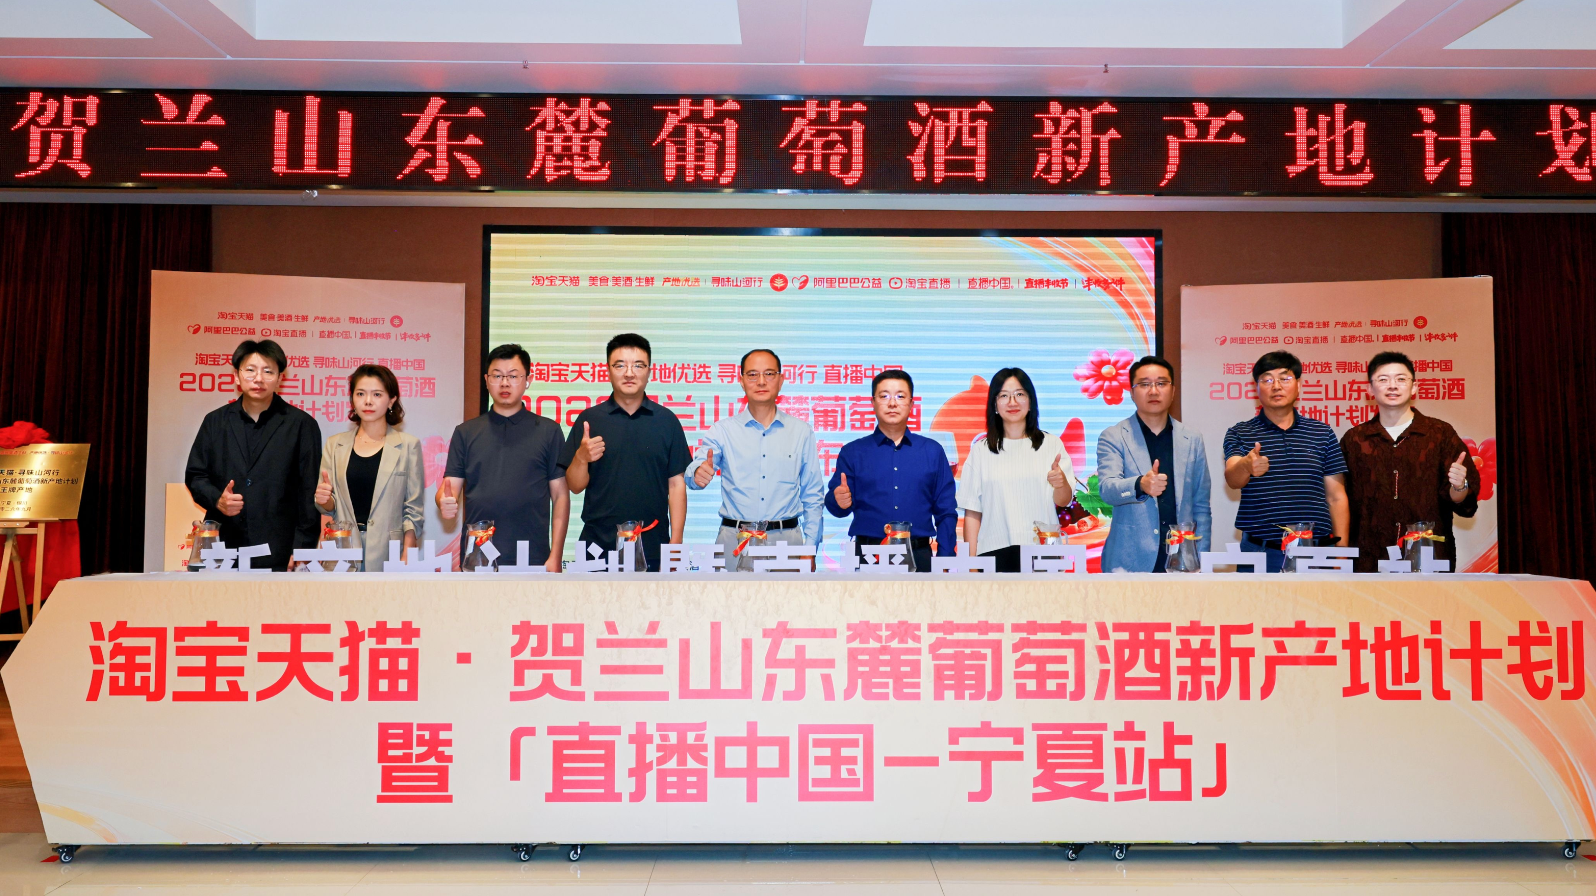
9月21日,淘宝天猫联合宁夏商务厅、贺兰山东麓葡萄酒产业园区管理委员会发布《淘宝天猫葡萄酒新产地报告》,并启动“贺兰山东麓葡萄酒新产地计划”。这一政企协力举措,标志着贺兰山东麓正借力电商平台的数智化生态,开启一场全方位的品牌重塑与市场破圈之旅。

01 线上葡萄酒市场的结构性变革

随着线上零售市场的深度渗透,葡萄酒消费者正加速从“低价尝试型”向“品质与产区认知型”转变。淘系平台数据显示,100—300元已成为主销价格带,300—600元中高端区间的增速更是高于整体,展现出强劲的消费升级拉动力。消费者在搜索时,不再单纯依赖大牌效应,像“宁夏红酒”“单一葡萄园”等产区词,以及“低度”“易饮”“果香浓郁”等口感卖点词的搜索热度显著攀升。

同时,饮用场景呈现高频化与多元化。“露营烧烤”“家庭聚餐”“晚宴用酒”等场景驱动购买,干白、甜型葡萄酒等细分品类异军突起,表明葡萄酒正在从“偶尔尝鲜的特定礼赠”走向“日常消费的品质生活”。

在用户画像上,25—40岁的中青年群体构成了线上消费的绝对主力(占比超45%)。值得注意的是,女性消费者占比升至46.11%,在低度易饮、高颜值包装的产品线中展现出极高爆发力,成为产业的新增量入口。从地域分布来看,虽然广东、浙江、上海等东南沿海省市占据核心消费份额,但安徽(增速16.64%)、新疆(增速33.46%)等内陆区域的强劲增长,映射出宁夏葡萄酒正在深耕一二线中产的同时,向更广阔的全国市场加速渗透。

在这一趋势下,贺兰山东麓产区凭借近3年连续保持两位数增长的稳健表现,已然成为推动整个国产葡萄酒线上复苏与增长的核心引擎。

02 从标杆实践到平台赋能的数智路径

贺兰山东麓产区如何实现从“风土优势”到“品牌红利”的转化?产区内部不同基因酒庄的成功实践,与淘系平台的生态资源形成了强有力的共振。

传统头部品牌“贺兰山葡萄酒”秉持“风土为根、电商为翼”战略,将天猫旗舰店作为数字化核心阵地。通过搭建覆盖自饮、聚餐、高端收藏的全场景产品矩阵,王牌单品“上鹤红干红”与“经典霞多丽干白”长期占据品类热销榜前列。2022-2026年品牌连续多年实现双位数增长,在线上沉淀高粘性精准用户的同时,反向拉动全国数百家线下商超连锁动销,实现了双向共振。

新锐国潮品牌“木兰朵”则以“东方美学+国际品质+电商爆发力”为破局点。木兰朵通过携手顶级直播间、打破“红酒配西餐”的刻板印象,将产品无缝融入火锅、家宴等中餐场景。爆品M218干红曾创下两周下单近10万瓶的纪录,店铺仅凭10款在售商品即跻身天猫葡萄酒店铺榜前六,示范了年轻品牌短时间内从0到1爆发式增长的路径。

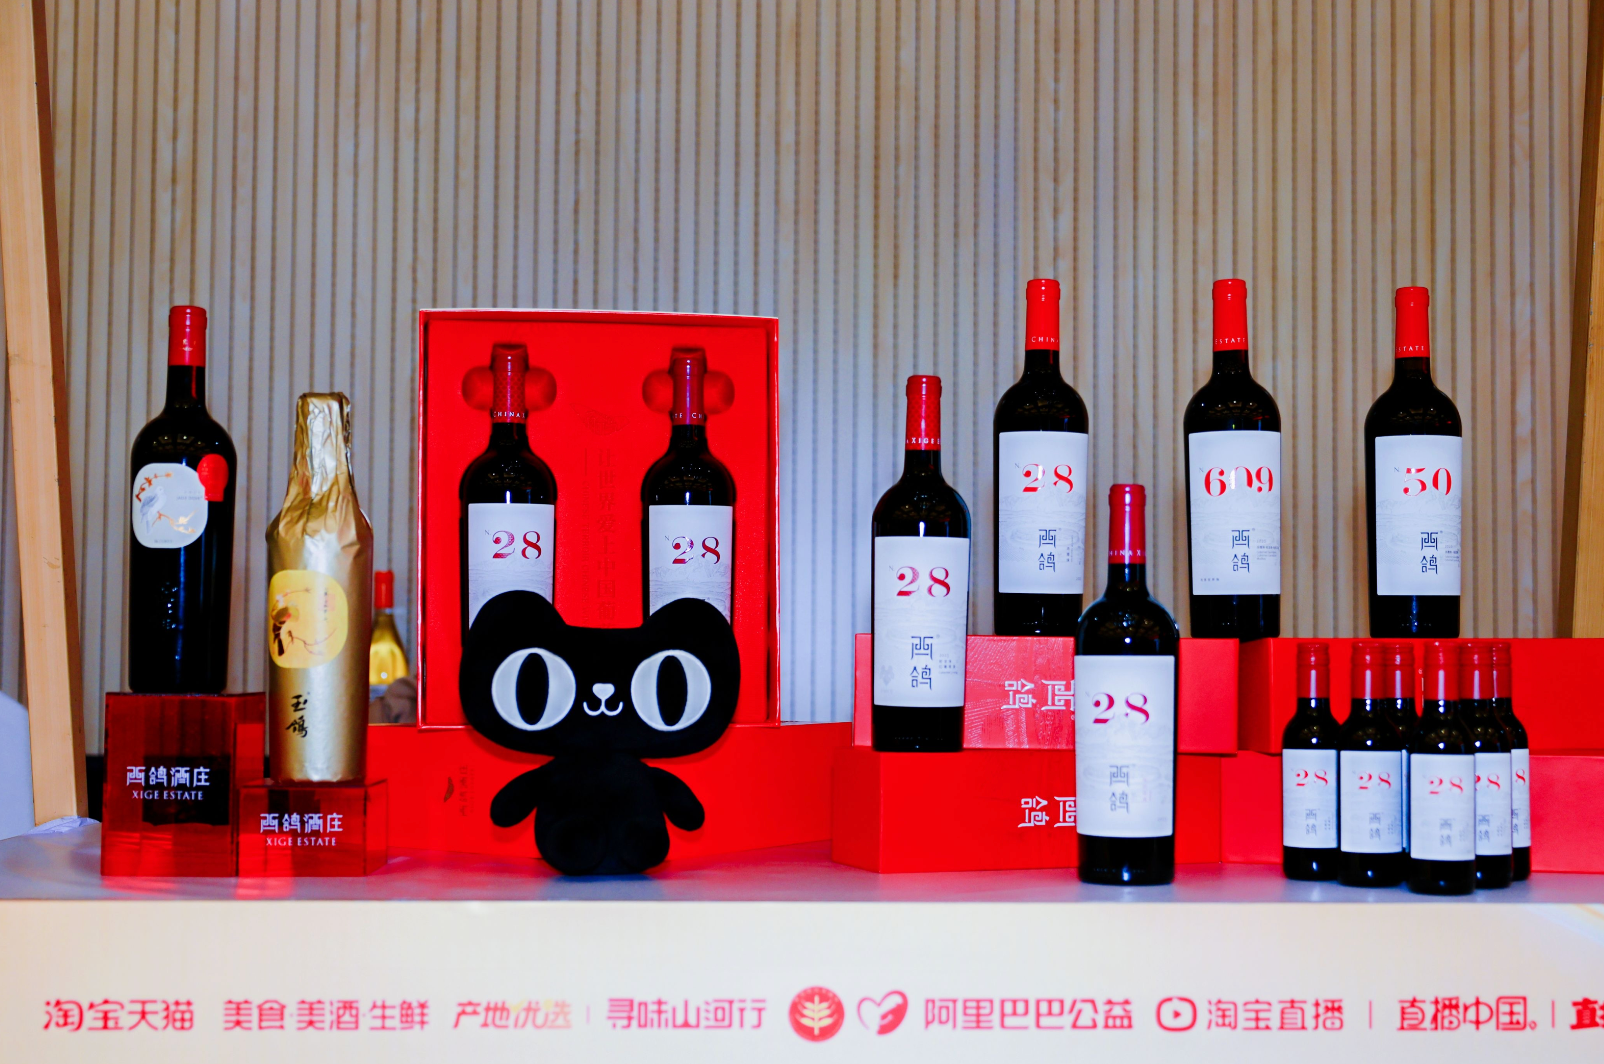
世界级精品酒庄“西鸽酒庄”坚持“真实葡萄园、真实年份”与严苛的“3126法则”,将高品质国际名庄路线与天猫精细化用户运营相融。通过打造会员体系与文旅体验产品,积累了大量高净值粉丝,其复购率长期高于行业平均水平,实现了高品牌溢价与商业规模的双重突破。

品牌的破圈不仅依赖酒庄自身的探索,更离不开淘系平台系统性的基础设施支撑。平台通过“AI商机中心”指引赛道方向,结合淘宝秒杀、百亿补贴等渠道分层承接,帮助酒庄精准匹配消费需求、集中打造爆款。

9月21日,淘宝直播S+级内容IP“直播中国”走进贺兰山东麓,打造“山河丰收·中国葡萄酒”专场。通过“酒庄走读+实地溯源+专家庄主夜话”的沉浸式内容,直观解构一瓶好酒从葡萄园到餐桌的全过程,将产区风土转化为消费者可感知的品牌信任。结合政府消费券发放与平台亿级资源补贴,淘系平台正通过“新产地计划”打造破亿级新产地与破百万爆款,推动产区品牌沉淀长效资产。

葡萄酒是风土的艺术,也是时间的产物。宁夏贺兰山东麓用数十年的耕耘造就了世界级的风土品质;而淘宝天猫等数字化平台的深入介入,则为这份风土插上了效率与品牌的翅膀。

从《淘宝天猫葡萄酒新产地报告》的发布到“新产地计划”的落地,政企商三方的深度联动,正在重新定义国产葡萄酒的价值链条。这不仅是一次产区的商业破圈,也是一场中国传统农业向现代高附加值品牌产业蜕变的深刻变革。

一瓶好酒的全国之旅,才刚刚开启。

本文首发于 亿邦动力 官方网站

亿邦持续追踪报道该情报,如想了解更多与本文相关信息,请扫码关注作者微信。

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

贺兰山东麓葡萄酒产区在国产葡萄酒行业处于什么地位?

截至2025年,贺兰山东麓是全国最大的酿酒葡萄集中连片产区,种植开发面积达60.6万亩,年灌装产量1.4亿瓶,占国产酒庄酒酿造总量近50%,品牌价值达350.86亿元,是带动国产葡萄酒线上复苏增长的核心引擎。

当前国内线上葡萄酒消费有哪些新趋势?

线上葡萄酒消费者正从“低价尝试型”转向“品质与产区认知型”,100-300元是主销价格带,300-600元中高端区间增速领先;25-40岁群体是消费主力,女性消费者占比达46.11%,消费场景从特定礼赠向露营、家宴等日常多元场景延伸。

贺兰山东麓葡萄酒通过哪些数字化路径实现品牌破圈?

一方面产区内不同定位的酒庄依托天猫等电商阵地,搭建全场景产品矩阵、对接头部直播渠道、精细化运营用户打造爆款;另一方面政企联动淘宝天猫启动葡萄酒新产地计划,借助平台AI商机匹配、溯源直播、流量与消费券补贴等资源,实现品牌长效增长与全国市场渗透。

这么好看,分享一下?

朋友圈 分享

APP内打开

+1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0