广告
加载中

携程Q2营收157亿 反垄断罚单致账面转亏 国际业务成亮点

姜琪 2026-09-16 15:37
姜琪 2026/09/16 15:37

邦小白快读

EN
全文速览

携程2026年第二季度的核心经营信息、旅游市场动向,是大家了解旅游行业变化、规划出行的重要参考。

可关注平台经营基本面,判断旅游服务供给稳定性。1.当季携程净营收157亿元,因52亿元反垄断罚单账面净亏损24亿元,剔除罚单影响实际净利润27亿元,截至季末平台现金储备超1005亿元,整体经营底盘稳健。2.分业务看住宿预订稳中有增,商旅、节假日度假业务增速较快,交通票务受高能源价格等宏观因素影响环比有所下滑。

可把握旅游市场新动向,优化出行规划。1.国际业务收入同比增超50%,入境游保持高双位数增长,平台上承接入境订单的酒店达11.8万家,三线及以下城市相关酒店增速更快,国际客源正向低线目的地渗透,小众涉外目的地的旅游配套正在完善。2.平台正推进全旅程AI服务覆盖,后续出行全流程的智能服务体验有望持续升级。

携程Q2披露的业绩表现、消费趋势与战略方向,可为旅游相关品牌的经营布局提供参考。

可依托消费趋势找准产品布局方向。1.国内市场中商旅管理业务同比增11%、环比增12%,为增速最高板块;节假日需求带动旅游度假业务增8%,住宿预订保持稳健增长,交通票务受高能源价格、地缘波动影响有所承压。2.入境游、国际业务是核心增量赛道,国际平台收入增超50%,入境游保持高双位数增长,国际客源正从一线门户向三线及以下城市渗透,低线城市涉外旅游配套增速领先。

可对齐平台战略优化自身经营动作。1.携程当前聚焦全球化加高质量的G2战略,正推进全旅程自研AI能力落地,持续拓展旅游加生活方式类产品版图。2.行业合规框架正持续更新,平台已主动结合最新要求做运营调整,品牌需同步做好合规适配,避免经营风险。

携程Q2财报透露出的市场机会、规则变化、风险提示,是平台内旅游类卖家调整经营策略的重要参考。

可瞄准高增长赛道捕捉增量机会。1.高增长业务包括商旅管理服务、节假日度假产品、入境游相关服务,目前平台承接入境订单的酒店达11.8万家,三线及以下城市相关酒店增速远超平台整体,低线城市涉外旅游服务存在明显缺口;国际板块中亚太是核心增量来源,欧美市场在低基数下增速更快,跨境旅游服务机会充足。2.平台正拓展旅游加生活方式类产品版图,相关品类卖家可积极对接入驻。

需做好风险防控与合规适配。1.高能源价格、地缘波动等宏观因素对交通票务类业务冲击明显,相关品类卖家需提前做好经营预案。2.行业合规框架持续更新,平台已主动调整运营规则,卖家需同步规范经营,规避违规风险。

可从携程披露的旅游行业发展动向中,挖掘相关配套产品的生产机会,借鉴数字化转型经验。

可围绕新的旅游消费需求优化产品设计与生产布局。1.入境游持续高增,国际客源正向三线及以下城市渗透,平台承接入境订单的酒店规模不断扩大,针对入境游客的酒店配套用品、本地化旅游文创、目的地体验周边存在明确增量,产品设计可兼顾多国籍游客的使用习惯与文化偏好。2.商旅管理业务增速领跑全板块,商务出行场景的便携差旅用品、高端商旅配套需求稳步上涨;节假日带动度假旅游增长,休闲度假类旅游装备也有稳定需求支撑。

可借鉴平台经验推进数字化升级。携程正通过自研AI覆盖旅客全旅程环节,落地全球化高质量战略,旅游供应链工厂也可借助数字化、AI能力打通供需匹配链路,提升对跨境、下沉市场需求的响应效率。

可从携程Q2业绩动向中把握旅游行业趋势、技术方向与客户痛点,找准服务切入点。

可锚定行业痛点与增长赛道打造适配服务方案。1.核心增长机会集中在跨境旅游、入境游、商旅管理板块,目前入境游供给正从一线向低线城市渗透,大量低线城市酒店、旅游商家存在涉外能力搭建、跨境客源对接、多语种服务配套的需求;高能源价格、地缘波动给交通票务类业务带来经营压力,相关成本优化、风险对冲类服务有明确市场空间。2.行业合规要求持续更新,平台及商家都有合规调整需求,可针对性提供合规咨询、流程优化类服务。

可跟进技术趋势升级服务能力。携程正推进自研AI覆盖旅客全旅程环节,服务商可围绕AI行程规划、智能客服、场景智能匹配等方向打造技术服务方案,对接行业数字化升级需求。

可从携程Q2的经营表现、战略布局与风险应对中,获取平台经营、增长拓展、风险防控的参考经验。

可参考头部平台逻辑挖掘新增长曲线。1.国内业务承压时全球化是核心增长极,携程国际平台收入同比增超50%,入境游保持高双位数增长,亚太为核心增量市场,欧美市场在低基数下增速更快;可重点完善入境游供给体系,尤其关注三线及以下城市的涉外服务覆盖,承接国际客源下沉的需求。2.业务结构上可重点发力高增速板块,针对商旅管理、节假日度假等需求旺盛的赛道,完善服务体系、丰富产品供给。

需做好合规运营与风险防控。1.要警惕高能源价格、地缘波动等宏观因素对交通票务等业务的冲击,提前制定应对预案;高度重视反垄断等合规要求,携程本次因52亿元反垄断罚单导致账面亏损,需主动适配行业合规框架调整平台规则。2.可推进自研AI在全用户旅程的落地,拓展旅游加生活方式类产品,提升平台服务厚度。

携程Q2的业绩数据、经营事件与战略布局,为在线旅游产业研究、平台监管研究提供了典型的现实样本。

可基于财报数据梳理产业新动向与新问题。1.产业增长结构出现明显变化,国内业务受高能源价格、地缘波动等宏观因素承压,国际业务成为核心增长极,携程国际平台收入增超50%,入境游保持高双位数增长,国际客源从一线向低线城市渗透,平台全球化布局的价值持续显现;分业务看商旅管理增速领跑,节假日是度假业务核心支撑,交通票务受外部因素影响明显。2.合规层面,52亿元反垄断罚单导致携程当季账面转亏,一般及行政费用同比激增477%,反映出平台适配最新合规框架的紧迫性。

可跟踪研究头部平台的商业模式创新。携程当前明确全球化加高质量的G2战略,通过自研AI覆盖全旅客旅程、拓展旅游加生活方式生态的路径推进战略落地,其经营效果可为产业研究、行业监管政策优化提供实证参考。

返回默认

声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

Ctrip’s Q2 2026 core operating metrics and broader travel market trends serve as a useful reference for understanding industry shifts and planning personal travel.

Users can assess the platform’s operational fundamentals to gauge the stability of travel service supply. 1. Ctrip reported quarterly net revenue of 15.7 billion yuan. While a 5.2 billion yuan anti-monopoly fine dragged the company to a reported net loss of 2.4 billion yuan, adjusted net profit excluding the fine came in at 2.7 billion yuan. As of quarter-end, its cash reserves exceeded 100.5 billion yuan, pointing to a solid overall operating foundation. 2. By segment, accommodation booking recorded steady growth, corporate travel and holiday vacation businesses posted faster expansion, while transportation ticketing declined quarter-over-quarter due to macro headwinds including high energy prices.

Users can also track emerging travel market trends to optimize trip planning. 1. International business revenue rose more than 50% year-over-year, and inbound tourism maintained high double-digit growth. The number of hotels on the platform accepting inbound orders reached 118,000, with faster growth among properties in third-tier and lower-tier cities. International travelers are increasingly visiting lower-tier destinations, and tourism infrastructure in niche outbound-connected locations continues to improve. 2. The platform is rolling out AI-powered services across the entire travel journey, which is expected to continuously upgrade smart travel experiences for end users going forward.

Ctrip’s Q2 earnings, consumer trends, and strategic direction provide a useful reference for travel-related brands to refine their operational planning.

Brands can align product development with shifting consumption trends. 1. In the domestic market, corporate travel management was the fastest-growing segment, rising 11% year-over-year and 12% quarter-over-quarter. Holiday demand drove an 8% increase in the vacation business, accommodation booking maintained steady growth, and transportation ticketing came under pressure from high energy prices and geopolitical volatility. 2. Inbound tourism and international business represent core growth tracks: international platform revenue grew more than 50%, inbound tourism maintained high double-digit growth, international travelers are expanding beyond first-tier gateway cities into third-tier and lower-tier markets, and foreign-facing tourism infrastructure in lower-tier cities is growing faster than the platform average.

Brands should align operational moves with the platform’s strategic priorities. 1. Ctrip is currently focused on its “Globalization + High Quality” (G2) strategy, rolling out self-developed, end-to-end AI travel services, and expanding its portfolio of travel-and-lifestyle products. 2. Industry compliance frameworks continue to evolve. As the platform proactively adjusts operations to meet latest requirements, brands need to adapt their own compliance practices to avoid operational risks.

Ctrip’s Q2 earnings shed light on market opportunities, rule changes, and risk alerts, offering critical guidance for travel sellers operating on the platform.

Sellers can target high-growth tracks to capture incremental opportunities. 1. High-growth segments include corporate travel management services, holiday vacation products, and inbound travel-related services. The number of hotels on the platform accepting inbound orders has reached 118,000, with properties in third-tier and lower-tier cities growing far faster than the platform average, indicating a clear supply gap for foreign-facing travel services in lower-tier markets. Internationally, Asia-Pacific is the core source of incremental growth, while Europe and North America are posting faster growth off a low base, creating broad opportunities for cross-border travel services. 2. The platform is expanding its travel-and-lifestyle product portfolio, and sellers in related categories are well positioned to pursue onboarding and partnership opportunities.

Sellers need to prioritize risk control and compliance adaptation. 1. Macro factors including high energy prices and geopolitical volatility are creating notable pressure on transportation ticketing businesses, and sellers in this category should prepare contingency plans in advance. 2. As industry compliance frameworks continue to update and the platform proactively adjusts operating rules, sellers must standardize operations in lockstep to avoid violation risks.

Ctrip’s disclosed travel industry trends can help supply chain manufacturers identify production opportunities for supporting products and draw lessons for digital transformation.

Manufacturers can optimize product design and production planning around emerging travel consumption demand. 1. Inbound tourism continues to grow rapidly, with international travelers increasingly penetrating third-tier and lower-tier cities, and the scale of hotels accepting inbound orders on the platform expanding steadily. This creates clear incremental demand for hotel amenities for inbound guests, localized travel cultural and creative products, and destination experience merchandise; product design should account for usage habits and cultural preferences of travelers from diverse national backgrounds. 2. Corporate travel management is the fastest-growing segment, driving steadily rising demand for portable business travel supplies and premium corporate travel supporting products. Holiday demand is also fueling vacation travel growth, supporting stable demand for leisure and vacation travel gear.

Manufacturers can draw on the platform’s experience to advance digital upgrades. Ctrip is deploying self-developed AI across the full passenger journey to deliver on its global high-quality strategy. Travel supply chain factories can similarly leverage digital and AI capabilities to streamline supply-demand matching and improve response efficiency to demand from cross-border and lower-tier markets.

Ctrip’s Q2 performance offers insight into travel industry trends, technology directions, and customer pain points, helping service providers identify high-value market entry points.

Service providers can build targeted solutions around industry pain points and high-growth tracks. 1. Core growth opportunities are concentrated in cross-border travel, inbound tourism, and corporate travel management. As inbound travel supply expands from first-tier to lower-tier cities, large numbers of hotels and travel merchants in lower-tier markets have clear demand for foreign-facing operational capability building, cross-border customer acquisition, and multilingual service support. High energy prices and geopolitical volatility are putting operating pressure on transportation ticketing businesses, creating clear market demand for cost optimization and risk hedging services. 2. As industry compliance requirements continue to evolve, both platforms and merchants face compliance adjustment needs, creating demand for targeted compliance consulting and process optimization services.

Service providers should follow technology trends to upgrade service capabilities. Ctrip is rolling out self-developed AI across the full travel journey, and service providers can develop technical solutions around AI trip planning, intelligent customer service, and scenario-based smart matching to support the industry’s digital upgrade needs.

Ctrip’s Q2 operating performance, strategic layout, and risk response practices offer actionable lessons for peer platforms on operations, growth expansion, and risk control.

Platforms can draw on the leading player’s playbook to identify new growth curves. 1. Globalization acts as a core growth driver when domestic business faces pressure: Ctrip’s international platform revenue rose more than 50% year-over-year, inbound tourism maintained high double-digit growth, Asia-Pacific served as the core incremental market, and Europe and North America posted faster growth off a low base. Platforms should prioritize improving the inbound travel supply system, with particular focus on expanding foreign-facing service coverage in third-tier and lower-tier cities to capture demand from international travelers traveling to non-gateway destinations. 2. On business structure, platforms can prioritize high-growth segments, improving service systems and enriching product supply for high-demand tracks such as corporate travel management and holiday vacations.

Platforms need to prioritize compliant operations and risk prevention. 1. They should guard against the impact of macro factors including high energy prices and geopolitical volatility on businesses such as transportation ticketing, and develop response plans in advance. They should also attach high importance to compliance requirements such as anti-monopoly rules — as illustrated by Ctrip’s 5.2 billion yuan anti-monopoly fine which led to a reported quarterly loss — and proactively adapt platform rules to align with evolving industry compliance frameworks. 2. Platforms can advance the deployment of self-developed AI across the full user journey and expand travel-and-lifestyle product offerings to enhance overall service depth.

Ctrip’s Q2 financial metrics, operating events, and strategic layout provide a typical real-world sample for research on the online travel industry and platform regulation.

Researchers can map new industry trends and emerging issues based on the earnings data. 1. The industry’s growth structure has shifted notably: domestic business faces pressure from macro factors including high energy prices and geopolitical volatility, while international business has become the core growth driver. Ctrip’s international platform revenue rose more than 50%, inbound tourism maintained high double-digit growth, international travelers are expanding from first-tier to lower-tier cities, and the value of the platform’s global layout continues to materialize. By segment, corporate travel management leads growth, holiday demand is the core support for the vacation business, and transportation ticketing is significantly affected by external factors. 2. On the compliance front, the 5.2 billion yuan anti-monopoly fine pushed Ctrip to a reported quarterly loss, with general and administrative expenses surging 477% year-over-year, highlighting the urgency for platforms to adapt to the latest compliance frameworks.

Researchers can track the leading platform’s business model innovation. Ctrip has clearly defined its “Globalization + High Quality” (G2) strategy, which it is executing by deploying self-developed AI across the full passenger journey and expanding its travel-and-lifestyle ecosystem. The operating outcomes of this strategy can provide empirical reference for industry research and the optimization of sector regulatory policies.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

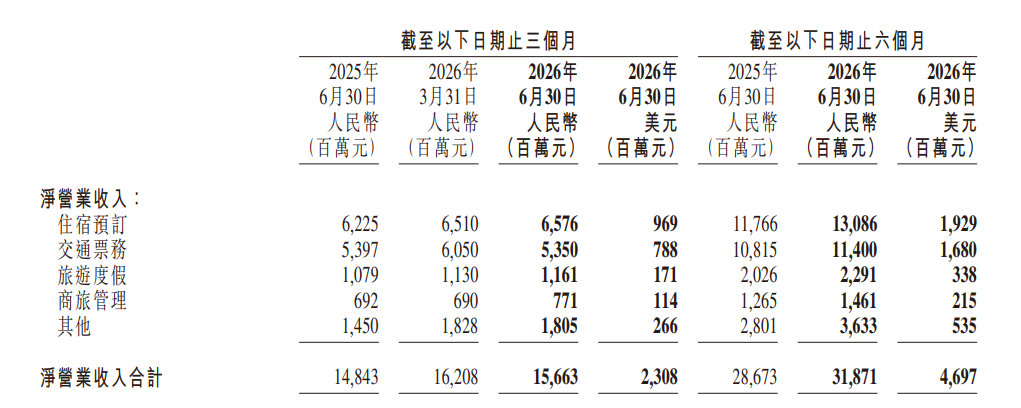
【亿邦原创】9月16日,携程集团发布2026第二季度及上半年业绩公告。第二季度,携程净营业收入157亿元,同比增长6%,环比下降3%。公司解释称,环比下滑主要受高能源价格和地缘政治波动等宏观因素影响,同时公司就行业标准与合规框架的最新变化主动进行了运营调整。

分业务看,二季度住宿预订收入66亿元,同比增长6%,环比增长1%。值得注意的是,这一增长已被国家市场监督管理总局的反垄断处罚冲减收入所部分抵消。交通票务收入54亿元,同比下降1%,环比下降12%,成为四大业务中唯一同比下滑的板块,同样受宏观因素影响。旅游度假收入12亿元,同比增长8%,节假日需求支撑明显。商旅管理收入7.71亿元,同比增长11%,环比增长12%,增速领跑各业务线。

因SAMR反垄断处罚52亿元,携程一般及行政费用同比激增477%,占净营业收入比重升至40%。受此影响,第二季度净亏损24亿元,而去年同期为净利润49亿元。若剔除罚单影响,净利润为27亿元,一般及行政费用占比回落至7%。

国内业务承压之际,全球化战略的厚度开始显现。

第二季度,携程国际平台收入同比增长超过50%,入境游收入在较高基数上继续保持高双位数增长。亚太是主要增量来源,欧洲与美洲市场则在较小基数上跑出更快增速。

入境游的暖意已传导至供给侧。上半年,携程平台承接入境订单的酒店达11.8万家,三线及以下城市承接入境订单的酒店数量增速显著高于平台整体水平。国际客源不再局限于一线门户,开始向更广阔的市场渗透。

携程董事会执行主席梁建章表示,公司战略重心始终明确,即全球化与高质量,也就是G2。他提到,公司正持续推进自研AI能力,覆盖旅客旅程的每一个环节,以加速G2战略落地。首席执行官孙洁则强调,入境旅游与全球对全球旅游持续发挥结构性成长动能,公司将持续拓展产品版图,纳入更多旅游与生活方式体验。

截至2026年6月30日,携程现金及现金等价物、受限制现金、短期投资及持有至到期的定期存款和理财产品余额为1005亿元。

亿邦持续追踪报道该情报,如想了解更多与本文相关信息,请扫码关注作者微信。

本文首发于 亿邦动力 官方网站

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

携程2026年第二季度出现净亏损的主要原因是什么?

携程2026年第二季度净亏损24亿元,主要受国家市场监督管理总局开出的52亿元反垄断罚单影响,当期一般及行政费用同比激增477%,占净营收比重升至40%;剔除罚单影响后,当季净利润为27亿元。

携程2026年第二季度国际业务增长表现如何?

携程2026年第二季度国际平台收入同比增长超50%,入境游收入在较高基数上保持高双位数增长;亚太区域是主要增量来源,欧洲、美洲市场在较小基数上实现了更快增速。

携程当前的核心发展战略是什么?

携程当前核心战略为全球化与高质量(即G2战略),将持续推进自研AI能力覆盖旅客旅程全环节,拓展旅游与生活方式体验类产品,挖掘入境游、全球对全球旅游的结构性成长动能。

2026年上半年携程平台入境游供给有哪些变化?

2026年上半年携程平台承接入境订单的酒店达11.8万家,三线及以下城市承接入境订单的酒店数量增速显著高于平台整体水平,国际客源正从一线门户向更广阔的低线市场渗透。

这么好看,分享一下?

朋友圈 分享

APP内打开

+1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0