广告
加载中

AI时代跨境电商服务商走向何方?三大核心任务指明方向

亿邦智库 2026-09-24 10:27
亿邦智库 2026/09/24 10:27

邦小白快读

EN
全文速览

AI时代跨境电商服务商正在经历深刻转型,报告提出三大核心任务,帮助理解行业未来走向。

1. 向AI原生企业进化:传统企业是先有业务再配AI,AI原生企业则将AI嵌入战略底层,从组织、数据、产品、交付四个层面全面重构,实现由AI驱动业务增长。

2. 向AI增长合伙人升级:服务商不再按工时或项目收费,而是转向按结果计费的RaaS模式,与卖家共同承担经营指标,比如与GMV、利润、转化率挂钩。目前已有21.4%服务商尝试这种模式,但62.1%仍认同趋势却未落地。

3. 融入全球化智能服务协同网络:电商网站成为合规数据、流量和技术的核心枢纽,83.5%服务商认为电商网站与AI服务商协同模式将成主流。服务商需向上对接平台、向下封装专业智能体、横向多智能体协同,构建开放共赢的生态。

AI时代服务商转型将直接影响品牌营销和渠道建设方式,品牌商可以从报告中找到借助AI提升增长的思路。

1. 品牌营销与用户行为观察:AI原生服务商通过数据驱动和智能运营闭环,能更精准洞察用户行为,帮助品牌把分散的业务数据转化为可持续迭代的数据资产,从而优化选品、营销和客户服务,提升市场响应速度。

2. 产品研发与解决方案升级:服务商正从做得更快升级为设计得更好,将行业知识和经验注入AI产品。品牌商可以借助这类专业方案,获得更贴合业务场景的智能工具,提高产品研发与营销决策的匹配度。

3. 品牌渠道与协同网络:电商网站成为AI服务商的关键枢纽,品牌商可通过深度嵌入协同网络,获得合规稳定的流量、培训和技术支持。服务商之间多智能体动态组队,能响应从选品到履约的全场景需求,帮助品牌在平台上实现更高效的增长闭环。

AI时代服务商模式的变化直接影响卖家的成本、风险和增长机会,报告揭示了几个关键信号。

1. 增长机会与合作模式:服务商正从完成单项任务转向共同承担经营指标,卖家可以从购买工具转向购买效果。若服务商将收费与GMV、利润、转化率挂钩,卖家能降低试错成本,获得更确定的增长结果。

2. 风险提示与应对:目前虽然有21.4%服务商尝试结果付费,但62.1%认同趋势却未找到合适的定价模型。卖家需要警惕概念炒作,应考察服务商是否有能力定义增长基线、追踪AI动作并建立归因模型,否则结果付费难以落地。

3. 可学习点与协同红利:主流趋势是电商网站与AI服务商协同,83.5%服务商认为这一模式将成为主流。卖家可以优先选择深度嵌入电商网站的服务商,借助合规数据、流量和技术支持,提升运营效率;同时关注服务商之间多智能体协同带来的全场景服务能力,灵活组队满足复杂需求。

报告虽面向服务商,但其中关于AI原生企业和数据闭环的内容,对工厂推进数字化和电商转型有重要启示。

1. 产品生产和设计需求:AI原生服务商通过数据驱动和智能运营,能更准确预测市场需求和用户偏好。工厂可以借助这类服务商的数据反馈,优化产品设计与生产规划,避免盲目生产,提升新品成功率。

2. 商业机会与合作方式:服务商向AI增长合伙人升级,收费与结果挂钩,这可能意味着工厂与AI服务商合作时,能以更低风险获得选品、营销和履约等方面的专业支持。选择有行业积累的服务商,能更快响应市场变化。

3. 数字化与电商启示:报告强调数据治理和流程重构是AI价值释放的基础。工厂在推进数字化时,应把分散的业务数据统一为可迭代的数据资产,形成数据到模型再到业务的循环提升机制。同时,未来电商网站与AI服务商协同网络将成为主流,工厂可提前对接这类枢纽,获取合规的流量和技术支持。

服务商应关注报告提出的三大长期任务,它们共同定义了从传统服务商向AI服务商进化的路径。

1. 向AI原生企业进化:核心是从业务配AI转向AI生业务。落地路径包括组织上构建全员可用AI的敏捷协作体系,数据上形成数据到模型再到业务的循环提升,产品上把行业经验注入AI工具形成差异化,交付上从单点交付转向增长闭环。

2. 向AI增长合伙人升级:服务商角色从完成单项任务转为共同承担经营指标。能力评价从功能是否实现转向是否带来可量化业务结果;收费方式向按结果计费的RaaS演进。报告调研显示21.4%服务商已尝试与GMV、利润等指标挂钩,但62.1%仍未找到合适的落地方式,这是巨大的创新空间。

3. 深度融入全球化智能服务协同网络:83.5%服务商认为电商网站与AI服务商协同将成为主流。服务商应向上对接平台技术接口与安全基座,向下封装专业智能体,横向与同行多智能体动态组队,以开放协同构建长期竞争优势。

报告为电商平台如何与AI服务商协同提供了重要参考,平台不再是单纯交易场所,而是智能服务生态的关键枢纽。

1. 平台的最新做法与招商方向:电商网站应开放技术接口与安全基座,吸引AI服务商接入,提供合规数据、流量、培训及技术支持。调研显示83.5%服务商认为电商网站+AI服务商协同模式将成为主流,平台应主动构建这种协同网络,增强服务商生态黏性。

2. 运营管理与风险规避:服务商接入后,平台需在合规、稳定、高效运行方面加强管理。报告强调数据治理和统一数据资产的重要性,平台可帮助服务商和卖家建立更完善的数据体系,避免数据分散带来的AI价值释放不足。同时要注意结果付费模式可能存在归因和定价风险,平台可推动建立行业标准。

3. 满足平台商业需求:卖家对AI投入正从购买工具转向购买效果,平台若能与服务商一起提供按结果计费的RaaS模式,将提升平台对卖家的吸引力。平台还应支持多智能体协同,让服务商动态组队响应复杂需求,从而增加平台整体服务能力和商家粘性。

报告揭示了AI时代跨境电商服务商产业的新动向和商业模式变革,为研究提供了清晰框架。

1. 产业新动向:服务商正经历从传统服务商到AI服务商的全面进化,核心是从业务配AI转向AI生业务。组织上全员上手、数据驱动、产品专业化和交付闭环四大路径共同构成了AI原生企业的转型方向。

2. 新问题与商业模式:服务商向AI增长合伙人升级,收费从按工时、项目转向按结果计费的RaaS。报告调研显示21.4%服务商已尝试与GMV、利润等挂钩,但62.1%认同趋势却未找到落地方式,这说明结果付费模式仍面临定价模型、归因机制和交付风险等值得深入研究的问题。

3. 协同网络与政策启示:电商网站被定位为AI服务商获取合规数据、流量、培训及技术支持的关键枢纽,83.5%服务商认为协同模式将成为主流。这提示研究者和政策制定者需要关注平台开放接口、数据治理、多智能体协同等新机制,以及如何建立基于信任的全球化智能服务协同网络,为跨境电商服务体系提供制度与规则支持。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

Cross-border e-commerce service providers are undergoing a profound transformation in the AI era. The report identifies three core tasks that help clarify the future direction of the industry.

1. Evolve into AI-native enterprises: Traditional companies first build a business and then add AI, whereas AI-native enterprises embed AI into their strategic foundation, comprehensively restructuring across organization, data, products, and delivery to achieve AI-driven business growth.

2. Upgrade to AI growth partners: Service providers are moving away from hourly or project-based billing toward outcome-based RaaS (Results as a Service) models, sharing operating metrics with sellers—such as tying fees to GMV, profit, and conversion rates. Currently, 21.4% of service providers have experimented with this model, but 62.1% recognize the trend yet have not implemented it.

3. Integrate into a global intelligent service collaboration network: E-commerce websites are becoming core hubs for compliant data, traffic, and technology. Some 83.5% of service providers believe that collaboration between e-commerce platforms and AI service providers will become mainstream. Service providers need to connect upward with platforms, package specialized AI agents downward, and coordinate horizontally across multiple agents to build an open, win-win ecosystem.

The transformation of service providers in the AI era will directly reshape brand marketing and channel strategies. Brands can draw actionable insights from the report to drive growth through AI.

1. Brand marketing and user behavior insights: AI-native service providers enable deeper understanding of user behavior through data-driven, intelligent operational loops. They help brands convert fragmented business data into continuously iterable data assets, optimizing product selection, marketing, and customer service while accelerating market responsiveness.

2. Product development and solution upgrades: Service providers are moving from delivering faster execution to designing better solutions, injecting industry knowledge and experience into AI products. Brands can leverage such specialized solutions to obtain intelligent tools that better fit their business scenarios, improving alignment between product development and marketing decisions.

3. Brand channels and collaboration networks: E-commerce websites are becoming critical hubs for AI service providers. Brands can embed themselves deeply into collaborative networks to gain compliant, stable traffic, training, and technical support. Dynamic multi-agent teams among service providers can respond to end-to-end needs from product selection to fulfillment, helping brands achieve more efficient growth loops on platforms.

The changing service provider model directly affects sellers' costs, risks, and growth opportunities. The report reveals several key signals.

1. Growth opportunities and cooperation models: Service providers are shifting from completing individual tasks to sharing operational metrics. Sellers can move from buying tools to buying outcomes. If service providers link fees to GMV, profit, and conversion rates, sellers can reduce trial-and-error costs and achieve more certain growth results.

2. Risk warnings and responses: While 21.4% of service providers have tried outcome-based pricing, 62.1% acknowledge the trend but have not yet identified a suitable pricing model. Sellers should be wary of concept hype, and must evaluate whether service providers can define growth baselines, track AI actions, and establish attribution models. Without these, outcome-based pricing will be difficult to deliver.

3. Learning points and collaboration dividends: The mainstream trend is collaboration between e-commerce platforms and AI service providers, with 83.5% believing this model will become dominant. Sellers should prioritize service providers deeply embedded in e-commerce platforms to leverage compliant data, traffic, and technical support for better operational efficiency. They should also watch for multi-agent collaboration capabilities among service providers, which enable flexible team formation to meet complex needs.

Although the report is geared toward service providers, its insights into AI-native enterprise transformation and data loops offer important lessons for factories advancing digitalization and e-commerce transformation.

1. Product production and design needs: AI-native service providers use data-driven, intelligent operations to more accurately predict market demand and user preferences. Factories can leverage these service providers' data feedback to refine product design and production planning, avoid blind production, and improve new product success rates.

2. Business opportunities and cooperation models: As service providers upgrade to AI growth partners with outcome-linked pricing, factories can access professional support in product selection, marketing, and fulfillment at lower risk. Choosing service providers with industry experience enables faster responses to market changes.

3. Digitalization and e-commerce insights: The report highlights that data governance and process restructuring are essential for unlocking AI's value. When advancing digitalization, factories should consolidate scattered business data into iterable data assets, forming a cyclical mechanism from data to models to business. Meanwhile, as e-commerce platform–AI service provider collaboration networks become mainstream, factories can proactively integrate with such hubs to obtain compliant traffic and technical support.

Service providers should focus on the three long-term tasks outlined in the report, which together define the path from traditional service provider to AI service provider.

1. Evolve into an AI-native enterprise: The core is shifting from adding AI to existing business toward generating business from AI. The implementation path includes building agile collaboration systems where all employees can use AI at the organizational level; forming a data-to-model-to-business loop for continuous improvement; embedding industry expertise into AI tools to differentiate products; and moving from point delivery to closed-loop growth in delivery.

2. Upgrade to an AI growth partner: The role shifts from completing individual tasks to sharing operational metrics. Capability evaluation moves from whether features are implemented to whether quantifiable business results are delivered, and billing evolves toward outcome-based RaaS. The report's survey shows 21.4% of service providers have tried tying fees to GMV and profit, but 62.1% have yet to find suitable implementation methods—this represents a significant innovation opportunity.

3. Deeply integrate into a global intelligent service collaboration network: 83.5% of service providers believe collaboration between e-commerce platforms and AI service providers will become mainstream. Service providers should connect upward with platform technical interfaces and security foundations, package specialized AI agents downward, and dynamically form teams horizontally with peers in multi-agent collaboration to build long-term competitive advantage through openness and synergy.

The report offers an important reference for e-commerce platforms on how to collaborate with AI service providers. Platforms are no longer mere transaction venues but key hubs of the intelligent service ecosystem.

1. Latest platform practices and merchant acquisition: E-commerce platforms should open technical interfaces and security foundations to attract AI service providers, offering compliant data, traffic, training, and technical support. The survey shows 83.5% of service providers believe the "e-commerce platform + AI service provider" collaboration model will become mainstream. Platforms should proactively build such collaborative networks to strengthen service provider ecosystem stickiness.

2. Operations management and risk mitigation: After service providers onboard, platforms need to strengthen management around compliance, stability, and efficient operations. The report emphasizes governance and unified data assets; platforms can help service providers and sellers establish better data systems to avoid fragmented data that limits AI value. Platforms should also watch for attribution and pricing risks in outcome-based models and can drive the creation of industry standards.

3. Meeting platform business needs: Sellers are shifting from buying tools to buying outcomes. If platforms work with service providers to offer outcome-based RaaS models, they will become more attractive to sellers. Platforms should also support multi-agent collaboration, allowing service providers to dynamically form teams to handle complex needs, thereby increasing the platform's overall service capability and merchant loyalty.

The report reveals new industry dynamics and business model shifts in the AI-era cross-border e-commerce service provider sector, providing a clear framework for research.

1. New industry dynamics: Service providers are undergoing a comprehensive evolution from traditional to AI-native service providers, with the core shift from adding AI to business toward generating business from AI. Four major paths—full-staff AI adoption, data-driven operations, product specialization, and closed-loop delivery—together define the transformation direction for AI-native enterprises.

2. New issues and business models: Service providers are upgrading to AI growth partners, with billing moving from hourly/project-based to outcome-based RaaS. The report's survey shows 21.4% of service providers have tied fees to GMV and profit, but 62.1% recognize the trend yet have not implemented it. This indicates that outcome-based pricing still faces challenging issues—pricing models, attribution mechanisms, and delivery risks—that merit further research.

3. Collaboration networks and policy implications: E-commerce websites are positioned as key hubs for AI service providers to access compliant data, traffic, training, and technical support, with 83.5% believing the collaboration model will become mainstream. This suggests researchers and policymakers should focus on new mechanisms such as open platform interfaces, data governance, and multi-agent collaboration, as well as how to build a trust-based global intelligent service collaboration network to supply institutional and regulatory support for the cross-border e-commerce service system.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

【亿邦原创】AI时代,服务商需要的不仅是当下的能力补位与效率提升,更是面向长期的进化方向与价值定位。从组织基因的深层重构,到服务模式的深刻重塑,再到协同网络的深度协同,服务商的转型终局,是完成从“传统服务商” 到“AI服务商”的全面进化,在AI时代确立自身不可替代的核心竞争力。

亿邦智库与亚马逊SPN服务商网络联合发布的《智胜新周期—跨境电商服务商AI发展报告》(以下简称“报告”)提出,服务商穿越新周期需要完成三项长期任务:向AI原生企业进化,向“AI增长合伙人”升级,并向全球化智能服务协同网络深度迈进。(点击链接下载完整报告

01

任务一:向AI原生企业进化

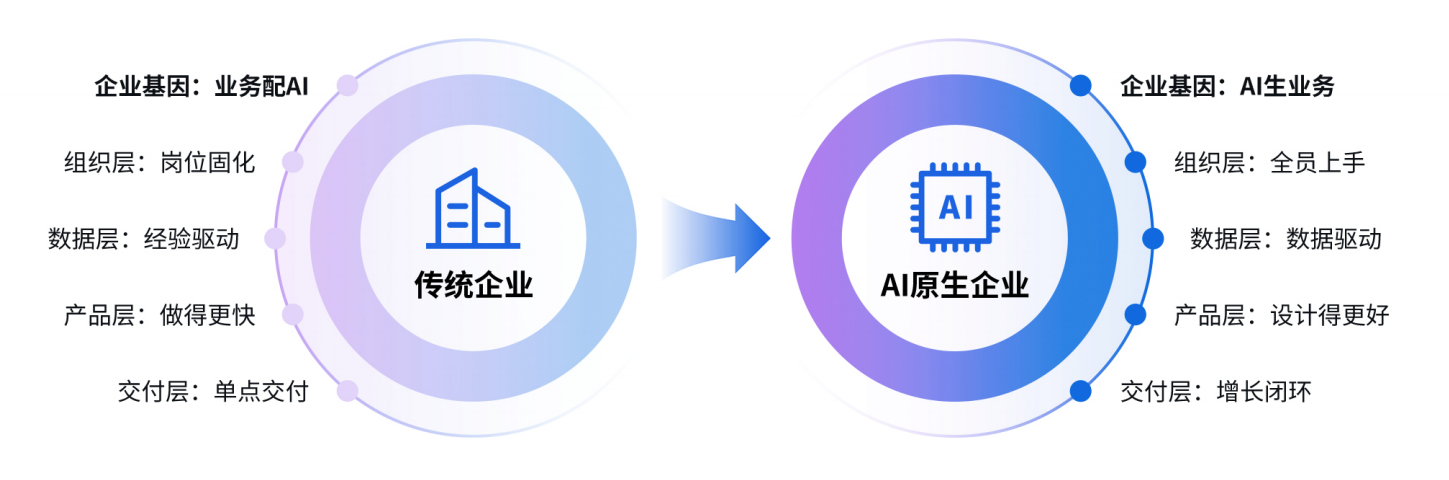
与传统企业“先有业务、再配AI”的逻辑不同,AI原生企业从创立之初或战略底层,就将AI深度嵌入企业基因中,因此天然具备更快的响应速度、更高的资源效率和更强的复杂场景适应力。

对于服务商而言,未来竞争的关键不只是增加AI工具应用,而是通过组织、数据、产品和交付体系的全面重构,实现从“业务配AI”到“AI生业务”的本质跨越,具体落地路径体现在四个层面:

在组织层面,服务商需要从“岗位固化”转向“全员上手”,构建人人可调用AI、流程可拆解、步骤可协同的敏捷协作体系。AI不再只是某个部门或技术团队的专属工具,而应成为贯穿企业经营流程的基础能力。过去,服务商依赖专业人员经验完成选品判断、广告优化、市场分析等工作,能力往往沉淀在个人和团队内部。而AI原生企业则通过智能工具、知识库和自动化流程,将个人经验转化为组织能力,使企业能够更快速响应市场变化。

在数据层面,服务商需要从“经验驱动”转向“数据驱动”,以智能运营闭环重塑企业经营流程。通过数据沉淀、分析和反馈,实现业务流程的自循环、自优化,让数据成为企业经营的中枢神经。跨境电商服务涉及选品、营销、物流、客服、合规等多个环节,长期积累的大量业务数据是服务商构建差异化能力的重要基础。但如果数据分散在不同部门和业务系统中,无法形成统一的数据资产,AI价值也难以充分释放。

因此,服务商需要建立更加完善的数据治理体系,将业务经验、客户需求和运营结果转化为可持续迭代的数据资产。通过数据反馈优化模型,再由模型提升业务决策效率,形成“数据—模型—业务”的循环提升机制。

在产品层面,服务商需要从“做得更快”升级为“设计得更好”。通过将行业专业知识和多年积累的经验注入AI产品,提高解决方案与业务场景的匹配度,形成区别于通用工具的专业能力。AI工具正在快速普及,基础功能逐渐趋于同质化。未来,服务商的价值不在于简单调用大模型,而在于能否结合自身行业理解,将AI能力转化为适用于具体业务场景的解决方案。

在交付层面,服务商需要从“单点交付”转向“增长闭环”。通过可量化结果提升客户满意度和复购率,实现服务能力边界的持续扩大。AI原生并非简单部署更多工具,而是围绕企业底层能力进行系统性重构,让AI成为企业运行方式的一部分。

02

任务二:向“AI增长合伙人”服务模式升级

卖家对AI投入正从购买工具转向购买效果,服务商角色也由完成单项任务,转向共同承担经营指标。能力评价不再只看功能是否实现,而要看是否带来可量化的业务结果;收费方式则从按工时、按项目和固定订阅,转向按结果计费的RaaS(Result-as-a-Service)。

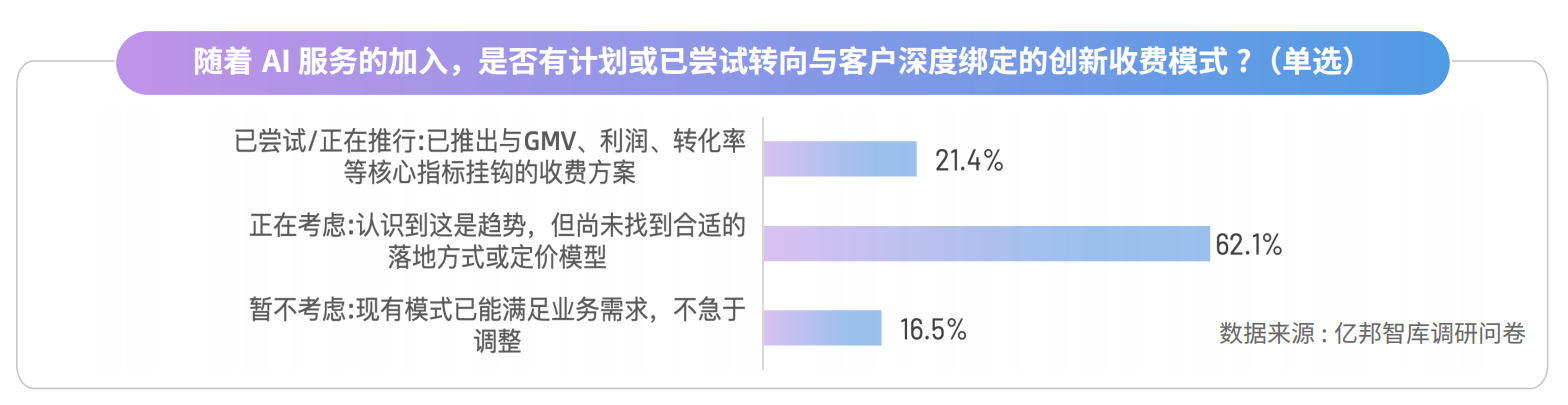
据IDC预测,到2028年,70%的软件供应商将按业务结果、交易量或自动化成果计费1。报告调研显示,21.4%的服务商已经尝试让收费与GMV、利润、转化率等核心指标挂钩,62.1%的服务商认同结果付费趋势,但尚未找到合适的落地方式或定价模型。

RaaS并不是简单更换价目表。它要求服务商具备深厚的行业洞察、业务经验和运营能力,能够共同定义增长基线、追踪AI动作、建立归因模型并管理交付风险。只有把数据、模型和产品持续嵌入卖家业务,服务商才可能与客户形成共享增长、共担结果的长期关系。

03

任务三:向全球化智能服务协同网络深度迈进

在AI时代,单一服务商的能力边界正在受到限制,开放协同成为行业发展的重要方向。报告指出,新周期下,电商网站成为AI服务商获取合规数据、流量、培训及技术支持的关键枢纽。

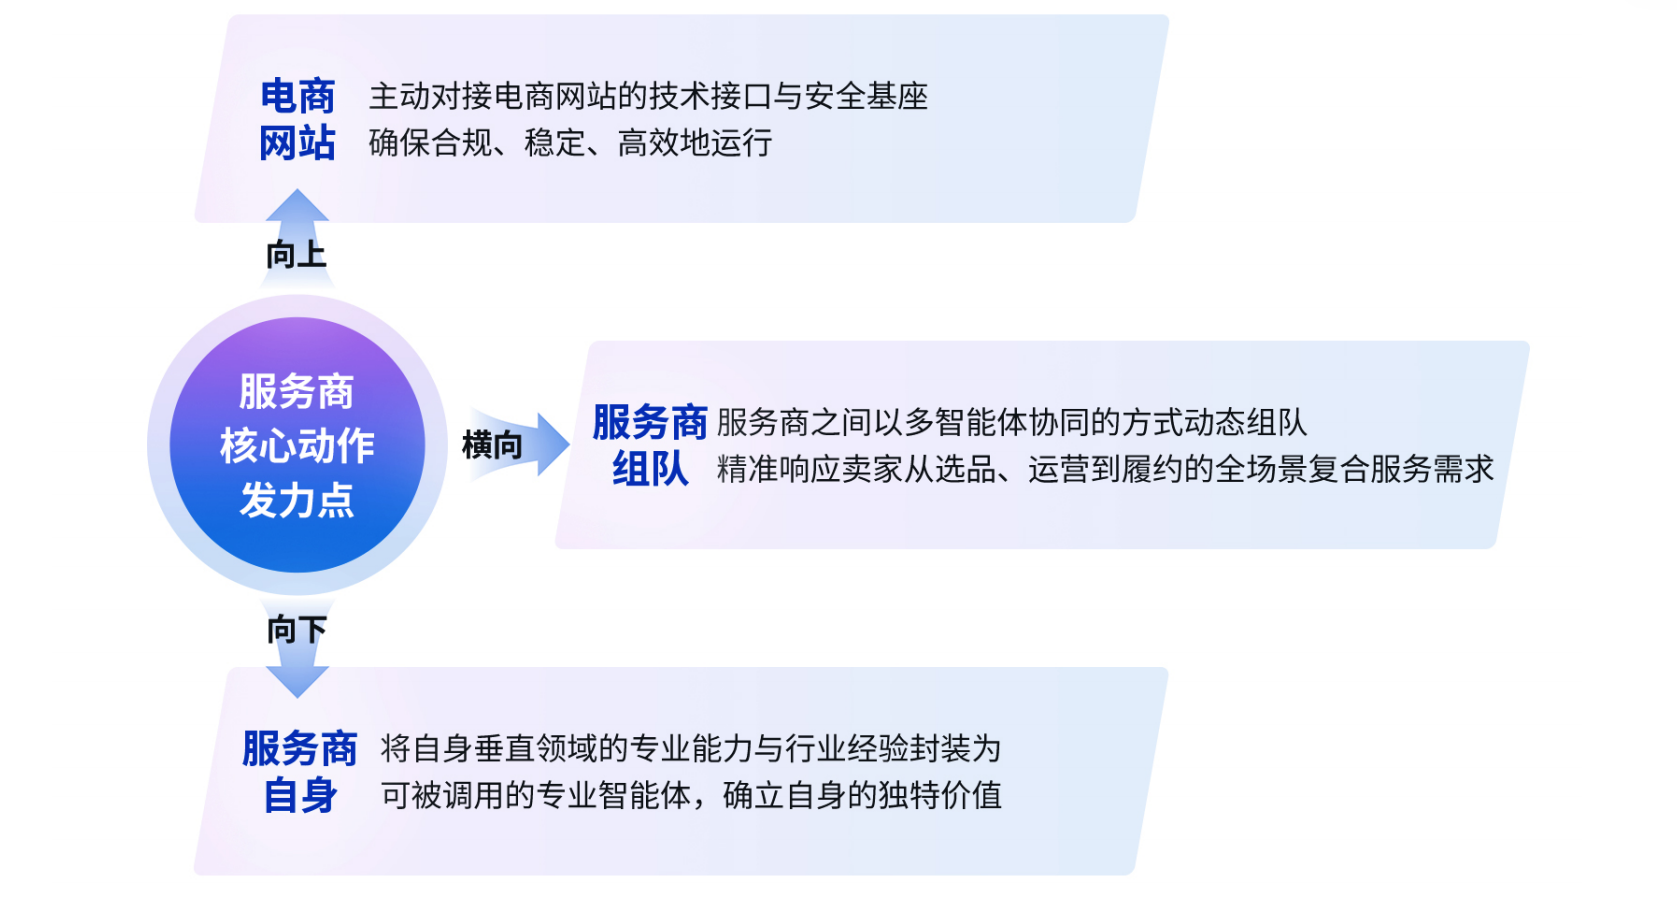
调研显示,高达83.5%的服务商认为“电商网站+AI服务商”协同模式将成为主流2。服务商的核心命题已经从“是否接入”转向“如何深度嵌入”。要在协同网络中构建竞争优势,服务商需要围绕三个方向持续发力:

向上,主动对接电商网站的技术接口与安全基座,确保AI服务合规、稳定、高效运行;

向下,将自身垂直领域的专业能力与行业经验封装为可被调用的专业智能体,确立自身独特价值;

横向,服务商之间通过多智能体协同方式动态组队,精准响应卖家从选品、运营到履约的全场景复合服务需求。

通过开放接口与持续进化,最终构建起一个基于信任、更高效、更具韧性与创新活力的全球化智能服务协同网络。

AI正在推动跨境电商服务体系进入新发展阶段。对于服务商而言,未来竞争不再只是单一服务能力的比拼,而是组织能力、数据能力、产品能力、交付能力以及协同能力的综合竞争。

从传统服务商到AI服务商,是一场围绕企业底层能力的系统性升级。只有完成AI原生化转型、构建增长伙伴关系,并深度融入全球化智能服务协同网络,服务商才能在新周期中建立长期竞争优势,持续释放增长动能。

参考阅读:

[1]https://sanieinstitute.substack.com/p/agentic-ai-is-not-a-feature-it-is

[2]2026跨境电商服务商AI能力调研 有效样本N=206

本文首发于 亿邦动力 官方网站

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

跨境电商服务商如何实现AI转型?

服务商需完成三项长期任务:向AI原生企业进化,从组织、数据、产品、交付四个层面重构底层能力;向AI增长合伙人服务模式升级,从按工时计费转向RaaS按结果付费;深度融入全球化智能服务协同网络,通过电商平台协同、多智能体协作构建竞争优势,最终从传统服务商进化为AI服务商。

什么是AI原生企业?与传统企业有何不同?

AI原生企业从创立之初或战略底层就将AI深度嵌入企业基因,具备更快的响应速度、更高的资源效率和更强的复杂场景适应力。服务商需要通过组织全员上手、数据驱动决策、产品注入行业知识、交付形成增长闭环,实现从业务配AI到AI生业务的本质跨越。

RaaS模式是什么意思?跨境电商服务商为什么转向RaaS?

RaaS(Result-as-a-Service)指按结果计费,收费与GMV、利润、转化率等核心指标挂钩。报告调研显示21.4%的服务商已尝试结果计费,62.1%认同趋势但尚未落地。IDC预测到2028年70%的软件供应商将按业务结果、交易量或自动化成果计费,推动服务商角色转向共同承担经营指标。

电商平台或电商网站在跨境电商AI服务生态中扮演什么角色?

电商网站成为AI服务商获取合规数据、流量、培训及技术支持的关键枢纽,调研中83.5%的服务商认为电商网站+AI服务商协同模式将成为主流。服务商需向上对接平台技术接口与安全基座,向下封装垂直行业专业智能体,横向通过多智能体协同动态组队,响应卖家全场景复合需求。

这么好看,分享一下?

朋友圈 分享

APP内打开

+1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0