广告
加载中

三类械成必答题?敷尔佳 贝泰妮 巨子生物布局医美注射赛道

张从容 2026-09-16 11:04
张从容 2026/09/16 11:04

邦小白快读

EN
全文速览

这篇文章梳理了大众熟知的多个护肤、医用敷料品牌集中入局医美注射赛道的核心信息,和日常医美消费、护肤产品选择直接相关。

1. 敷尔佳、贝泰妮、巨子生物都将推出各自首款三类医美注射产品:敷尔佳的“花季动能素”10月上市,主打改善成人皮肤干燥、暗沉;贝泰妮自研的“注射用透明质酸钠溶液”也就是俗称的水光针,刚完成三类械获批;巨子生物的“可丽金芯生753胶原针”已经正式上市。

2. 这些品牌扎堆布局注射类医美产品,核心原因是原来主打的医用敷料品类已经陷入价格战利润变薄,加上今年9月底医保个账支付白名单落地后,医用敷料这类产品不能再刷医保个人账户,原有业务营收波动大,需要寻找新的增长点。

3. 当前新推出的这类注射产品普遍主打改善真皮层ECM微环境的功效,有权威学术研究支撑,大家选择相关医美项目时,优先认准正规三类械资质产品,避开不合规的水货、假货。

本文披露了功效护肤、医用敷料赛道头部玩家集体布局三类械医美注射赛道的行业动向,对品牌经营决策有明确参考价值。

1. 品类布局的趋势参考:原先以二类械医用敷料为核心医疗器械品类的品牌,普遍面临敷料品类价格战加剧、利润空间被压缩的问题,叠加2026年9月底落地的医保个账支付白名单新规,敷料类产品无法再走医保个账支付渠道,相关板块营收波动明显,高门槛的三类医美注射赛道成为拉动医疗器械板块回暖的核心方向。

2. 产品研发与营销的方向参考:当前新入局的注射类产品普遍锚定ECM(细胞外基质)调节的功效方向,不管是透明质酸类水光产品还是重组胶原类针剂,都主打补充真皮层支撑结构、改善皮肤状态的价值点,匹配用户抗衰、改善肤质的核心痛点,相关方向也有顶级期刊的学术理论支撑。

3. 赛道验证参考:华熙生物提前布局的两款水光针2026年上半年销量同比增长超150%,其中上市不满一年的单品销售额就近亿元,验证了该赛道的增长潜力。

本文释放了医美、功效护肤赛道的政策变动、增量赛道机会等关键经营信息,对卖家选品调整、风险规避有直接指导意义。

1. 明确风险提示:今年9月底各地落地医保个账支付白名单制度后,医用敷料这类械字号“马甲产品”将无法使用医保个人账户支付,原先靠医保引流的敷料类产品销售会受到明显冲击,卖家需要提前调整相关品类的库存和销售策略,避免货物积压。

2. 明确机会提示:三类械医美注射类产品是当前确定性较强的高增长赛道,华熙生物旗下两款水光针2026年上半年销售支数同比增长超150%,其中上市未满一年的“润致缇透”销售规模近亿元;近期敷尔佳、贝泰妮、巨子生物的首款注射类三类械将集中上市,是可重点跟进的潜力品类。

3. 需求变化提示:当前医美注射类产品的用户需求已经从基础填充转向根源性皮肤状态改善,主打干燥缓解、暗沉提亮、胶原再生、调节ECM微环境的产品更容易获得消费者认可。

本文透露出医美、医用敷料赛道的产品需求转向、商业合作机会,对生产端调整业务布局有重要参考价值。

1. 传统品类的需求预警:当前二类械医用敷料已经成为价格战重灾区,叠加医保支付政策收紧,品牌方的敷料类订单利润空间会被持续压缩,工厂不可过度依赖该类品类的生产订单,需要提前拓展新的业务方向。

2. 明确商业机会:敷尔佳、贝泰妮、巨子生物等多家头部护肤、敷料品牌正在集中布局三类械医美注射类产品,涵盖透明质酸水光针、重组胶原蛋白注射剂两大方向,功效主打改善皮肤干燥暗沉、补充真皮层胶原、调节ECM微环境,具备三类医疗器械生产资质的工厂,可重点对接相关品牌的联合研发、定制生产需求。

3. 产品设计参考:从已经跑出来的爆品来看,有明确皮肤改善靶点、具备权威学术理论支撑的注射类产品,更容易获得品牌方和市场的认可。

本文梳理了功效护肤、医美赛道头部玩家的业务布局动向和现存经营痛点,可为服务商找准服务方向、匹配客户需求提供参考。

1. 行业趋势判断:传统医用敷料赛道已经增长见顶,叠加医保支付政策收紧,行业头部玩家正集体从敷料品类切入三类械医美注射赛道,未来两到三年,注射类医美产品会成为品牌营销投入、渠道铺设的核心品类。

2. 客户痛点识别:当前布局注射赛道的品牌大多原先主打大众护肤品、二类医用敷料,缺乏三类医美产品的院线渠道铺设、合规营销传播、专业端医生教育的相关经验,同时需要为新产品搭建具备专业学术支撑的功效传播体系。

3. 服务方向参考:围绕三类械注射产品的合规营销服务、院线渠道对接服务、学术内容打造服务会有明确的市场需求,参考华熙生物的爆品打造路径,有能力帮助新品牌快速跑出大单品的服务商,会更受品牌客户青睐。

本文反映了医美、功效护肤赛道的品类变动趋势和商家动向,可为平台的招商布局、品类运营、合规风控提供参考。

1. 招商方向调整参考:医用敷料类商品因价格战激烈、叠加医保支付政策限制,增长已经显露出疲态,平台可重点引入三类械医美注射类的品牌商家,包括即将推出新品的敷尔佳、贝泰妮、巨子生物等头部玩家,抓住品类增长红利——参考华熙生物同类产品半年销量增长150%、新品上市未满一年销售额近亿的表现,该品类能为平台带来明确的营收增量。

2. 品类运营方向参考:可重点打造主打ECM根源改善、皮肤干燥暗沉修复、胶原再生的医美注射类商品心智,匹配用户消费升级的需求。

3. 合规风控提示:要严格核查医美注射类商品的三类械资质,杜绝无资质不合规产品上架;同时针对医用敷料类商品,及时调整宣传规则,不允许商家暗示产品可刷医保销售,规避合规风险。

本文记录了2026年功效护肤、医疗器械领域的产业新动向,为相关产业研究、趋势分析提供了鲜活的行业样本。

1. 核心产业新动向:原先以二类械医用敷料、功效性护肤品为主营业务的敷尔佳、贝泰妮、巨子生物三家头部企业,于2026年集中推出首款三类械医美注射产品,正式切入医美注射赛道,反映出敷料赛道增长见顶后,功效护肤企业正集体向高壁垒的医疗美容终端赛道延伸。

2. 产业变动的驱动因素:一是医用敷料品类陷入价格战,利润被持续压缩,近三年相关企业医疗器械板块营收波动明显,2025年上半年敷尔佳、贝泰妮的医疗器械营收近乎腰斩;二是2026年5月出台的医保新规要求9月底前落地个账支付白名单,切断了敷料类产品的个账支付渠道,倒逼企业转型;三是三类注射医美赛道增长确定性强,华熙生物同类产品2026年上半年销量同比增超150%,验证了商业模式可行性。

3. 研发新趋势:新入局的注射类产品普遍锚定ECM细胞外基质调节的技术方向,学术背书属性更强。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

This article breaks down the key details behind the wave of well-known skincare and medical dressing brands entering the medical aesthetic injectable market, with direct relevance to everyday consumer choices for aesthetic treatments and skincare products.

1. Top brands including Voolga, Botanee, and Giant Biogene are all launching their first Class III medical device-certified injectable products: Voolga’s "Blossom Kinetic Booster" will launch in October, formulated to improve dry, dull adult skin; Botanee’s self-developed "injectable sodium hyaluronate solution"—commonly known as a water-light injection—has just received Class III medical device approval; Giant Biogene’s "Collgene Core 753 Collagen Injection" has already officially launched.

2. The core drivers of this collective push into injectable aesthetics are twofold: the brands’ core medical dressing category has become mired in price wars that erode profit margins, and the implementation of the medical insurance personal account payment whitelist at the end of September will bar medical dressings from being covered by personal medical insurance accounts, creating significant revenue volatility in existing business lines and pushing brands to seek new growth drivers.

3. These newly launched injectables generally focus on improving the dermal extracellular matrix (ECM) microenvironment, an efficacy claim backed by authoritative academic research. When selecting relevant aesthetic treatments, consumers are advised to prioritize products with formal Class III medical device certification and avoid unapproved parallel imports or counterfeit products.

This article covers the industry trend of leading players in the efficacious skincare and medical dressing segments collectively entering the Class III medical device-certified medical aesthetic injectable market, providing clear reference value for brand business decision-making.

1. Category expansion trend reference: Brands that previously centered their medical device portfolios on Class II medical dressings are普遍 facing intensifying price wars and compressed margins in the dressing category. Compounded by the new medical insurance personal account payment whitelist regulation taking effect at the end of September 2026, which excludes dressing products from personal account payment channels and causing notable revenue volatility in related segments, the high-barrier Class III medical aesthetic injectable track has become the core direction to drive recovery in the medical device business.

2. Product R&D and marketing direction reference: New entrants in the injectable category are universally anchoring their value propositions on extracellular matrix (ECM) regulation. Both hyaluronic acid-based water-light injections and recombinant collagen injectables highlight their ability to replenish dermal support structures and improve skin condition, addressing core consumer pain points around anti-aging and skin quality improvement—a positioning also supported by academic research published in top-tier journals.

3. Track validation reference: Bloomage Biotech, which laid out early布局 in this space, saw its two water-light injection products record over 150% year-over-year sales growth in the first half of 2026; one SKU launched less than a year ago already generated nearly RMB 100 million in sales, validating the growth potential of this track.

This article releases critical business information including policy changes and incremental track opportunities in the medical aesthetic and efficacious skincare sectors, offering direct guidance for sellers to adjust product selection and mitigate risks.

1. Clear risk warning: Following the implementation of the medical insurance personal account payment whitelist system across regions at the end of September this year, medical dressing products marketed under Class I/II medical device registrations will no longer be eligible for payment via personal medical insurance accounts. Sales of dressing products that previously relied on medical insurance as a customer acquisition channel will see a significant impact, so sellers need to adjust inventory and sales strategies for this category in advance to avoid overstocking.

2. Clear opportunity indicator: Class III medical device-certified aesthetic injectables represent a high-growth track with strong certainty. Bloomage Biotech’s two water-light injection products saw unit sales grow over 150% year-over-year in the first half of 2026, with "Runzhiti Tou"—a SKU launched less than a year ago—approaching RMB 100 million in sales. The upcoming concentrated launch of first-ever Class III injectable products from Voolga, Botanee, and Giant Biogene represents a high-potential category worth prioritizing.

3. Demand shift reminder: Consumer demand for aesthetic injectables has evolved from basic filling to root-cause skin condition improvement. Products focused on dryness relief, dullness brightening, collagen regeneration, and ECM microenvironment regulation are more likely to win consumer recognition.

This article reveals shifting product demand and new business partnership opportunities in the medical aesthetic and medical dressing sectors, providing important reference for manufacturers to adjust their business布局.

1. Demand warning for traditional categories: Class II medical dressings have become a major battleground for price wars, compounded by tightening medical insurance payment policies. Profit margins for dressing orders from brand clients will continue to be compressed, so manufacturers should avoid over-reliance on production orders for this category and proactively explore new business directions.

2. Clear business opportunities: Multiple leading skincare and dressing brands including Voolga, Botanee, and Giant Biogene are collectively expanding into Class III medical aesthetic injectables, covering two major segments: hyaluronic acid water-light injections and recombinant collagen injectables. These products are positioned to improve dry, dull skin, replenish dermal collagen, and regulate the ECM microenvironment. Manufacturers with Class III medical device production qualifications should prioritize pursuing joint R&D and custom production partnerships with these brands.

3. Product design reference: Based on the performance of existing breakout products, injectables with clear skin improvement targets and backing from authoritative academic research are more likely to gain recognition from both brand partners and the broader market.

This article outlines the business布局 moves and existing operational pain points of leading players in the efficacious skincare and medical aesthetic sectors, providing reference for service providers to identify service directions and align with client needs.

1. Industry trend assessment: The traditional medical dressing track has reached peak growth, compounded by tightening medical insurance payment policies. Leading industry players are collectively shifting from the dressing category to the Class III medical aesthetic injectable track. Over the next two to three years, aesthetic injectables will become the core category for brands’ marketing investment and channel expansion.

2. Client pain point identification: Most brands entering the injectable track previously focused on mass-market skincare and Class II medical dressings, lacking experience in professional clinic channel distribution, compliant marketing communications, and clinician education for Class III medical aesthetic products. They also need to build efficacy communication frameworks for new products that are supported by professional academic evidence.

3. Service direction reference: There will be clear market demand for services supporting Class III injectable products, including compliant marketing, clinic channel matchmaking, and academic content development. Drawing on Bloomage Biotech’s breakout product playbook, service providers capable of helping new brands rapidly build blockbuster SKUs will be particularly favored by brand clients.

This article reflects category trends and merchant movements in the medical aesthetic and efficacious skincare sectors, providing reference for platforms to adjust merchant recruitment, category operation, and compliance risk control strategies.

1. Merchant recruitment adjustment reference: Medical dressing products have shown slowing growth due to fierce price wars and medical insurance payment restrictions. Platforms can prioritize onboarding brand merchants offering Class III medical aesthetic injectables, including leading players such as Voolga, Botanee, and Giant Biogene which are poised to launch new products, to capture category growth dividends. For context, comparable products from Bloomage Biotech delivered 150% half-year sales growth, with a new SKU reaching nearly RMB 100 million in sales within its first year, demonstrating that this category can deliver clear incremental revenue for platforms.

2. Category operation direction reference: Platforms can focus on building consumer mindshare around aesthetic injectables positioned for root-cause ECM improvement, dry and dull skin repair, and collagen regeneration, to align with consumer demand for upgraded aesthetic services.

3. Compliance risk control reminder: Platforms must strictly verify the Class III medical device qualifications of aesthetic injectable products to prevent unqualified, non-compliant products from being listed. For medical dressing products, platforms should also update advertising rules in a timely manner to prohibit merchants from implying products are eligible for medical insurance payment, mitigating compliance risks.

This article documents new industrial developments in China’s efficacious skincare and medical device sectors in 2026, providing a real-world industry sample for related industrial research and trend analysis.

1. Core new industrial trend: Three leading enterprises previously focused on Class II medical dressings and efficacious skincare—Voolga, Botanee, and Giant Biogene—are all launching their first Class III medical aesthetic injectable products in 2026, formally entering the aesthetic injectable track. This shift reflects a collective move by efficacious skincare firms to expand into the high-barrier medical aesthetic end-market as growth in the medical dressing segment peaks.

2. Drivers of industrial change: First, the medical dressing category has fallen into price wars that continue to compress margins, with notable revenue volatility in the medical device segments of relevant firms over the past three years; Voolga and Botanee saw their medical device revenue nearly halved in the first half of 2025. Second, new medical insurance regulations issued in May 2026, requiring implementation of the personal account payment whitelist by the end of September, cut off personal account payment channels for dressing products, forcing enterprise transformation. Third, the Class III aesthetic injectable track offers strong growth certainty, as evidenced by Bloomage Biotech’s comparable products recording over 150% year-over-year sales growth in the first half of 2026, validating the viability of the business model.

3. New R&D trend: New entrants in the injectable segment are universally anchoring their technology roadmaps on extracellular matrix (ECM) regulation, with stronger emphasis on academic evidence backing product efficacy.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

【亿邦原创】9月15日,敷尔佳官宣其首款三类医疗器械产品——“敷尔佳花季动能素”将于今年10月上市,标志着敷尔佳正式进入医美注射赛道。该产品主要用于改善成人皮肤干燥、肤色暗沉等问题。

无独有偶,9月12日,贝泰妮官宣其首款自研三类医疗器械获批,标志着公司正式进入医美注射赛道。获批产品为“注射用透明质酸钠溶液”(型号:BTN001),即市场俗称的“水光针”。

实际上,早在6月9日,巨子生物的III类械新品——重组Ⅰ型α1亚型胶原蛋白(即“可丽金芯生753胶原针”)已正式上市。这是巨子生物首款医美注射类III类医疗器械产品。

上述三家企业的共同点在于:主营业务均同时涵盖护肤品和医疗器械,且医疗器械产品以二类械(如医用敷料)为主。2026年,这几家企业集中从敷料领域切入医美注射赛道,背后有着怎样的考量?

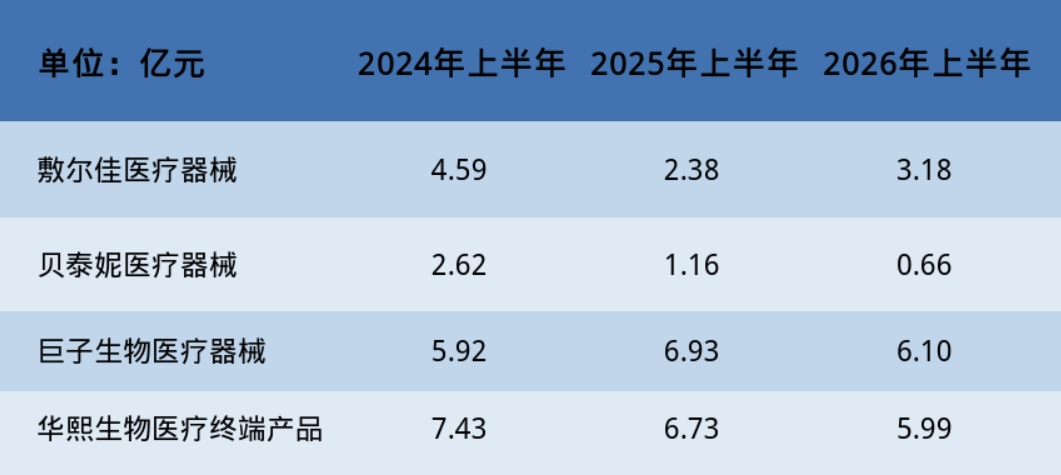
从财务数据来看,上述三家企业的医疗器械营收在近3年均经历了一定波动。2025年上半年,敷尔佳和贝泰妮的医疗器械营收同比近乎腰斩;2026年上半年,敷尔佳同比有所回暖,贝泰妮则继续下滑,巨子生物功效性护肤品营收同比微降4.52%。

从医疗器械之外的其他主营业务来看,敷尔佳表现相对稳健:2024年上半年至2026年上半年,其化妆品营收从4.81亿元增长至8.39亿元,近乎翻倍;同期,贝泰妮的护肤品业务营收虽有波动,但基本维持在20亿元以上;巨子生物功效性护肤品2026年上半年营收23.01亿元,对比2024年同期的19.4亿元仍有所增长。

从业务定位上看,医美注射产品并非整体业务的“救世主”,而是帮助医疗器械板块回暖的重要手段。上述三家企业主营的医疗器械产品以医用敷料为主,而这一品类已成为价格战的重灾区,大量竞品涌入导致利润空间被持续压缩。

与此同时,今年5月,监管部门发布新规,要求各地在9月底前建立定点零售药店个人医保账户支付白名单制度。医用敷料、女性护理垫等械字号“马甲产品”,将不再允许使用医保个人账户支付。

与上述三家企业主营业务类似的华熙生物,在护肤品业务营收连年承压的背景下,其医疗终端产品成为业务增长的重要支撑。据华熙生物2026年半年报,公司唯一实现营收增长的业务板块是原料,营收6.38亿元,同比增长1.87%;医疗终端产品营收5.99亿元,同比下降10.99%;皮肤科学创新转化业务营收4.48亿元,同比下降50.91%。

值得注意的是,医美注射产品成为2026年上半年华熙生物的重要增长点。2025年,华熙旗下两款水光针“润百颜玻玻”和“润致缇透”获批。据2026年半年报,其美塑类产品销售支数约298万支,同比增长超过150%,增长主要由“润百颜·玻玻”和“润致·缇透”贡献,其中“润致缇透”上市未满一年,销售规模已近亿元。

ECM(细胞外基质)失调被顶级期刊《Cell》列为14个细胞衰老标志物之一,是真皮层的重要组成部分,相当于细胞生存的“土壤”。目前,华熙旗下品牌润百颜已将品牌定位升级为“ECM科技护肤领导者”。

值得注意的是,贝泰妮和巨子生物在今年发布医美注射产品时,均强调其对ECM的作用:贝泰妮指出,透明质酸钠是人体真皮细胞外基质(ECM)的关键组成物质;巨子生物则表示,旗下可丽金芯生753胶原针可直接补充Ⅰ型胶原蛋白,同时诱导内源性胶原(如Ⅰ、Ⅲ、Ⅳ、Ⅶ型)合成,改善ECM微环境。

亿邦持续追踪报道该情报,如想了解更多与本文相关信息,请扫码关注作者微信。

本文首发于 亿邦动力 官方网站

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

国货功效护肤企业为何扎堆布局三类械医美注射赛道?

核心原因是企业原有以医用敷料为主的二类医疗器械板块营收出现波动,医用敷料赛道陷入价格战、利润空间被压缩,叠加医保新规限制械字号马甲产品医保支付,布局医美注射赛道可帮助医疗器械板块回暖,挖掘新的业绩增长空间。

目前已有哪些国货护肤企业推出三类械医美注射产品?

敷尔佳、贝泰妮、巨子生物、华熙生物均已布局三类械医美注射赛道,敷尔佳花季动能素将于2026年10月上市,贝泰妮首款自研水光针已获批,巨子生物可丽金芯生753胶原针已上市,华熙生物相关美塑类产品2026年上半年销量同比增长超150%。

ECM和皮肤衰老、医美注射有什么关联?

ECM即细胞外基质,是真皮层的重要组成部分,被顶级期刊《Cell》列为14个细胞衰老标志物之一。透明质酸钠、Ⅰ型胶原蛋白都是ECM的关键组成物质,相关医美注射产品可补充对应成分,改善ECM微环境,实现抗衰护肤效果。

当前国内医用敷料赛道面临哪些经营压力?

一方面大量竞品涌入让医用敷料赛道成为价格战重灾区,行业利润空间被持续压缩;另一方面2026年监管部门出台新规,要求医保个人账户支付建立定点零售药店白名单,医用敷料等械字号“马甲产品”不再允许使用医保个人账户支付。

这么好看,分享一下?

朋友圈 分享

APP内打开

+1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0