广告
加载中

《2026天猫新宠物观察》:214种宠物撑起猫狗之外的全新市场

龚作仁 2026-09-18 11:04
龚作仁 2026/09/18 11:04

邦小白快读

EN
全文速览

这份《2026天猫新宠物观察》能帮你快速了解非猫狗类宠物的市场全貌,获取实用的饲养筹备参考。

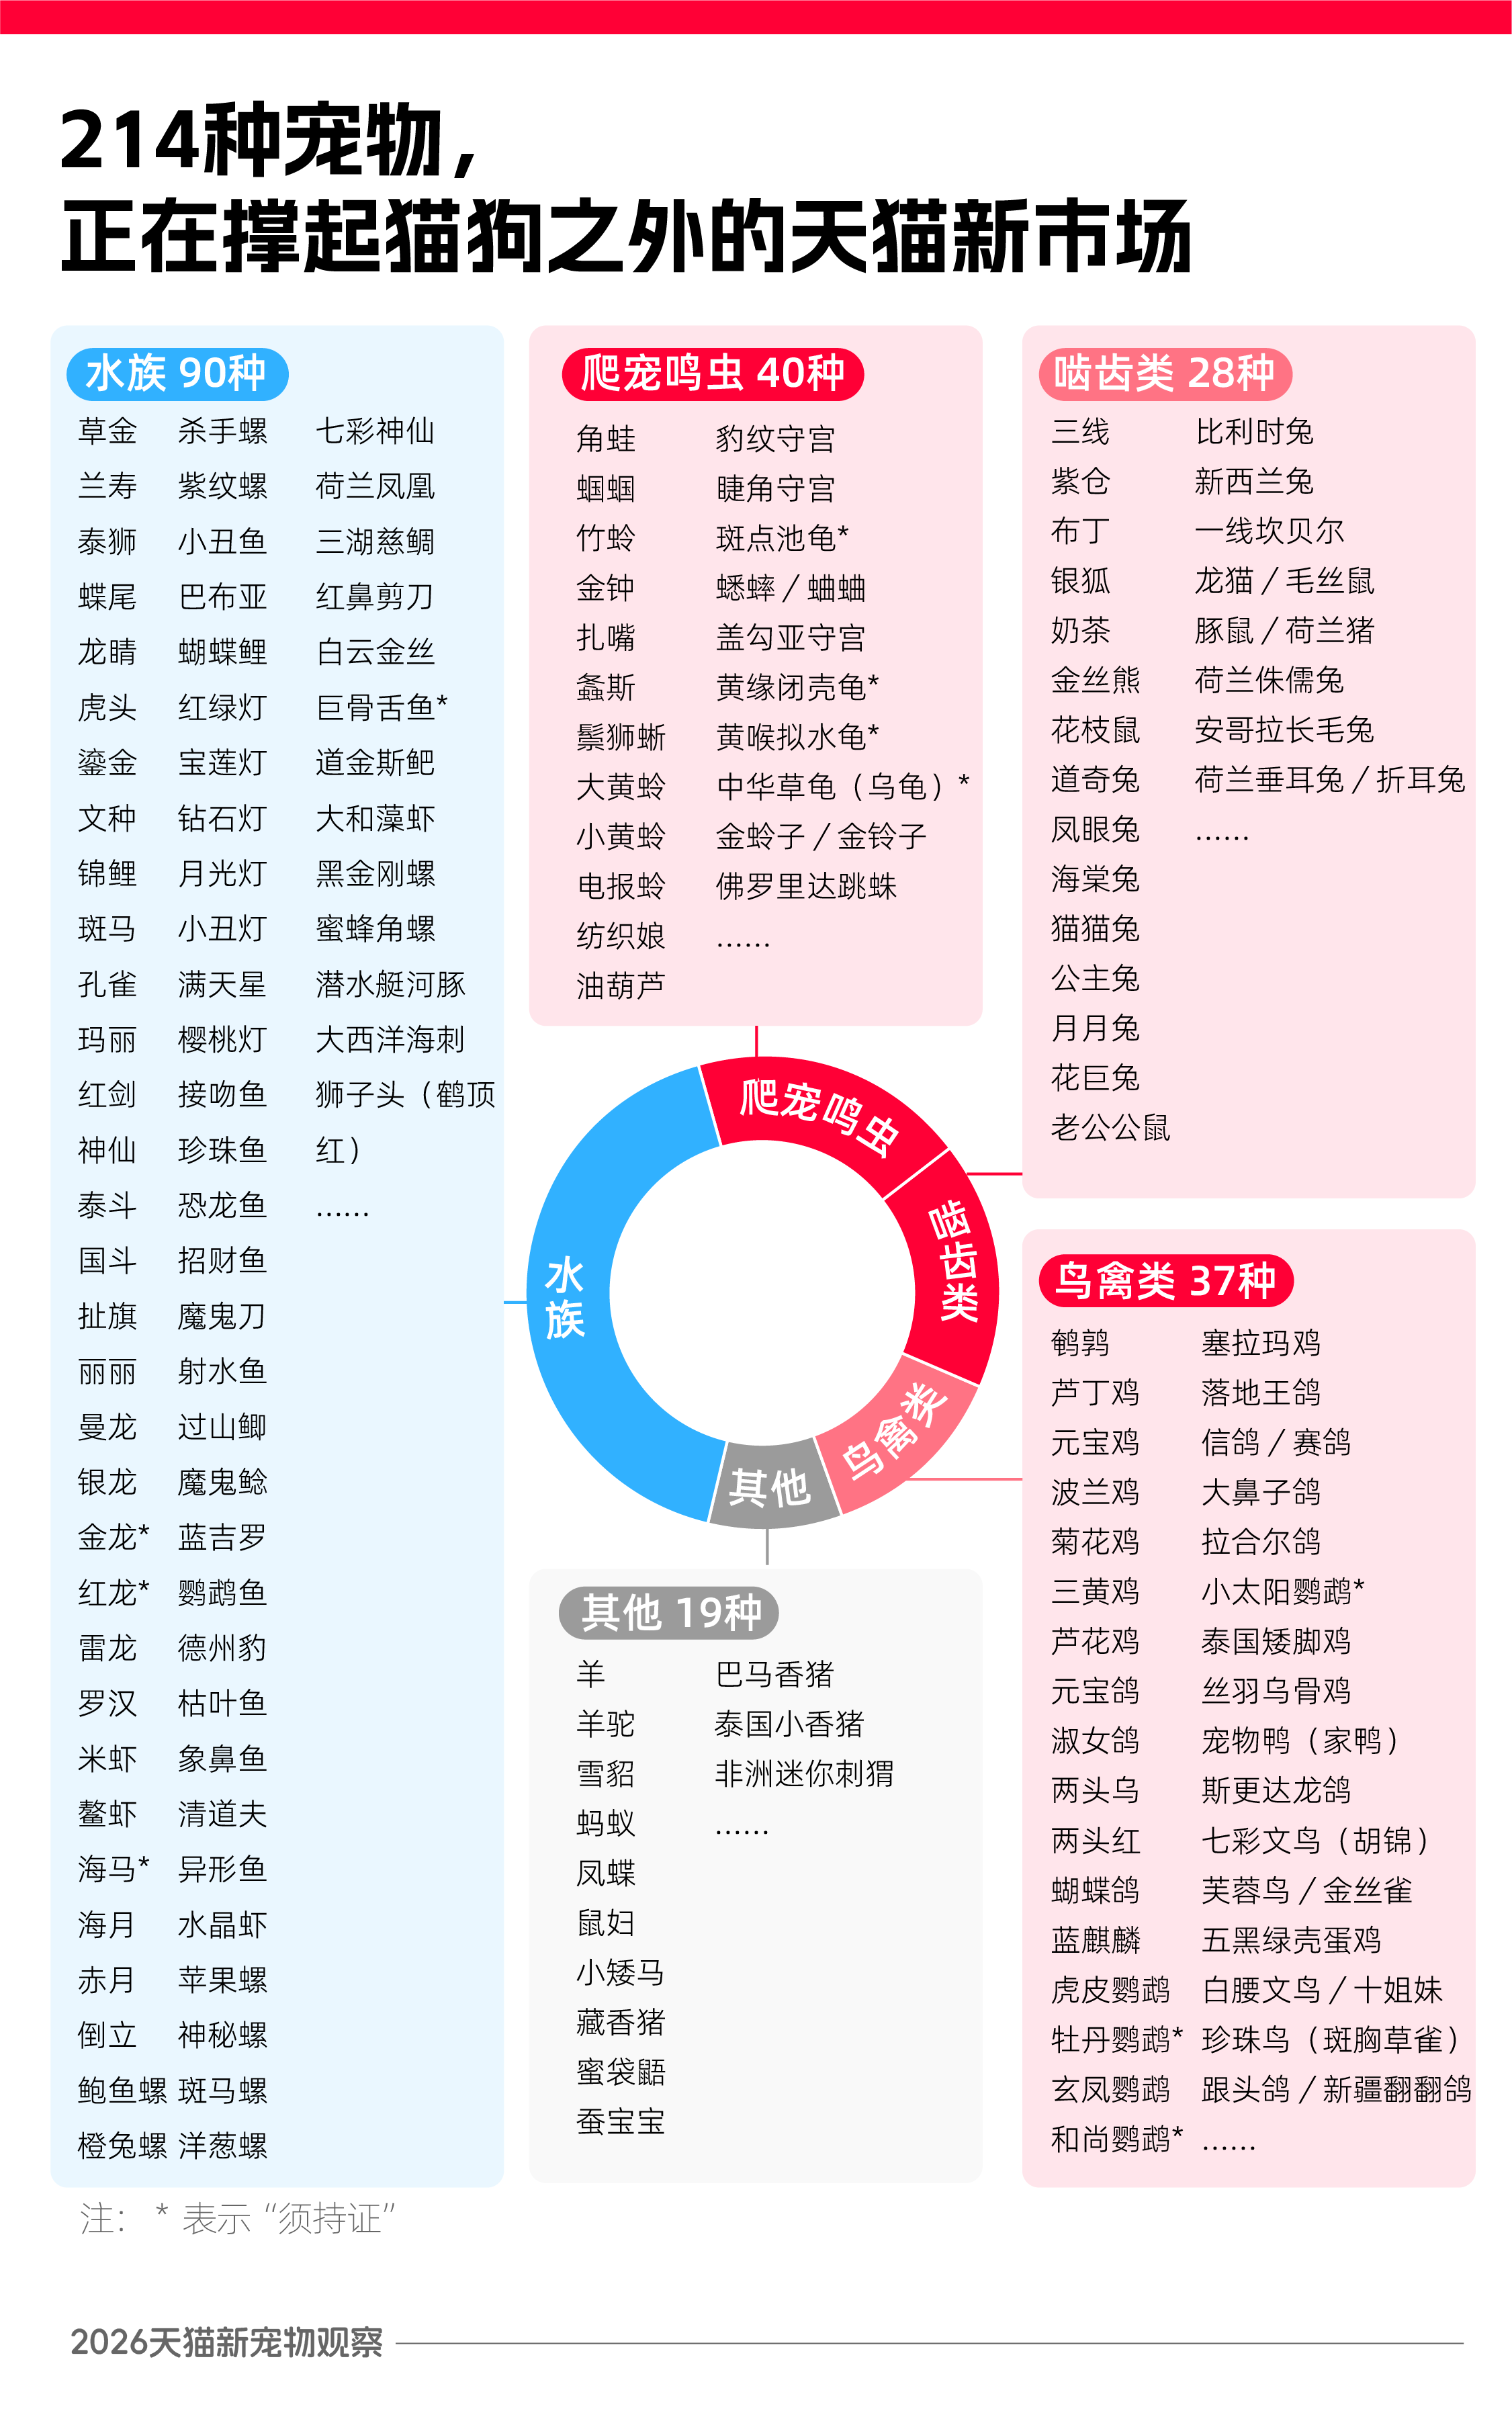
1. 核心市场认知:目前淘宝天猫平台上已经有214种非猫狗类动物被作为宠物饲养,涵盖90种水族、40种爬宠鸣虫、28种啮齿类、37种鸟禽类及19种其他类动物。这类宠物早已不是小众爱好,其中观赏鱼产业2022年产值突破百亿元,小宠市场2024年也跨过百亿门槛,是独立于猫狗宠物的成熟消费市场。

2. 实用饲养提示:新宠物饲养不能直接套用猫狗的用品采购逻辑,养鱼需要提前配齐鱼缸、过滤设备、灯具、恒温装置、造景物资;养爬宠要准备专用饲养箱、加热灯、UVB灯、温控设备;养鹦鹉的首笔核心支出是适配的鸟“房”也就是鸟笼,而非鸟粮。不同物种对居住环境、主粮、用品的需求差异极大,饲养前要针对性准备,避免错买通用款造成浪费。

这份新宠物消费报告展现的细分赛道格局与用户需求特征,可为宠物领域品牌的赛道布局、产品研发、渠道运营提供明确的方向参考。

1. 核心消费趋势:猫狗之外的新宠物市场已经形成独立规模,平台覆盖的214种非猫狗宠物对应着高度分散的消费需求,观赏鱼、小宠先后突破百亿产值,每类物种都有专属消费清单,需求难以被标准化产品满足,是宠物行业区别于传统猫狗赛道的确定性新增量。

2. 赛道切入机会:今年以来天猫平均每天新增1个非猫狗赛道宠物品牌,其中小宠赛道仍在快速洗牌期,过去一年TOP10品牌变动率达90%,新品牌可围绕单物种、细分刚需商品、专属饲养场景切入,有较大机会抢占头部位置;水族赛道头部格局趋稳,国产品牌已在鱼缸、过滤设备等核心品类建立规模优势,品牌可深挖垂直细分需求寻找切入点。

3. 用户决策特征:新宠物主的首笔预算往往优先投向饲养环境配套设备而非主粮,这类核心决策点可作为品牌产品研发、营销触达的重点方向。

这份报告披露的非猫狗宠物市场发展特征,能为线上宠物卖家指明增长方向与入局机会,规避经营误区。

1. 确定性增长空间:猫狗之外的新宠物已经成长出两个百亿级独立赛道,平台覆盖214种非猫狗宠物,对应海量细分消费需求,今年以来平均每天有1个新品牌在天猫入场,是避开猫狗赛道红海竞争的新增长领域。

2. 差异化经营机会:小宠赛道目前处于快速洗牌期,过去一年平台小宠类TOP10品牌变动率高达90%,即使已有先行品牌占位,卖家依然可以通过聚焦单一物种、一类刚需商品、特定饲养场景切入,有较大概率冲进头部序列;水族赛道头部格局趋稳,国产品牌在核心设备品类已有规模优势,卖家可布局细分补位类商品寻找生存空间。

3. 经营实操提示:新宠物消费不能照搬猫狗用品的组货、运营逻辑,不同物种对笼具、环境设备、主粮的需求差异极大,且消费者首单往往优先采购环境配套设备,卖家可围绕前置需求组货、搭建场景化商品链路,匹配用户真实决策路径。

这份天猫新宠物报告披露的细分需求与赛道格局,能为宠物供应链工厂指明产品开发方向,提供电商化布局的思路参考。

1. 清晰的产品设计与生产方向:非猫狗新宠物市场已形成百亿级规模,覆盖214种不同宠物,不同物种的需求差异极大、难以标准化,不存在直接套用缩小版猫狗用品就能满足需求的可能。其中养鱼用户需要适配的鱼缸、过滤设备、灯具、恒温装置、造景产品;爬宠饲养者需要专用饲养箱、加热灯、UVB灯、温控设备;养鸟用户首购核心是适配的鸟笼,这类专属配套设备都是明确的刚需品。

2. 商业合作机会:目前小宠赛道仍在快速洗牌,过去一年平台TOP10品牌变动率达90%,大量新品牌涌入,对柔性供应链、细分物种专属产品的需求旺盛,工厂可对接新品牌开发定向产品;水族赛道国产品牌已经站稳头部,在核心设备品类形成规模优势,工厂可依托产能优势承接规模化订单,同时拓展细分小品类补位市场。

这份报告展现的新宠物市场发展阶段与经营特征,能为宠物行业服务商找准服务方向、精准挖掘客户痛点提供参考。

1. 行业发展整体趋势:猫狗之外的新宠物已经成为宠物生态的核心新增量,目前平台覆盖214种非猫狗宠物,观赏鱼、小宠先后成长为百亿级独立市场,今年以来平均每天有1个新品牌入驻天猫开拓相关赛道,市场细分度还在持续提升。

2. 不同赛道的客户核心痛点:小宠赛道目前处于快速洗牌期,过去一年TOP10品牌变动率高达90%,新入局品牌普遍存在用户洞察不足、细分场景运营能力弱、爆品打造路径不清晰的痛点,且赛道内需求高度分散,不同物种的消费需求差异极大,品牌很难靠标准化方案突围;水族赛道头部品牌格局趋稳,国产品牌占据核心品类优势,存量品牌存在精细化运营、品类拓展、用户生命周期价值挖掘的需求。

3. 服务优化方向:服务商可针对小宠赛道客户推出细分物种的用户研究、场景化营销、爆品打造服务,针对水族赛道客户推出数字化用户运营、供应链优化服务,匹配不同阶段客户的真实需求。

这份天猫发布的新宠物观察,既展现了新宠物赛道的现有布局成果,也为平台后续的招商、运营管理、服务优化提供了方向参考。

1. 现有布局基础:目前平台已经覆盖214种非猫狗类宠物,涵盖水族、爬宠鸣虫、啮齿类、鸟禽类等多个大类,成功培育出观赏鱼、小宠两个百亿级独立消费市场,今年以来平均每天有1个非猫狗赛道的新品牌在平台诞生,新宠物已经成为平台宠物生态的重要新增量。

2. 招商与赛道运营方向:小宠赛道目前仍处于快速洗牌期,过去一年TOP10品牌变动率达90%,平台可针对性招引聚焦单一物种、细分饲养场景、专属刚需商品的特色商家,为新商家提供冷启动扶持,丰富赛道供给;水族赛道头部国产品牌已经趋稳,平台可重点扶持核心品类的国产品牌做大做强,同时招补细分特色品类商家补全供给。

3. 用户运营方向:新宠物消费需求高度细分,不同物种的配套商品差异极大,平台可细化品类导航、搭建场景化导购板块,帮助用户快速匹配对应物种的全链路商品,提升转化效率。

这份天猫发布的新宠物观察报告,为宠物产业研究提供了最新的市场动向、赛道特征与商业模式演化参考。

1. 产业发展新动向:国内宠物消费正在跳出猫狗为主的传统结构,目前淘宝天猫平台已经出现214种被家庭饲养的非猫狗类宠物,覆盖水族、爬宠鸣虫、啮齿类、鸟禽等大类,其中观赏鱼产业2022年产值突破百亿,小宠市场2024年迈过百亿门槛,两个独立于猫狗的百亿级新赛道已经成型,成为宠物产业的核心新增量。

2. 赛道演化新特征:新宠物市场的需求逻辑与传统猫狗市场存在明显差异,物种多样性带来了高度分散、难以标准化的需求,每一种新宠物进入家庭都会催生全新的专属购物清单,用户首笔消费往往优先投向环境配套设备而非主粮。从竞争格局看,小宠赛道仍处快速洗牌期,过去一年TOP10品牌变动率达90%;水族赛道则进入头部稳定期,国产品牌在核心品类建立起规模优势,不同细分赛道处于完全不同的发展阶段。

3. 商业模式启示:宠物行业的增长不再局限于把标准化商品卖给更多养宠用户,围绕新物种形成的全链路商品、服务布局,会持续催生更多细分商业机会。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

The *2026 Tmall Emerging Pet Report* provides a comprehensive overview of the non-cat and non-dog pet market, as well as practical guidance for preparing to care for these animals.

1. Core market context: There are currently 214 non-cat/dog species kept as pets on Taobao and Tmall, spanning 90 aquatic species, 40 reptile and singing insect species, 28 rodent species, 37 bird species, and 19 other species. Far from a niche hobby, the ornamental fish industry surpassed RMB 10 billion in output value in 2022, while the small pet market crossed the same threshold in 2024, forming a mature consumer segment separate from the traditional cat and dog market.

2. Practical care tips: Owning these emerging pets requires a different approach to supply shopping than that used for cats and dogs. Fish owners need to prepare a fish tank, filtration system, lighting, temperature control devices, and aquascaping materials in advance; reptile owners require specialized enclosures, heat lamps, UVB lamps, and temperature control equipment; for parrot owners, the first core purchase is a suitable cage (the bird’s "home") rather than bird food. Each species has vastly different requirements for housing, staple food, and supplies, so prospective owners should make targeted preparations ahead of time to avoid wasting money on generic products.

This emerging pet consumption report outlines the segment landscape and user demand characteristics, providing clear directional guidance for pet brands on segment positioning, product R&D, and channel operations.

1. Core consumption trends: The non-cat/dog pet market has reached independent scale, with 214 species on the platform corresponding to highly fragmented consumer demands. Both the ornamental fish and small pet segments have exceeded RMB 10 billion in output value, and each species has its own dedicated purchase list, with demands that are difficult to meet with standardized products. This makes the segment a reliable growth driver for the pet industry, distinct from the traditional cat and dog track.

2. Segment entry opportunities: Since the start of the year, Tmall has seen an average of one new non-cat/dog pet brand launch per day. The small pet segment remains in a period of rapid reshuffling, with a 90% turnover rate among the top 10 brands over the past year. New brands can target single species, high-demand niche products, or species-specific care scenarios to gain a strong chance of capturing top positions. The aquatic segment, meanwhile, has a more stable leading landscape, with domestic brands already holding scale advantages in core categories such as fish tanks and filtration equipment; brands here can identify entry points by tapping into deep vertical niche demands.

3. User decision-making traits: First-time owners of emerging pets typically allocate their initial budget to habitat setup equipment rather than staple food, making this core decision point a key priority for product development and marketing outreach.

This report’s findings on non-cat/dog pet market development point out growth directions, entry opportunities, and operational pitfalls for online pet sellers.

1. Reliable growth potential: The non-cat/dog pet category has spawned two independent RMB 10 billion segments, with 214 species on the platform corresponding to massive niche consumer demand. An average of one new brand has entered the category on Tmall per day since the start of the year, making it a new growth area free from the red-hot competition of the cat and dog track.

2. Differentiated operation opportunities: The small pet segment is currently in a rapid reshuffling phase, with a 90% turnover rate among the platform’s top 10 small pet brands over the past year. Even with early movers holding market share, sellers can still break into the top ranks by focusing on single species, one category of high-demand staple products, or specific care scenarios. The aquatic segment has a more stable leading landscape, with domestic brands holding scale advantages in core equipment categories; here, sellers can carve out space by offering niche complementary products.

3. Practical operational tips: Selling emerging pet supplies cannot replicate the stocking and operational logic used for cat and dog products. Different species have vastly different requirements for enclosures, habitat equipment, and staple food, and consumers typically purchase habitat setup equipment first. Sellers should stock products around these pre-purchase needs and build scenario-based product links to align with users’ actual decision-making paths.

This Tmall emerging pet report’s insights into niche demands and segment structure provide pet supply chain factories with clear direction for product development and e-commerce-oriented layout.

1. Clear product design and production priorities: The non-cat/dog emerging pet market has reached RMB 10 billion in scale, covering 214 species with highly divergent, hard-to-standardize demands—simply downsizing cat and dog products will not meet these needs. Fish owners require species-appropriate tanks, filtration systems, lighting, temperature control devices, and aquascaping products; reptile keepers need specialized enclosures, heat lamps, UVB lamps, and temperature control equipment; bird owners’ core first purchase is a suitable cage, and all of these dedicated habitat supplies are confirmed high-demand staples.

2. Business partnership opportunities: The small pet segment remains in rapid reshuffling, with a 90% turnover rate among the platform’s top 10 brands over the past year. A flood of new brands is creating strong demand for flexible supply chains and species-specific niche products, creating openings for factories to partner with new brands to develop targeted products. In the aquatic segment, domestic brands have secured leading positions and built scale advantages in core equipment categories, so factories can leverage their production capacity to take on large-scale orders while expanding into complementary niche product markets.

This report’s overview of the emerging pet market’s development stage and operational traits helps pet industry service providers identify service directions and accurately address client pain points.

1. Overall industry trends: Non-cat/dog emerging pets have become a core growth driver in the pet ecosystem. The platform currently covers 214 non-cat/dog pet species, the ornamental fish and small pet segments have each grown into independent RMB 10 billion markets, an average of one new brand has joined Tmall to enter the track per day since the start of the year, and market segmentation continues to deepen.

2. Core client pain points across segments: The small pet track is in a rapid reshuffling phase, with a 90% turnover rate among the top 10 brands over the past year. New entrants to the segment commonly face pain points including insufficient user insights, weak ability to operate niche scenarios, and unclear paths to building hit products. Demand in the segment is also highly fragmented, with vast differences in consumption needs across species, making it difficult for brands to break through with standardized solutions. The aquatic segment has a more stable leading brand structure, with domestic brands holding advantages in core categories; existing brands here have demand for refined operations, category expansion, and user lifetime value optimization.

3. Service optimization directions: Service providers can offer small pet segment clients user research for specific species, scenario-based marketing, and hit product development services, while providing aquatic segment clients with digital user operations and supply chain optimization services to meet the real needs of clients at different development stages.

This emerging pet observation released by Tmall showcases the existing achievements of the emerging pet segment while providing directional guidance for the platform’s future merchant recruitment, operation management, and service optimization.

1. Existing layout foundation: The platform currently covers 214 non-cat/dog pet species across major categories including aquatic pets, reptiles and singing insects, rodents, and birds. It has successfully cultivated two independent RMB 10 billion consumer segments—ornamental fish and small pets—and an average of one new non-cat/dog pet brand has launched on the platform per day since the start of the year, making emerging pets a key growth driver for the platform’s pet ecosystem.

2. Merchant recruitment and segment operation directions: The small pet segment remains in a rapid reshuffling phase, with a 90% turnover rate among the top 10 brands over the past year. The platform can target recruitment of specialty merchants focused on single species, niche care scenarios, and species-specific high-demand products, providing cold-start support for new merchants to diversify segment supply. In the aquatic segment, leading domestic brands have reached relative stability; the platform can focus on supporting domestic brands in core categories to expand their scale, while recruiting merchants in specialty niche categories to fill supply gaps.

3. User operation directions: Emerging pet consumption demands are highly segmented, with large differences in supporting supplies across species. The platform can refine category navigation and build scenario-based shopping guide sections to help users quickly find full-funnel products for their specific pet, improving conversion efficiency.

This emerging pet observation report released by Tmall provides the latest market trends, segment characteristics, and business model evolution references for pet industry research.

1. New industry development trends: Domestic pet consumption is moving beyond its traditional cat- and dog-dominated structure. There are currently 214 non-cat/dog species kept as household pets on Taobao and Tmall, covering aquatic pets, reptiles and singing insects, rodents, and birds. Among these, the ornamental fish industry surpassed RMB 10 billion in output value in 2022, while the small pet market crossed the same threshold in 2024. Two new RMB 10 billion segments independent of the cat and dog market have taken shape, becoming a core growth driver for the pet industry.

2. New segment evolution traits: The demand logic of the emerging pet market differs significantly from that of the traditional cat and dog market. Species diversity creates highly fragmented, hard-to-standardize demand; the entry of each new pet species into households spawns an entirely new dedicated shopping list, and users typically spend their first budget on habitat setup equipment rather than staple food. In terms of competitive landscape, the small pet segment remains in a period of rapid reshuffling, with a 90% turnover rate among the top 10 brands over the past year. The aquatic segment, by contrast, has entered a stage of stable leadership, with domestic brands building scale advantages in core categories, placing different niche segments at entirely different development stages.

3. Business model implications: Growth in the pet industry is no longer limited to selling standardized products to more pet owners. Full-funnel product and service layouts built around new species will continue to spawn more niche business opportunities.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

谁说宠物只有猫和狗?

9月16日,天猫发布《2026天猫新宠物观察》,第一次把猫狗之外的宠物消费放进一张完整的版图。

报告显示,目前在淘宝天猫上已经有214种新的动物被当成宠物饲养——覆盖水族90种、爬宠鸣虫40种、啮齿类28种、鸟禽类37种及其他动物19种。它们不是猫狗市场的边角料,而是天猫宠物生态不断长出的新增量。

从小众饲养到百亿市场,每一种宠物都会带来一张新的购物清单

过去几年,小宠、水族逐渐从少数人的兴趣爱好,成长为猫狗之外两个独立发展的宠物市场。农业农村部公开数据显示,国内观赏鱼产业产值于2022年突破100亿元,小宠市场在2024年跨过同一门槛。猫狗之外已跑出两个百亿级独立市场。

但这两门生意,并不是把猫狗用品缩小一号就能做。

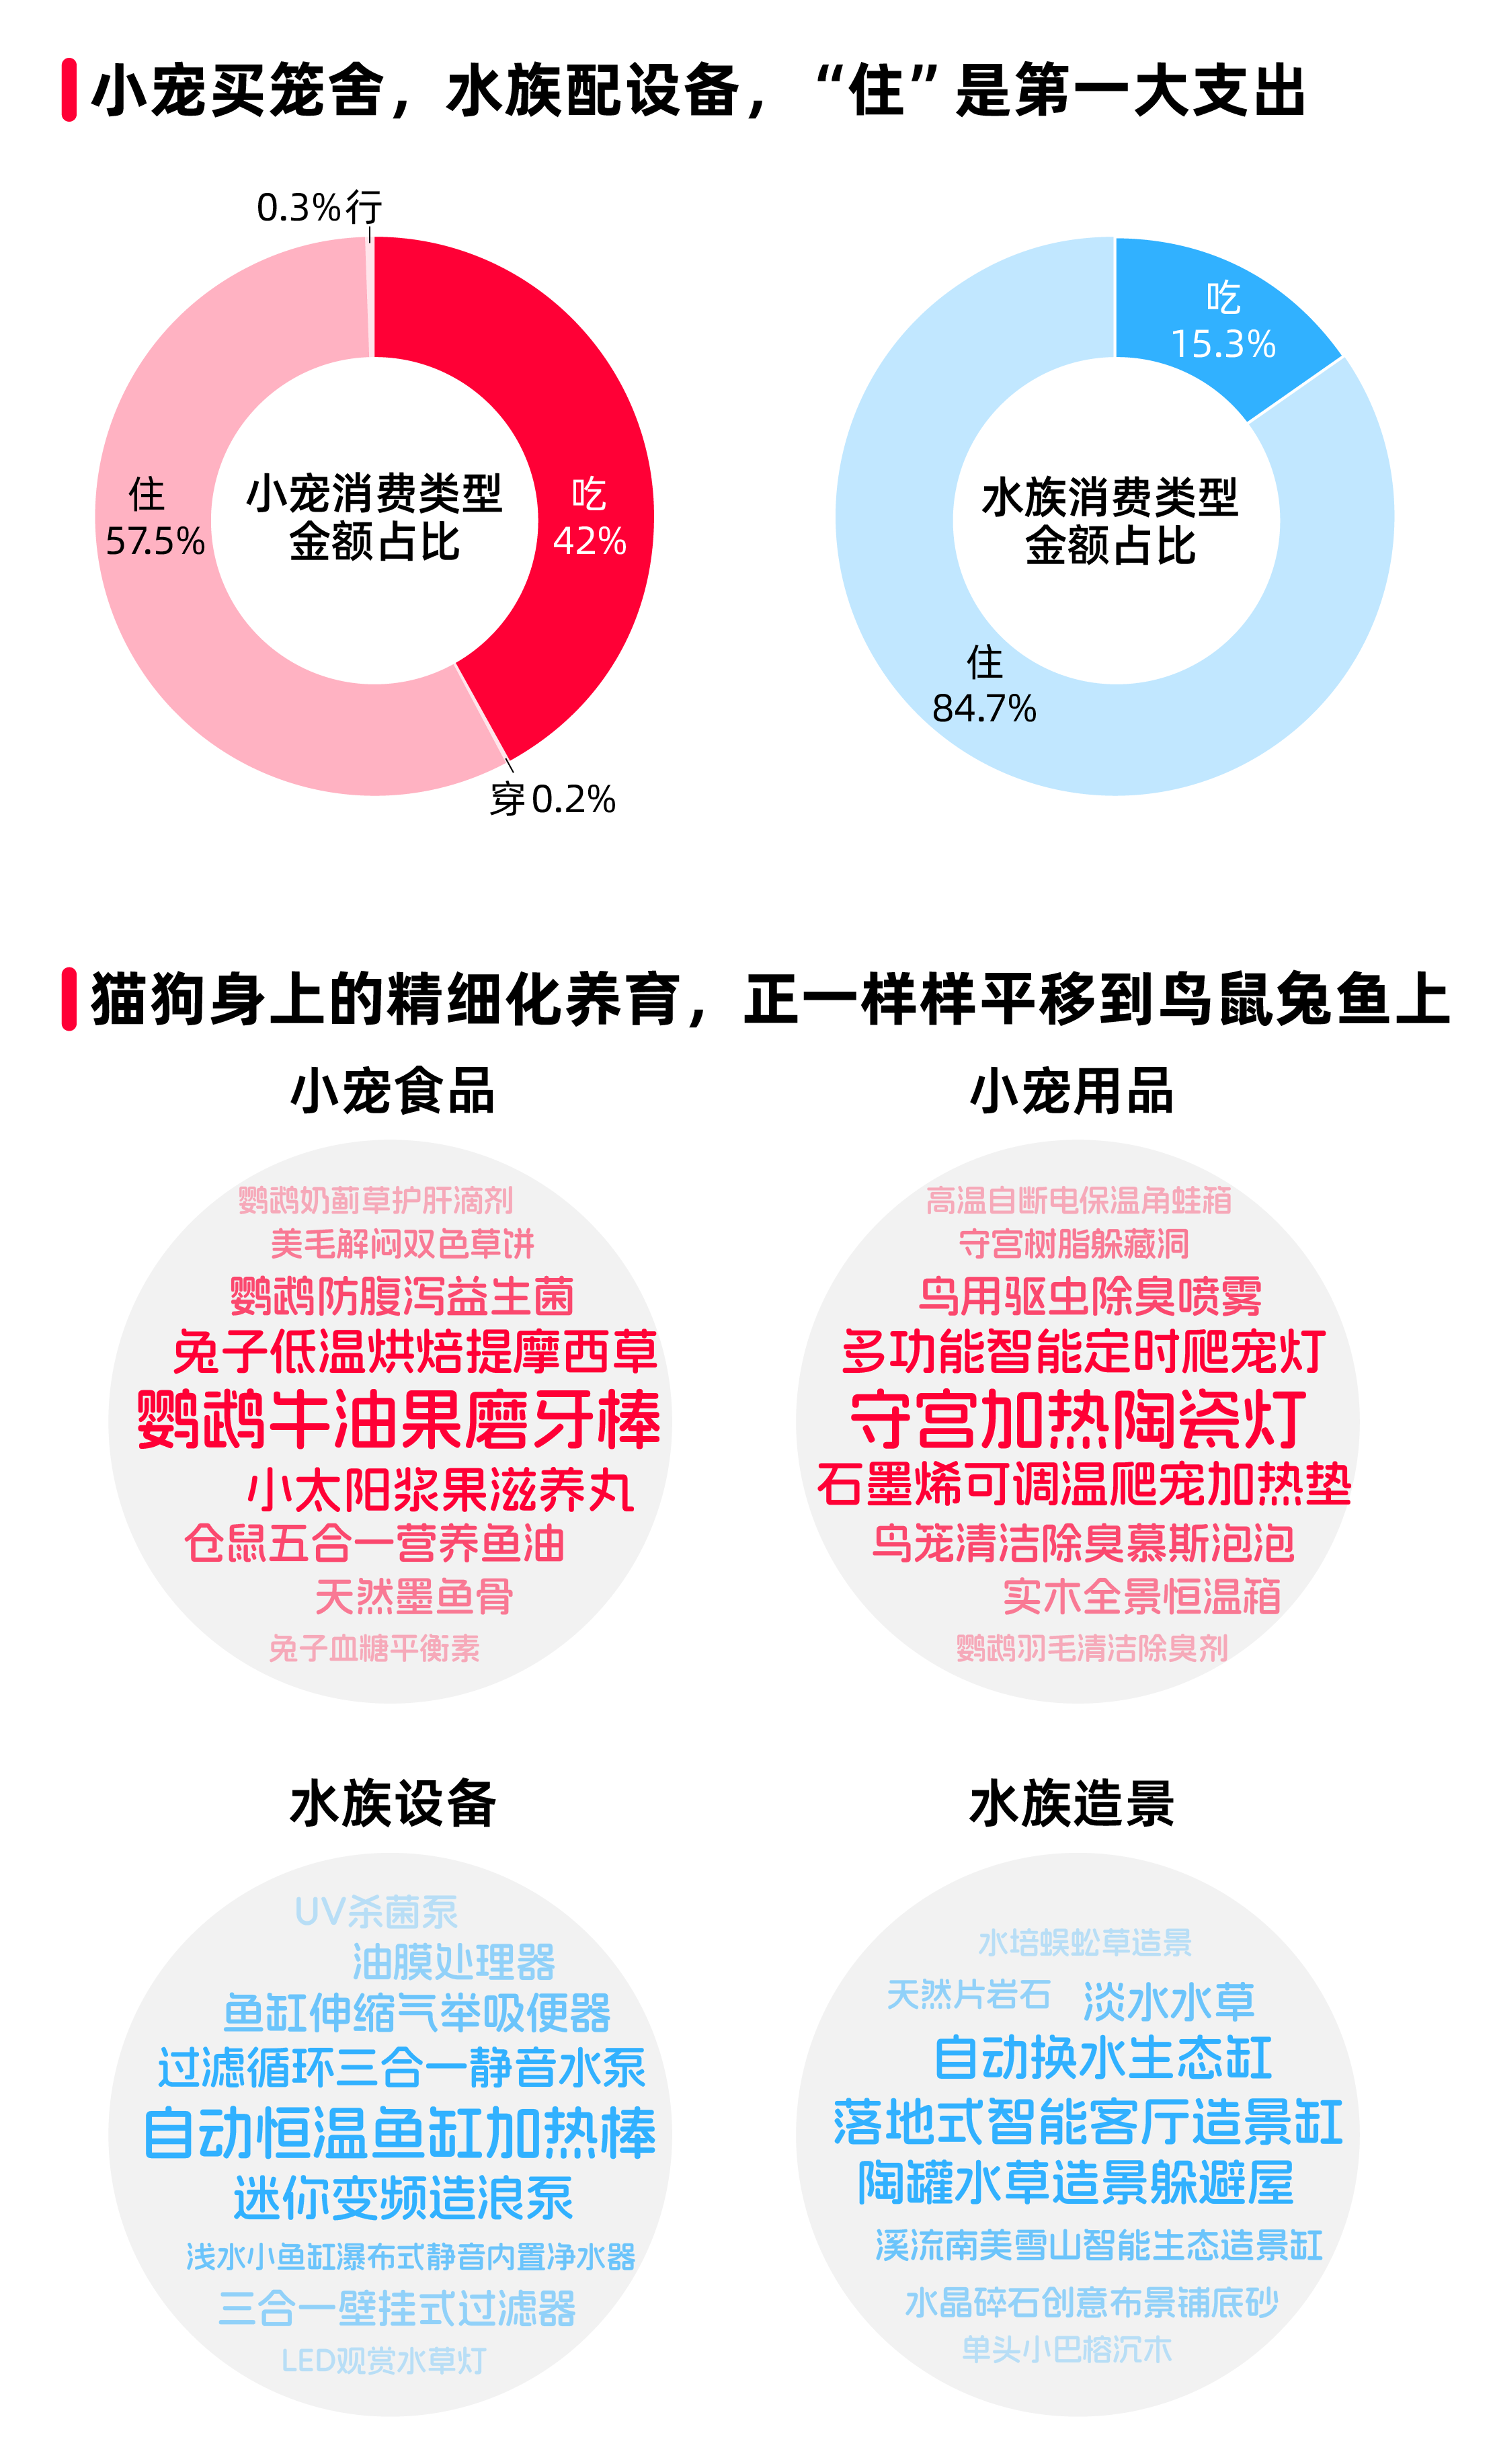
养鱼之前,要先准备鱼缸、过滤、灯具、恒温设备和造景;养爬宠,需要饲养箱、加热灯、UVB灯和温控设备;而决定一位鹦鹉主人首笔预算的,常常不是鸟粮,而是鹦鹉住的那间"房"。

这也是新宠物市场和传统猫狗市场明显不同的地方:物种越多,需求越难标准化:鱼需要水环境,鸟需要垂直空间,爬宠对温度和光照敏感,仓鼠、兔子甚至不同鸟种之间,对主粮、笼具和用品的需求都不完全相同。每多一种宠物进入家庭,都可能重新产生一张购物清单。

平均每天1个新品牌,宠物生意机会正在越拆越细

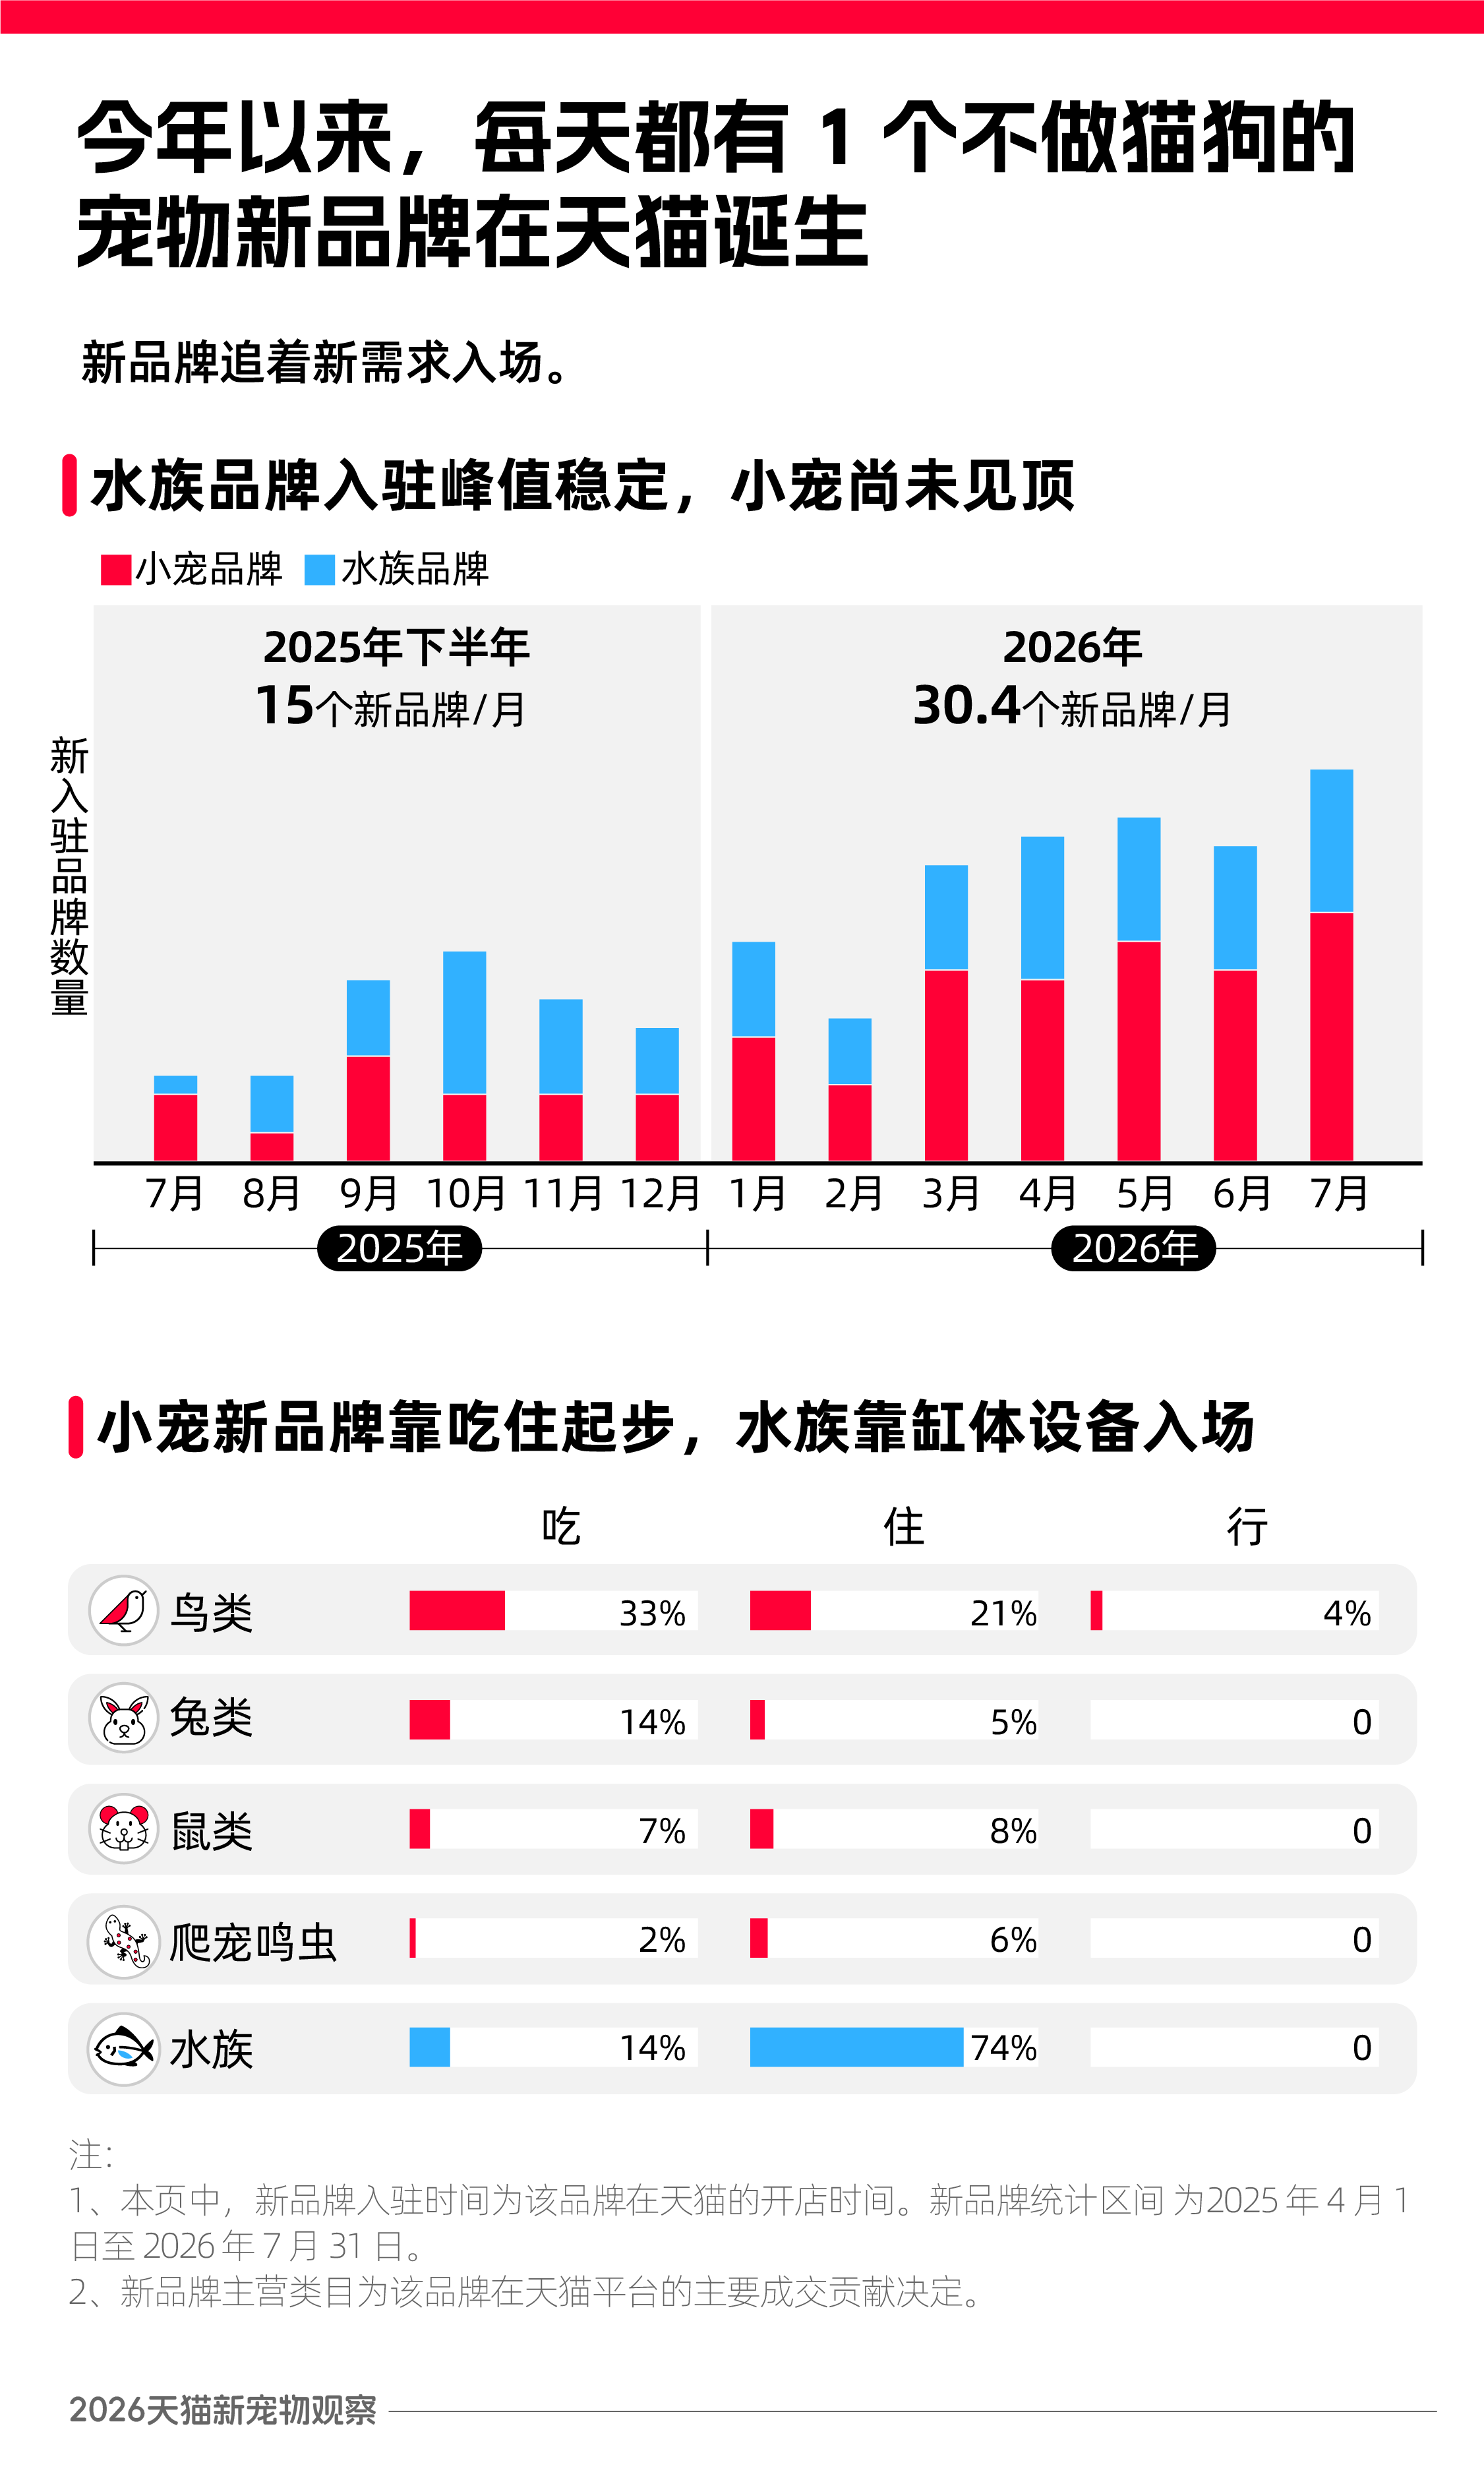
越来越多新品牌追着新需求入场。报告显示,今年以来,平均每天都有1个猫狗赛道之外的宠物新品牌在天猫诞生。

但如果把小宠和水族拆开看,两条赛道已经呈现出不同的竞争阶段。

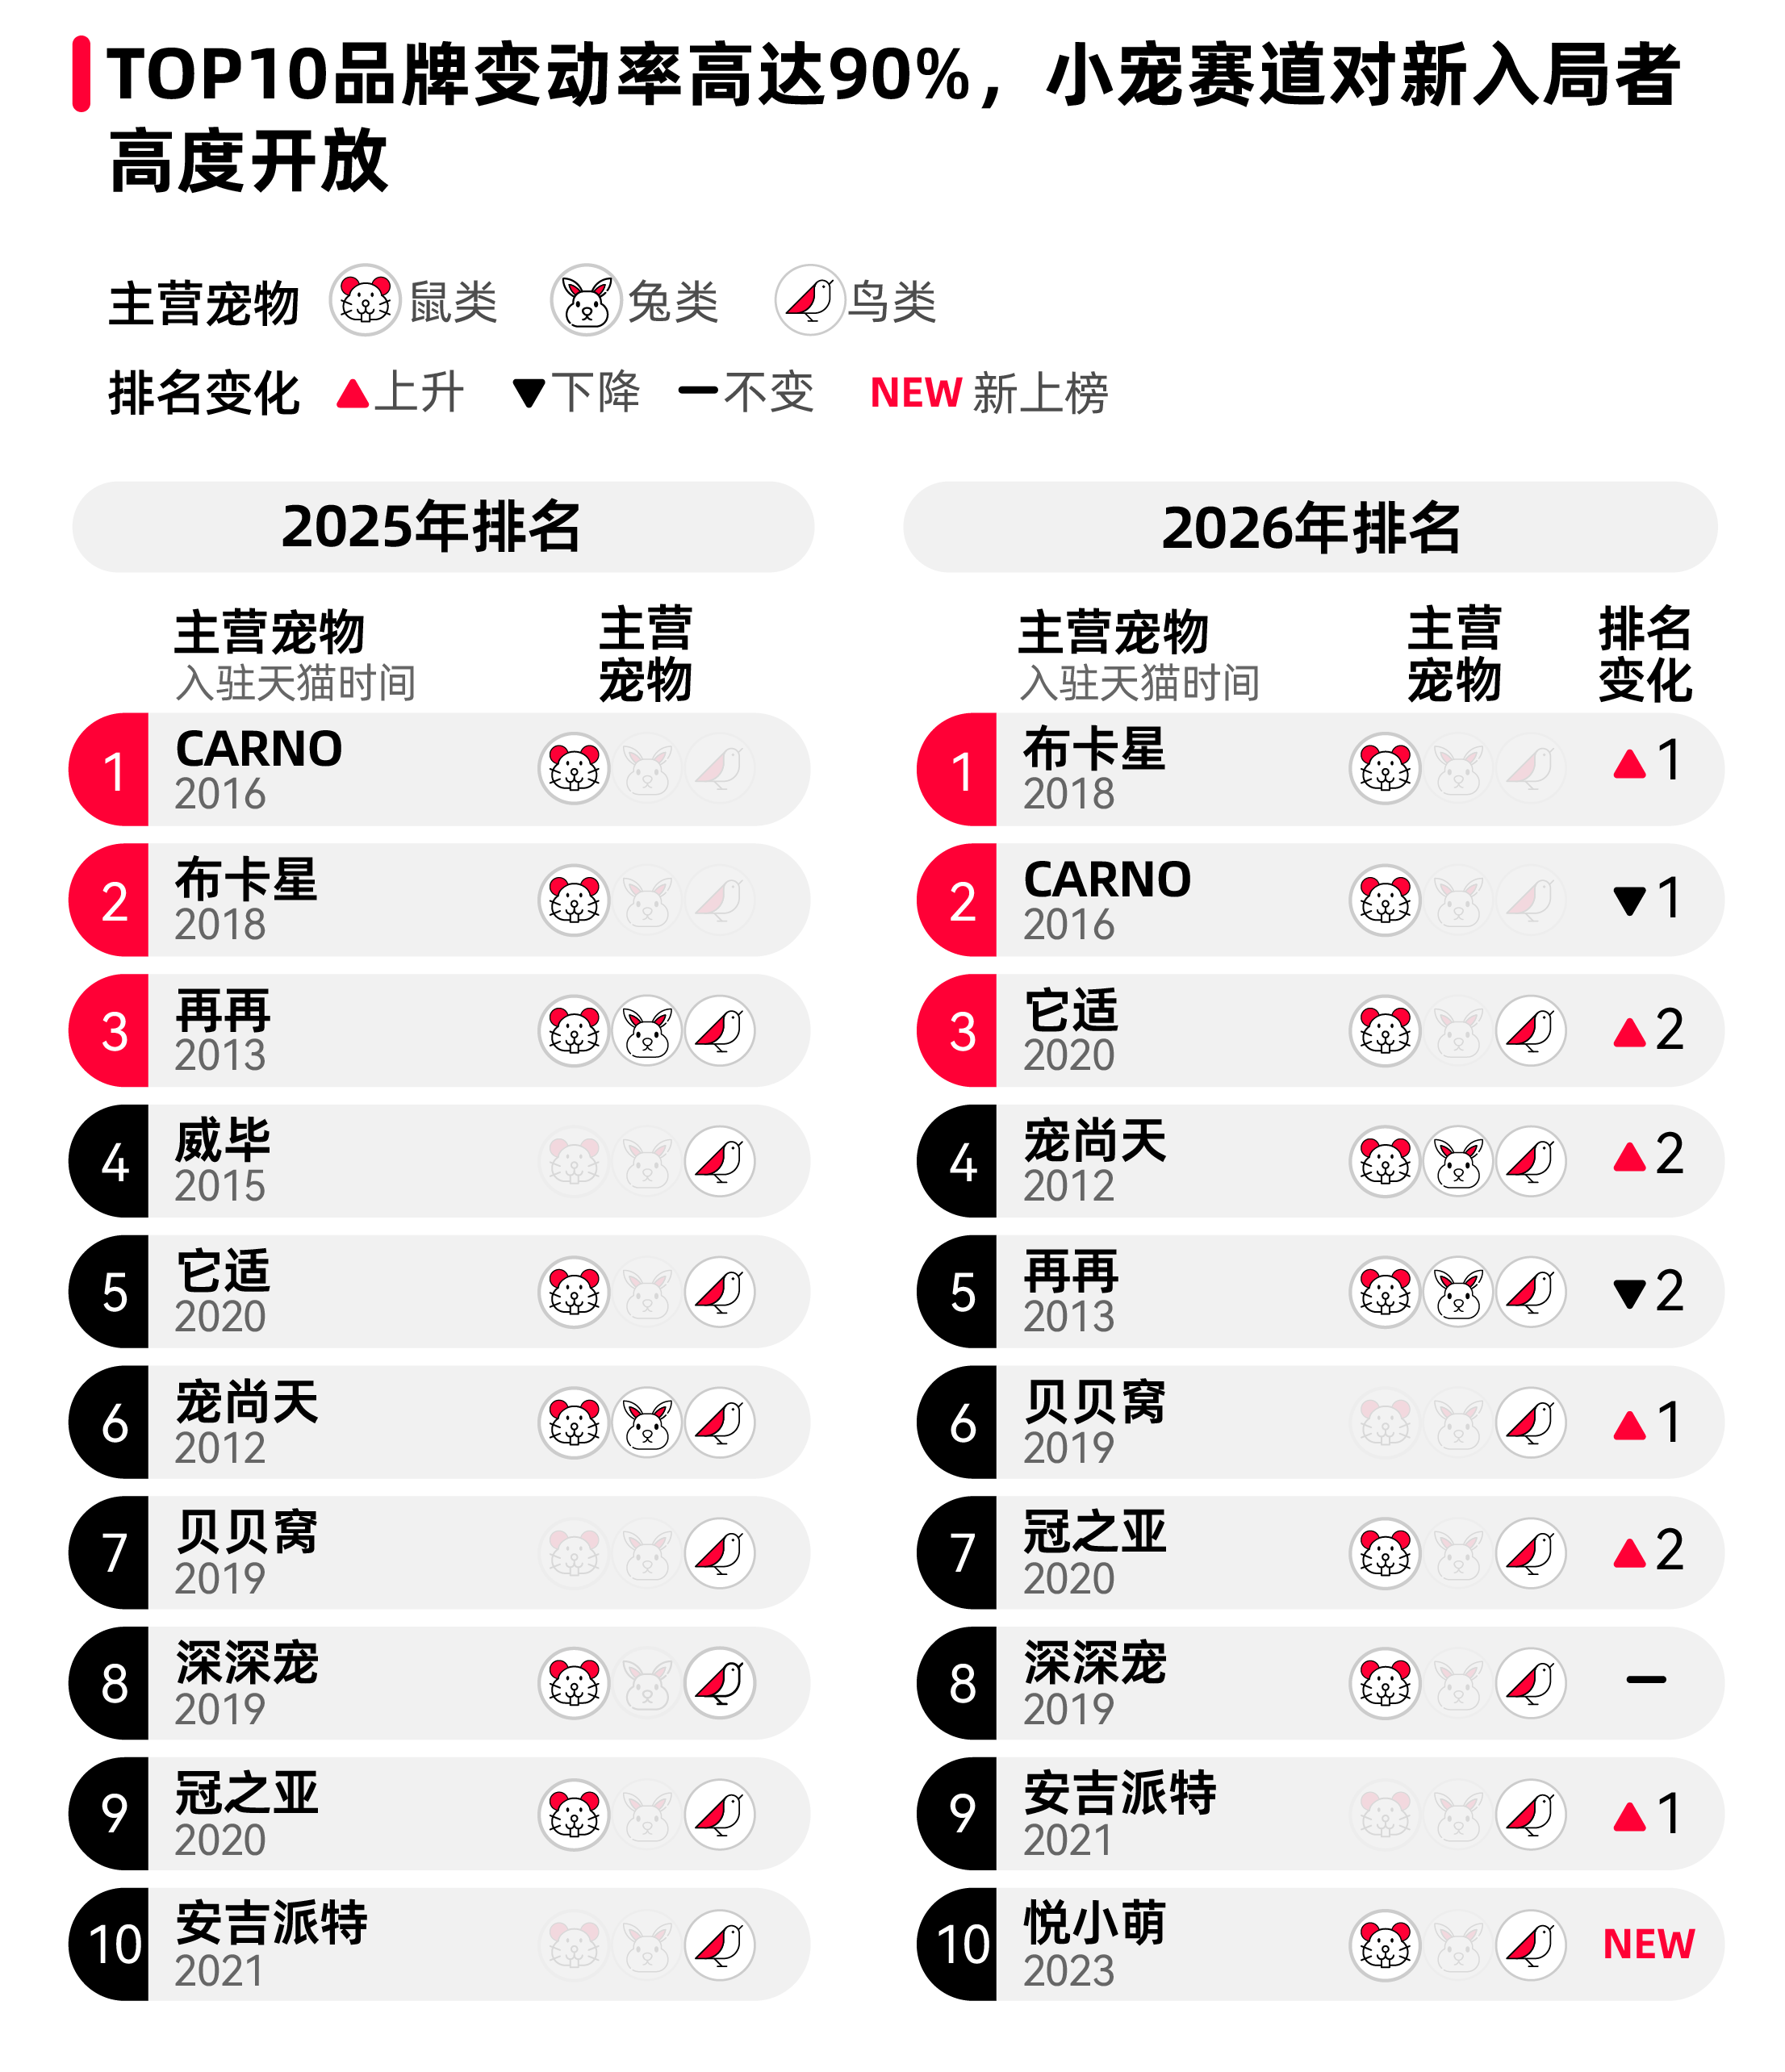
小宠仍处在快速洗牌期。如果按成交金额排序,过去一年里,天猫上小宠赛道TOP10品牌的变动率高达90%。这意味着,即使已经有一批品牌跑在前面,新入局者依然有机会凭借一个物种、一类商品或一个新的饲养场景进入头部序列。

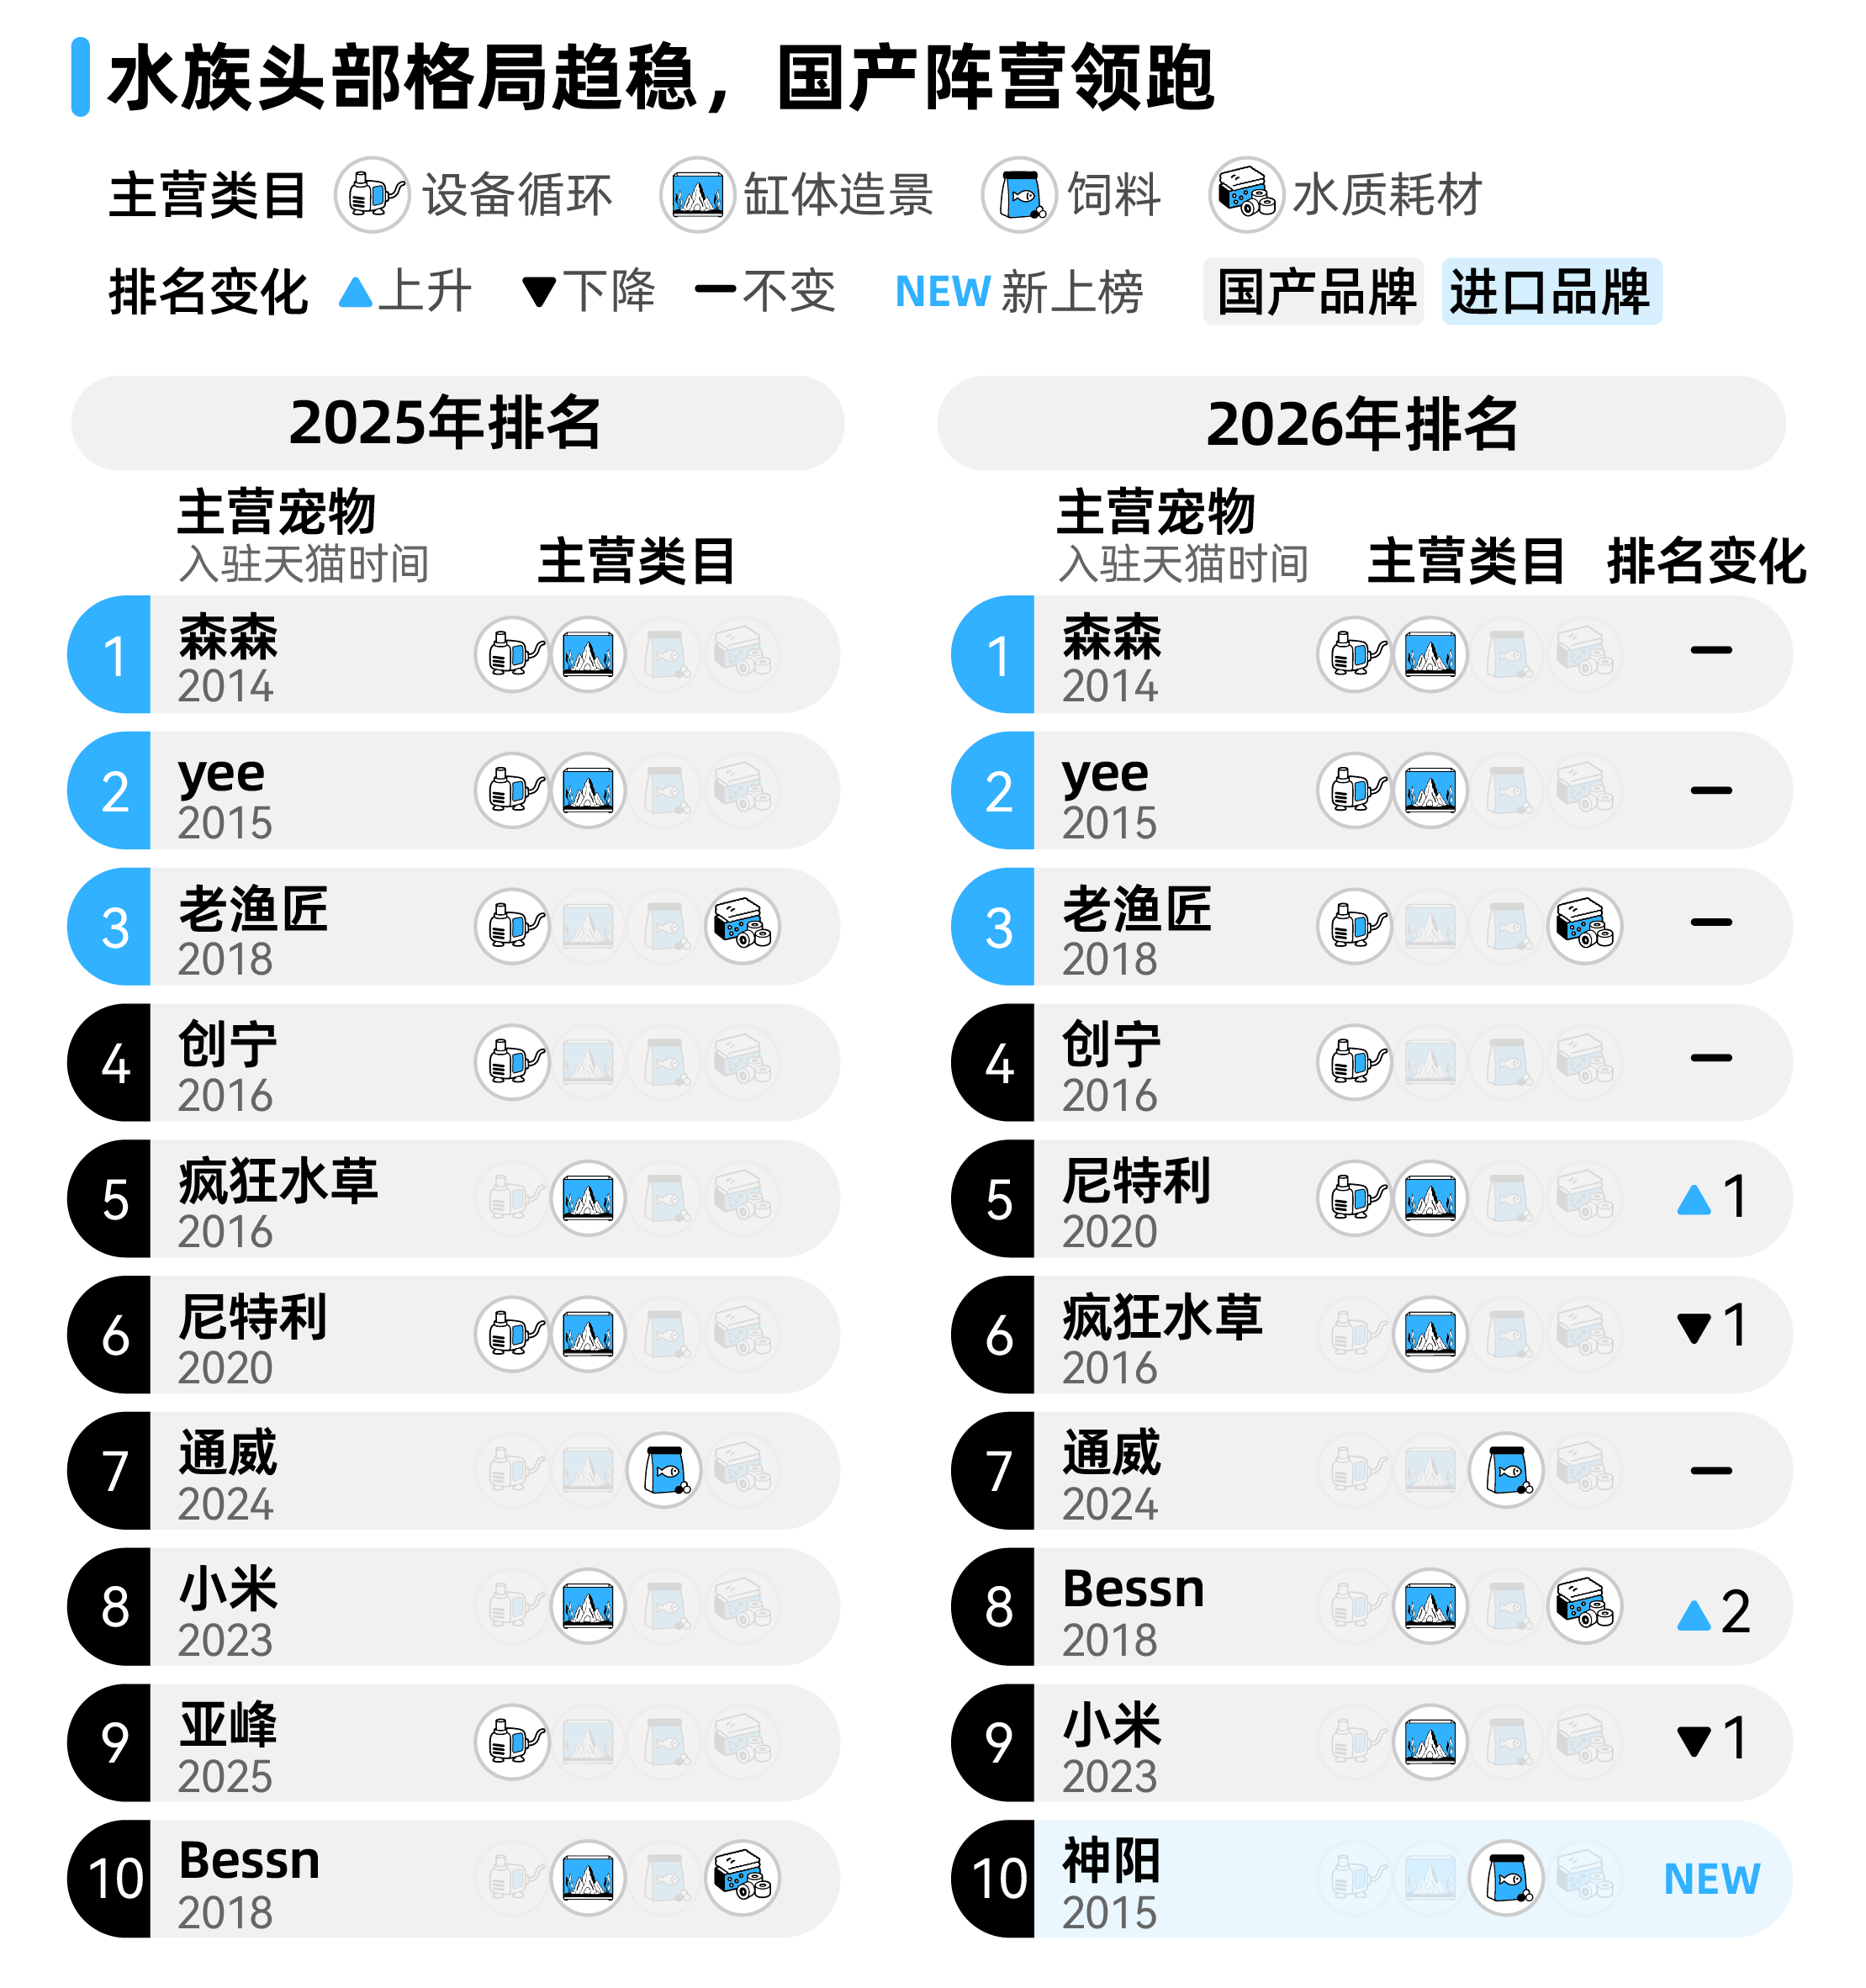
相比小宠频繁更替的品牌格局,水族头部品牌已经明显趋稳,一批国产品牌逐渐占据领先位置。从鱼缸、过滤设备,到灯具、水泵、水草造景,国内品牌已经在多个核心品类建立起规模优势。

一边是头部仍在不断换人的小宠市场,一边是国产阵营开始站稳的水族市场,宠物生意已经不再只是一个笼统的“新赛道”,而是进入了不同的发展阶段。

猫狗市场曾经证明了一件事:当一种动物变成家庭成员,围绕它的食品、用品、健康和服务,都会成为一门新生意。如今,同样的过程正在鹦鹉、仓鼠、兔子、鱼和爬宠身上发生。

从214种宠物到百亿级市场,再到不断涌入的新品牌,猫狗之外的宠物消费正在持续细分,催生出全新的生意机会。对宠物行业而言,新的增长未必只来自把同一种商品卖给更多人——也可能来自又一种动物被认真地当作家人。

注:文/龚作仁,文章来源:Laborer,本文为作者独立观点,不代表亿邦动力立场。

文章来源:Laborer

广告
微信
朋友圈

FAQ回顾

国内猫狗之外的新宠物市场规模有多大?

目前淘宝天猫平台覆盖的非猫狗类宠物已达214种,涵盖水族、爬宠鸣虫、啮齿类、鸟禽类等品类。据农业农村部公开数据,国内观赏鱼产业2022年产值突破100亿元,小宠市场2024年规模跨过百亿门槛,猫狗之外已形成两个百亿级独立消费市场。

新宠物消费和传统猫狗宠物市场的核心差异是什么?

核心差异是新宠物市场需求难以标准化,不同物种的饲养需求差异极大:水族需要鱼缸、过滤、恒温等水环境配套设备,爬宠对温度光照敏感,鸟类需要垂直活动空间,每新增一类宠物入户,都会衍生出全新的专属消费清单。

天猫平台上新宠物赛道的品牌竞争格局是怎样的?

今年以来,平均每天有1个猫狗赛道之外的宠物新品牌在天猫诞生。其中小宠赛道仍处快速洗牌期,过去一年赛道TOP10品牌变动率高达90%,新品牌仍有突围机会;水族赛道头部品牌格局趋稳,国产品牌已在多个核心品类建立规模优势。

这么好看,分享一下?

朋友圈 分享

APP内打开

赞 +1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0