广告
加载中

净利润大涨56%、研发投入翻倍增长 绿联科技半年报表现亮眼

王昱 2026-09-05 19:17
王昱 2026/09/05 19:17

邦小白快读

EN
全文速览

本文披露了绿联科技2026年半年报核心信息,核心干货内容整理如下:

1. 核心业绩表现:2026上半年绿联科技实现营业收入58.21亿元,同比增长50.92%,归母净利润4.31亿元,同比增长56.90%,三项核心指标增速创下上市以来新高。财报发布后股价大涨超10%,当前市盈率回落至27上下,进入和同业一致的合理区间。

2. 业务增长亮点:三大传统品类均保持40%以上增速,全品类毛利率提升至39.18%;NAS作为第二增长曲线营收同比大增85.53%,2025年已拿下消费级NAS出货量、零售额双料冠军;跨境业务增速69.42%,占总营收超六成,线下营收同比大涨65.31%,已进驻全球多家知名线下零售渠道;研发投入同比翻倍,累计持有专利超2500项,持续推出多款智能化新品。

本文披露的绿联科技增长经验,对消费电子品牌商有多方面干货参考,具体如下:

1. 业务布局层面:抓住AI赋能消费电子的消费趋势,打造第二增长曲线,绿联将智能存储NAS定为第二增长曲线后,该业务增速超85%,2025年超越一众国际老牌品牌拿到消费级NAS双料冠军,同时稳固传统业务基本盘,通过成本管控实现全品类毛利率上涨,盈利能力持续提升。

2. 渠道建设层面:坚持长板更长、多点开花的渠道策略,深耕核心渠道亚马逊放大优势,该渠道营收占比近四成,增速超71%;同时积极拓展多渠道,线下渠道增速达65.31%,成功进驻全球多家知名线下零售巨头,境外收入占比提升至66.79%,成为增长核心动力。

3. 竞争策略层面:持续加码研发投入,上半年研发投入同比翻倍,连续两年保持高增长,积累专利构建技术壁垒,围绕不同用户需求推出智能化新品,持续丰富产品矩阵,加固品牌护城河。

绿联科技半年报透露出3C消费电子领域的最新市场变化与机会,可供3C卖家参考的干货整理如下:

1. 市场增长机会:AI赋能的消费级智能存储是当前高速增长的蓝海赛道,绿联该业务增速达85.53%;海外市场整体增速69.42%,远高于国内市场的23.46%,已经成为品牌增长核心动力,线下渠道当前增长空间较大,绿联线下营收增速达65.31%,新兴小平台和独立站也实现近60%的增长。

2. 可借鉴的发展路径:深耕核心优势渠道放大长板,亚马逊渠道优势持续扩大,同时多渠道布局分散风险,抓住不同渠道的增量;持续加大研发投入,通过技术赋能打造差异化产品,提升产品毛利率,构建自身竞争壁垒。

3. 风险提示:消费电子赛道资本市场波动较大,市盈率过高脱离业绩支撑会出现泡沫回调,卖家需要关注估值与业绩的匹配度,避免过度投机。

绿联科技半年报展现了当前消费电子行业的产品需求与发展方向,对3C工厂的干货启示整理如下:

1. 产品生产设计需求:当前市场对AI赋能的智能化消费电子需求旺盛,尤其是智能存储NAS赛道增长极快,产品需要覆盖从家庭入门级到专业旗舰级的全档位矩阵,针对普通家庭、专业创作者、中小型团队等不同群体的需求开发对应功能,要搭载本地AI功能满足用户智能存储需求。

2. 可挖掘的商业机会:绿联作为快速增长的本土3C品牌,持续推出新品,拓展线上线下全球化渠道,对高品质、稳定的生产供应有持续的增量需求,绿联的全球化布局也会带动配套生产端的业务增长,对有产能优势的工厂来说是新机会。

3. 转型启示:传统制造工厂转型升级,需要加大研发投入,提升自研技术能力,跟进智能化趋势,依托品牌化路线打开增长空间,拥抱全球化电商与线下渠道可以获得更多增长增量。

从绿联科技半年报可以看出当前消费电子行业的发展趋势,以及服务商可挖掘的机会,干货整理如下:

1. 行业发展趋势:当前消费电子行业整体向智能化、全球化方向发展,AI赋能C端消费电子是核心增长方向,越来越多品牌把打造第二增长曲线的重心放在AI相关品类上,同时品牌出海加速,从线上单一渠道往线上线下全渠道布局发展,多数品牌都在持续加大研发投入,拓展新渠道。

2. 品牌客户核心痛点:品牌打造AI相关新品,需要对应的智能化技术研发配套支持,全球化全渠道布局,需要渠道对接、供应链配套、合规运营等多方面的服务支持,多渠道运营也需要对应的营销、仓储物流服务支持。

3. 解决方案机会:服务商可以围绕AI消费电子打造技术研发配套服务,针对品牌出海线下拓展提供海外渠道对接、合规服务,针对新兴平台多渠道运营提供配套运营服务,抓住品牌出海多渠道拓展的红利,挖掘新的业务增长。

绿联科技的渠道布局情况,反映了当前品牌方对平台的需求,也为平台运营招商提供参考,干货整理如下:

1. 品牌方的渠道需求:头部有产品力的品牌,倾向于深耕核心优势平台放大自身优势,同时多渠道布局拓展增量,核心平台需要给到头部品牌足够的资源支持,帮助品牌扩大优势,实现共赢,新兴渠道和线下渠道是品牌获取新增长的重要方向。

2. 不同渠道的最新表现:亚马逊作为核心跨境平台,对头部3C品牌的支撑效果突出,绿联在亚马逊渠道营收超22亿元,增速超71%,占总营收近四成;国内天猫京东整体增长稳定,份额变化不大;线下实体零售渠道成为品牌拓展新增量的重要方向,绿联线下营收增速超65%。

3. 平台运营招商启示:平台可以重点引入有研发优势和产品力的头部3C品牌,给到资源支持,共同做大市场;线下海外零售平台可以积极对接优质中国3C品牌,吸引品牌入驻,抓住中国3C品牌出海的增长红利,挖掘自身增量。

绿联科技半年报反映出当前中国3C消费电子产业的多个新动向,可供产业研究者参考的干货整理如下:

1. 产业发展新动向:AI技术已经落地消费级C端产品,AI赋能的消费级智能存储成为行业新的增长曲线,中国本土品牌已经实现弯道超车,绿联2025年已经超越群晖、威联通等国际老牌厂商,拿到消费级NAS出货量和零售额双料冠军;中国3C品牌出海加速,头部品牌境外收入占比已经超过六成,成为增长核心动力,出海从线上单一渠道往线上线下全渠道布局发展。

2. 新特征与新问题:当前头部消费电子品牌普遍采用“传统基本盘+第二增长曲线”双轮驱动的商业模式,通过持续高研发投入构建技术壁垒,打造自有品牌差异化竞争力的模式已经跑通;同时需要注意,资本市场对新赛道的热捧容易产生估值泡沫,市盈率过高脱离业绩支撑会出现回调,需要关注产业增长与资本预期的匹配问题。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

This article discloses key information from Ugreen Technology’s 2026 half-year report, with core takeaways summarized below:

1. Core performance: In H1 2026, Ugreen generated 5.821 billion yuan in operating revenue, up 50.92% year-over-year, and posted 431 million yuan in net profit attributable to parent company, a 56.90% YoY increase. All three core metrics hit their highest growth rates since Ugreen went public. The stock jumped more than 10% after the report release, pulling its price-to-earnings ratio down to around 27, entering a reasonable range aligned with industry peers.

2. Growth highlights: Ugreen’s three traditional core categories all posted growth above 40%, pushing its overall gross margin to 39.18%. As Ugreen’s second growth curve, its NAS (network-attached storage) business surged 85.53% YoY, and the company claimed the top spot in both shipment volume and retail sales for consumer-grade NAS in 2025. Its cross-border business grew 69.42% YoY and accounts for over 60% of total revenue, while offline revenue jumped 65.31% YoY following expansion into major global offline retail channels. R&D spending doubled year-over-year, and the company holds more than 2,500 patents, with a steady pipeline of new smart products.

This article extracts actionable growth insights from Ugreen Technology for consumer electronics brands, summarized below:

1. Business layout: Capitalize on the AI-powered consumer electronics trend to build a second growth curve. After positioning smart storage NAS as its second growth driver, Ugreen grew the segment by over 85% and surpassed long-established global legacy brands to claim the top two consumer NAS market positions in 2025, while solidifying its core traditional business. Cost optimization lifted its overall gross margin, driving steady improvement in profitability.

2. Channel development: Ugreen follows a "double down on core strengths + diversify across channels" strategy. It deepened its presence on its core channel Amazon to amplify its advantage, where revenue grew more than 71% and accounts for nearly 40% of total revenue. At the same time, it actively expanded into new channels: offline revenue grew 65.31% YoY, and the company successfully secured placement with multiple leading global offline retail giants. Overseas revenue now accounts for 66.79% of total revenue and has become the core driver of growth.

3. Competitive strategy: Ugreen continues to ramp up R&D investment, with H1 R&D spending doubling year-over-year after two consecutive years of double-digit growth. It has built technological barriers through its patent portfolio, launched new smart products tailored to different user needs, steadily expanded its product matrix, and strengthened its brand moat.

Ugreen Technology’s half-year report reveals the latest market shifts and opportunities in the 3C consumer electronics space, with key takeaways for 3C sellers summarized below:

1. Growth opportunities: AI-powered consumer-grade smart storage is currently a fast-growing blue-ocean market, with Ugreen’s segment growing 85.53% YoY. The overall overseas market grew 69.42% YoY, far outpacing the 23.46% growth of the domestic market, and has become the core driver of brand growth. Offline channels offer substantial room for growth, with Ugreen’s offline revenue growing 65.31% YoY, while emerging small platforms and independent stores also posted nearly 60% growth.

2. Actionable growth paths: Double down on your core advantaged channels to maximize strengths while expanding across multiple channels to diversify risk and capture incremental growth from different platforms. Consistently increase R&D investment to build differentiated products through technological advantage, lift gross margins, and establish your own competitive barriers.

3. Risk warning: The 3C consumer electronics sector sees greater capital market volatility. A P/E ratio that outpaces underlying business fundamentals can lead to a bubble correction. Sellers should pay close attention to the match between valuation and performance to avoid excessive speculation.

Ugreen Technology’s half-year report outlines current product demand and development direction for the consumer electronics industry, with key insights for 3C manufacturers summarized below:

1. Product design and manufacturing demand: The market currently sees strong demand for AI-enabled smart consumer electronics, particularly the fast-growing smart NAS segment. Products need to cover a full range of tiers from entry-level home models to professional flagship versions, with features tailored to different user groups: ordinary households, professional creators, and small and medium-sized teams. Local AI functionality is required to meet users’ smart storage demands.

2. Untapped business opportunities: As a fast-growing local 3C brand, Ugreen continues to launch new products and expand its global online and offline channel network, generating sustained incremental demand for high-quality, stable manufacturing supply. Ugreen’s global expansion will also drive growth for supporting upstream manufacturing, creating new opportunities for factories with surplus production capacity.

3. Transformation insights: To upgrade, traditional manufacturing plants need to increase R&D investment, build in-house technical capabilities, keep up with the smart industry trend, and unlock growth by pursuing a branding-focused route. Embracing global e-commerce and offline channels will deliver additional growth.

Ugreen Technology’s half-year report reveals current consumer electronics industry trends and untapped opportunities for service providers, with key takeaways summarized below:

1. Industry trends: The consumer electronics sector as a whole is moving toward smartification and globalization. AI-powered consumer-facing electronics is the core growth direction, and a growing number of brands are focusing their second growth curve on AI-related product categories. At the same time, brands are accelerating their overseas expansion, shifting from online-only operations to an omni-channel online-offline model, with most brands consistently increasing R&D investment and expanding into new channels.

2. Core pain points for brand clients: Brands developing new AI-related products need supporting smart technology R&D services. For global omni-channel expansion, they need support in channel connection, supply chain coordination, compliance operations and other areas, while multi-channel operations also require supporting marketing, warehousing and logistics services.

3. Opportunity for solution providers: Service providers can build R&D supporting services tailored for AI consumer electronics, offer overseas channel connection and compliance services for brands expanding into offline overseas markets, and provide supporting operational services for multi-channel operations on emerging platforms. This allows providers to capitalize on the growth dividend from brands’ global multi-channel expansion and unlock new business growth.

Ugreen Technology’s channel layout reveals current brand demand for platforms and offers actionable insights for platform operation and merchant recruitment, summarized below:

1. Channel demand from brands: Leading product-focused brands tend to double down on their core advantageous platforms to maximize strengths, while expanding across multiple channels to capture incremental growth. Core platforms need to provide sufficient resource support to leading brands to help them expand their advantage and achieve win-win growth. Emerging channels and offline channels have become key priorities for brands looking to unlock new growth.

2. Latest performance by channel: As the core cross-border platform, Amazon delivers strong support for leading 3C brands: Ugreen generated more than 2.2 billion yuan in revenue on Amazon, growing more than 71% YoY and accounting for nearly 40% of total revenue. Domestic platforms Tmall and JD.com posted steady overall growth with little change in market share. Offline physical retail has become a key area for brands to capture new incremental growth, with Ugreen’s offline revenue growing more than 65% YoY.

3. Insights for platform operation and recruitment: Platforms should prioritize onboarding leading 3C brands with R&D advantages and strong product capabilities, provide resource support to grow the market together. Offline overseas retail platforms can actively connect with high-quality Chinese 3C brands to attract them onboarding, capitalize on the growth dividend from Chinese 3C brands’ global expansion, and unlock their own incremental growth.

Ugreen Technology’s half-year report reveals multiple new trends in China’s 3C consumer electronics industry, with key insights for industry researchers summarized below:

1. New industry trends: AI technology has now been commercialized in mass consumer products, and AI-powered consumer-grade smart storage has become a new industry growth curve. Local Chinese brands have achieved a technological overtaking: in 2025, Ugreen surpassed long-established global players including Synology and QNAP to claim the top spot in both shipment volume and retail sales for consumer-grade NAS. Chinese 3C brands are accelerating their overseas expansion, with leading brands generating more than 60% of revenue from overseas markets that now serve as their core growth driver, shifting from online-only presence to a full omni-channel online-offline global layout.

2. New characteristics and emerging issues: Leading consumer electronics brands have widely adopted a "core traditional business + second growth curve" two-wheel driven business model. The approach of building technological barriers through sustained high R&D investment and building differentiated competitiveness through proprietary branding has been proven viable. At the same time, it is important to note that capital market enthusiasm for new growth tracks can easily create valuation bubbles, and corrections occur when P/E ratios outpace underlying performance. Researchers should pay close attention to the alignment between industrial growth and capital market expectations.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

【亿邦原创】9月2日消息,绿联科技(301606.SZ)近日发布2026年半年报,展现出强劲的增长动能与盈利能力。

报告期内,公司实现营业收入58.21亿元,同比增长50.92%,营收规模显著跃升;归母净利润达4.31亿元,同比增长56.90%;扣非归母净利润为4.20亿元,同比增长62.59%。三项核心指标的同比增速均创下上市以来新高。

亮眼业绩迅速获得二级市场积极回应。

财报发布次日,公司股价大涨逾10%,一举扭转此前一个多月的低迷走势,随后数个交易日延续震荡上行态势。截至发稿,股价一度触及57.86元,不过相较于其五月中旬创下的超80元股价高点,仍有不少失地有待收复。

走过震荡频繁、多空角力的上半年,绿联科技似乎已逐步企稳,向市场证明了自身稳健的业务基本盘,继续在核心主业赛道上攻城略地。


一.NAS业务延续高速增长,全产品线毛利润上涨

报告期内,绿联科技的三大传统产品线表现稳健。

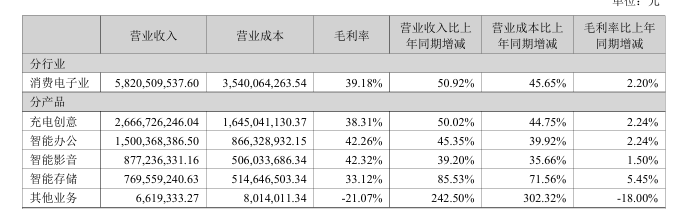
分品类来看,充电创意品类收入达26.67亿元,同比增长50.02%,贡献了接近一半的营收;另两大传统业务板块智能办公、智能影音的收入分别为15.00亿元、8.77亿元,分别同比增长42.26%和42.32%。

值得注意的是,各条产品线的毛利率较去年同期均实现了上升。整体毛利率达39.18%,较同期增长2.2%。作为以供应链能力见长的老牌3C厂商,绿联科技的成本管控能力进一步显现。

不过,真正引人注目的却是其近一年以来受“OpenClaw”等AI概念驱动而暴涨的消费级NAS业务。

据悉,绿联已经将以NAS为核心品类的智能存储品类,定义为公司的“第二增长曲线”,并持续加大系统级研发投入。目前,该品类已经成为公司营收增速最快的产品线之一:拿下7.70亿元营收,同比大增85.53%。

报告指出,公司已构建覆盖家庭入门级至专业旗舰级的多档位NAS产品矩阵,核心产品依托自研UGOS Pro系统,搭载本地AI算力,可实现文件智能打标、快速整理、语义检索照片文件、个人知识库总结等多项智能化功能。

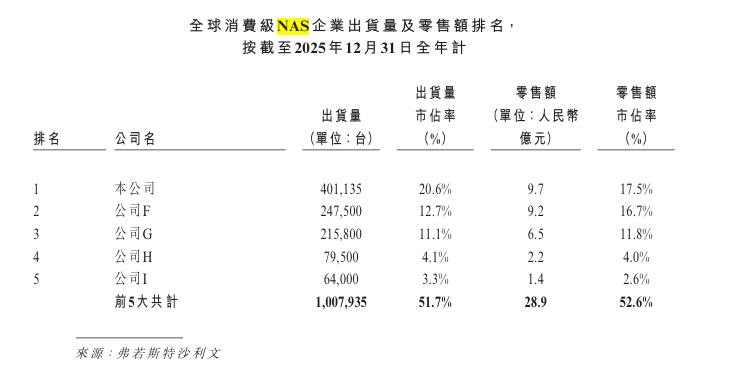
根据此前公开披露的数据显示,2025年,绿联已经超过业内的一众“老前辈”和新锐势力(推测公司F系Synology群晖、公司G为QNAP威联通、公司H为Buffalo巴法络、公司I为极空间ZhiTi),在消费级NAS产品上一骑绝尘,以断层式领先夺下了出货量和零售额的“双料冠军”。

二.跨境业务暴涨,线下收入可观,亚马逊渠道“长板更长”

2026年上半年,绿联在海外市场依旧跑出“加速度”。

分地域来看,境外收入38.88亿元,同比增长69.42%,占比提升至66.79%,成为增长核心动力;境内收入19.26亿元,同比增长23.46%,国内市场稳步渗透。

与此同时,在渠道布局上,绿联呈现出“长板更长、多点开花”的态势。

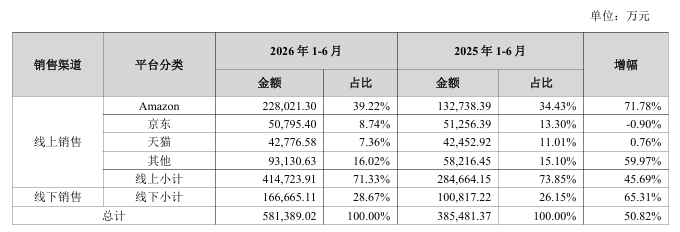
亚马逊仍是核心“粮仓”,单一渠道独大的情况继续存在:报告期内,亚马逊渠道为绿联创新贡献了高达22.80亿元的营收,同比大增71.78%,占据总营收份额的39.22%——较去年同期上涨4.79%。

而在国内电商平台,绿联科技在京东与天猫分别实现了5.08与4.28亿元的营收,相较去年同期各自保持微跌和微升,变化幅度不大。

除亚马逊、天猫、京东外的其他渠道(主要是境外的独立站、速卖通、Lazada、Shopee、Noon、TikTok等)合计实现收入9.31亿元人民币,同比大幅增长59.97%。

整体而言,线上渠道依旧是绿联科技的主要销售场域。上半年,其线上收入总计41.47亿元,在总营收中占比71.33%,同比增长15.69%。

值得关注的是绿联在“重塑线下”维度的野心。上半年,其线下收入达16.67亿元,在总营收中占比28.67%,同比大涨65.31%。

报告期内,绿联科技积极拓展线下渠道,进一步在全球市场拓展其经销网络,不断推进全球化销售布局。通过战略合作大型商超、专业渠道及区域头部经销商,在境外,其已成功进驻美国Walmart、Costco、Bestbuy、B&H、MicroCenter,欧洲Media Markt,日本Bic Camera、Yodobashi Camera等知名零售巨头渠道体系。


三.研发投入快速增长,市盈率进入合理区间

此前,在绿联科技发布2025年年报时,曾有不少市场评论指出,绿联的市盈率反映出“市场的过热情绪”——当时绿联的市盈率一度高达40以上,远超安克创新、漫步者、传音控股等电子板块同业巨头。

本季度,在经过一系列市场调整后,绿联的市盈率剔除泡沫,平缓降至27上下,基本落入与安克(23.11)、传音(20.72)、漫步者(20.58)同一区间的上沿,回归相对健康稳定的范围。

另一方面,绿联亦在经营层面加紧落子,力图加固行业护城河并提升市场认可。

半年报显示,2026上半年,其研发投入3.49亿元,同比暴增101.21%,主要系公司研发团队规模扩大,员工薪酬增加所致。

事实上,研发投入的扩张并非短期举措——去年其研发费用已同比增长43.96%,本年度则在此高基数上再度提速。截至报告期末,公司全球累计持有注册专利2506项,其中发明专利48项,另有349项发明专利正处于实质审查阶段。

伴随研发加码,绿联本季度密集推出多款新品。

例如,在智能存储领域,其向市场推出旗舰机型iDX6011Pro,该产品搭载本地大模型及雷电4接口,专为中小型团队与专业创作者的高强度存储及本地AI算力需求设计。

而在智能影音领域,则推出X8耳夹型耳机等多款新品,集成新一代高速音视频传输、新一代蓝牙音频、低功耗高精度定位、高清影像采集及高刷便携显示等多项自主核心技术,进一步丰富了产品矩阵。


亿邦持续追踪报道该情报,如想了解更多与本文相关信息,请扫码关注作者微信。

本文首发于 亿邦动力 官方网站

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

绿联科技2026年上半年经营业绩怎么样?

2026年上半年绿联科技实现营业收入58.21亿元,同比增长50.92%;归母净利润4.31亿元,同比增长56.90%;扣非归母净利润4.20亿元,同比增长62.59%,三项核心指标增速均创下上市以来新高。

绿联科技的第二增长曲线是什么业务?

绿联科技将以NAS为核心品类的智能存储品类定义为第二增长曲线,2026年上半年该品类实现营收7.70亿元,同比大增85.53%,已构建覆盖家庭入门级到专业旗舰级的多档位NAS产品矩阵,2025年已拿下消费级NAS出货量和零售额双料冠军。

绿联科技的主要销售渠道有哪些?

绿联科技以线上渠道为核心销售场域,2026年上半年线上收入占总营收71.33%,亚马逊是核心渠道,贡献营收22.80亿元,占总营收39.22%;线下收入占比28.67%,已进驻沃尔玛、Costco等全球多个知名零售巨头渠道体系。

绿联科技2026年上半年研发投入情况如何?

2026年上半年绿联科技研发投入达3.49亿元,同比增长101.21%,主要源于研发团队规模扩大、员工薪酬增加。截至报告期末,公司全球累计持有注册专利2506项,其中发明专利48项。

这么好看,分享一下?

朋友圈 分享

APP内打开

赞 +1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0