广告
加载中

试水线下销售 美团松鼠便利试点“店仓一体”

姜琪 2026-08-05 17:26
姜琪 2026/08/05 17:26

邦小白快读

EN
全文速览

本文核心是美团旗下松鼠便利在千店布局后,于上海试点首家店仓一体模式的新尝试,核心干货信息如下:

1. 模式基础:松鼠便利已经开出1000家门店,覆盖百余座城市,此次试点是在原有线上前置仓的基础上,首次开放线下营业,核心目的是拓宽增收渠道。

2. 模式优势:对比纯前置仓只做线上履约、功能单一的缺点,店仓一体的节点同时承担仓库、线下门店、品牌展示中心三种功能,能获得线下自然流量,平摊租金和人力成本,还能扩大订单规模,提升供应链效率,形成正向循环。

3. 门店特点:门店按便利店设计动线陈列,但保留仓的属性,暂不设休闲区,也没有引入传统便利店的鲜食品类,商品延续线上5000余支标品SKU,新增了小家电、家清等社区长尾需求商品。

本文为布局即时零售赛道的品牌商提供了行业趋势参考与模式创新思路,核心干货如下:

1. 行业趋势:当前即时零售赛道竞争已经进入新阶段,阿里、京东等头部玩家都在加码布局,行业从规模扩张转向拼内功,竞争核心最终回归做好供应链、提升商品质量、服务用户的本质。

2. 渠道创新方向:松鼠便利的店仓一体模式,是在原有前置仓基础上叠加线下功能,不需要大规模新建网点,就能拓宽增收渠道,还能通过线上线下订单叠加扩大规模,提升供应链效率,形成正向增长循环,适合有前置仓布局的品牌参考。

3. 产品研发方向:该模式没有复制传统便利店,而是错位竞争,延续线上标品+效率的优势,重点强化社区长尾需求商品,避开传统便利店扎堆的鲜食赛道,为品牌产品布局提供了新思路。

本文给布局即时零售的卖家提供了机会方向、模式参考与风险提示,核心干货如下:

1. 行业机会:当前即时零售已经进入拼内功的阶段,场景叠加、供应链效率提升是新的增长机会,店仓一体模式适合已有前置仓布局的卖家改造升级。

2. 模式收益:该模式在原有前置仓基础上叠加线下门店功能,不需要额外投入大量新成本,就能获得线下自然流量,还能平摊租金、人力等固定成本,改善纯前置仓模式盈利性不足的问题,同时还能作为品牌展示和用户体验的触点,一举多得。

3. 注意提示:该模式目前仍处于试点阶段,现阶段不需要新增传统便利店的鲜食品类、休闲区等配置,只需要在原有线上SKU盘的基础上延伸,重点补充社区长尾商品,改造门槛较低,卖家可以根据自身资源试点试错。

本文给对接即时零售渠道的消费品工厂提供了需求方向、商业机会与数字化转型启示,核心干货如下:

1. 产品生产设计需求:随着店仓一体模式的推广,即时零售渠道对社区长尾需求商品的需求会逐步提升,其中小家电、家清类商品的需求已经被明确强化,工厂可以针对即时零售场景调整产品结构,推出适配该渠道的相关产品。

2. 商业合作机会:松鼠便利采用自建供应链、强管控加盟模式,订单规模越大供应链效率越高,店仓一体会进一步扩大订单规模,工厂可以和这类平台系零售品牌对接,获得稳定的大宗出货渠道,依托大订单降低自身生产升本。

3. 数字化转型启示:该模式延续线上标品+效率的优势,要求供应链端适配线上化的库存管理、快速履约要求,工厂需要加快推进数字化改造,适配渠道的效率要求,才能拿到更多订单。

本文给即时零售相关服务商提供了行业趋势、客户痛点与业务机会,核心干货如下:

1. 行业发展趋势:即时零售行业已经结束了早期跑马圈地的规模扩张阶段,进入了拼内功的模式优化阶段,大量布局前置仓的品牌都有降本增效、模式升级的需求,相关服务需求会持续增长。

2. 核心客户痛点:早期纯前置仓模式存在明显短板,功能单一,获客完全依赖线上,租金和人力成本高,模型经济性差,很多品牌都有改造原有前置仓的需求,希望通过模式优化提升盈利水平。

3. 业务解决方案方向:服务商可以围绕店仓一体改造开发相关服务,比如适配店仓一体的门店动线设计、陈列设计服务,适配双渠道运营的库存管理系统,供应链效率优化服务等,满足品牌在原有前置仓基础上叠加线下功能的需求,开拓新的业务增长点。

本文给布局即时零售的平台商提供了行业风向、模式参考与运营思路,核心干货如下:

1. 行业竞争现状:当前即时零售赛道头部玩家竞争加剧,阿里整合资源押注即时零售,京东也持续加码,行业已经进入拼内功的阶段,竞争核心回归供应链、商品质量与用户服务,平台需要优化现有模式提升竞争力。

2. 商家与用户需求:现有纯前置仓模式盈利性不足,商家希望通过场景叠加拓宽增收渠道、平摊成本,用户也有线下体验、即时自提的需求,店仓一体模式刚好匹配这类需求。

3. 运营优化参考:松鼠便利的试点是在原有仓储网点基础上做改造,不需要大规模新建网点,投入成本低,还能发挥原有线上供应链和SKU的优势,平台可以参考该模式,开放改造扶持政策,吸引已有前置仓资源的商家参与试点,丰富平台即时零售的服务场景,提升整体竞争力。

本文给零售产业研究者提供了即时零售赛道的最新产业动向与商业模式创新样本,核心干货如下:

1. 产业新动向:即时零售行业经过早期的跑马圈地、规模扩张后,已经进入深耕阶段,当前头部玩家纷纷加码,行业竞争从拼规模转向拼内功,整个行业的发展重心回归零售本质,也就是做好供应链、提升商品质量、服务用户。

2. 新模式研究价值:松鼠便利的店仓一体模式是对原有前置仓模式的重要创新,解决了纯前置仓模式功能单一、获客成本高、盈利性差的痛点,让前置仓节点具备了自我造血能力,同时充分发挥了原有线上供应链、SKU体系的优势,实现了线上线下的协同。

3. 产业研究启示:该模式是品牌千店规模后探索业态升级的新尝试,验证了线上优势向线下场景延伸的可行性,为即时零售业态创新提供了新的研究样本,也反映了当前零售行业模式创新的方向,就是围绕效率优化和成本控制升级原有业态。

返回默认
声明:快读内容全程由AI生成,请注意甄别信息。如您发现问题,请发送邮件至 run@ebrun.com 。

我是 品牌商 卖家 工厂 服务商 平台商 研究者 帮我再读一遍。

Quick Summary

This article focuses on Meituan’s convenience store brand Songshu Convenience, which is piloting its first "omnichannel store-warehouse" model in Shanghai after rolling out 1,000 stores across China. Key takeaways are as follows:

1. Foundation of the model: With 1,000 stores already operating across more than 100 Chinese cities, this pilot adds in-store retail to Songshu’s original online-based front warehouse setup. Its core goal is to expand revenue streams.

2. Advantages of the model: Unlike pure front warehouses that only handle online order fulfillment with limited functionality, the integrated store-warehouse node serves three roles: storage, offline retail, and brand display. It captures offline organic traffic, spreads rent and labor costs across more revenue, boosts order volume, improves supply chain efficiency, and creates a positive growth cycle.

3. Store characteristics: The space follows convenience store layout and circulation flow but retains storage functions. It currently has no seating area and does not carry the fresh food offerings common at traditional convenience stores. It keeps the 5,000+ standardized SKUs used for online business, and adds products that meet long-tail community demand, such as small home appliances and household cleaning goods.

This article provides industry trend insights and innovative model inspiration for brands positioned in the instant retail track. Key takeaways are as follows:

1. Industry trends: Competition in instant retail has entered a new phase. Leading players including Alibaba and JD.com are scaling up their investments, and the industry has shifted from pure expansion to optimizing core operations. Competition will ultimately return to the fundamentals of retail: building a capable supply chain, improving product quality, and serving users well.

2. Channel innovation direction: Songshu Convenience’s integrated store-warehouse model adds offline functions to existing front warehouse networks, eliminating the need for large-scale new site construction while expanding revenue streams. Combined online and offline orders also boost volume and improve supply chain efficiency, creating a positive growth cycle. This model is a valuable reference for brands with existing front warehouse networks.

3. Product development direction: Instead of copying traditional convenience stores, the model pursues differentiated competition by retaining the advantages of online standardized SKUs and operational efficiency. It focuses on products that meet long-tail community demand and avoids the crowded fresh food category that traditional convenience stores dominate, offering a new path for brand product positioning.

This article outlines opportunity directions, model references and risk notes for sellers engaged in instant retail. Key takeaways are as follows:

1. Industry opportunities: Instant retail has entered an era of focusing on core operations. Overlaying multiple retail scenarios and improving supply chain efficiency have emerged as new growth opportunities, and the integrated store-warehouse model is well suited for upgrading sellers that already have front warehouse networks.

2. Benefits of the model: By adding offline store functions to existing front warehouses, the model requires no large additional upfront investment, while capturing organic offline traffic and spreading fixed costs such as rent and labor. It addresses the weak profitability of pure front warehouse models, and also serves as a touchpoint for brand display and user experience, delivering multiple benefits at once.

3. Key notes: The model is still in the pilot stage. For now, it does not require adding fresh food categories or customer seating like traditional convenience stores. Sellers only need to extend their existing online SKU assortment by adding long-tail community-focused products, keeping transformation barriers low. Sellers can pilot the model for testing based on their own resources.

This article provides demand direction, business opportunities and digital transformation insights for consumer goods factories that serve instant retail channels. Key takeaways are as follows:

1. Product design and production demand: As the integrated store-warehouse model scales, demand for products that meet long-tail community needs in instant retail channels will gradually increase. Demand for small home appliances and household cleaning products has already been clearly highlighted. Factories can adjust their product mix for the instant retail scenario and launch products tailored to this channel.

2. Business cooperation opportunities: Songshu Convenience operates a self-built supply chain with tightly managed franchising. Larger order volumes drive higher supply chain efficiency, and the store-warehouse model will further expand order scale. Factories can partner with this type of platform-affiliated retail brand to secure a stable bulk shipping channel and lower production costs through large order volumes.

3. Digital transformation insights: The model retains the advantages of online standardized SKUs and operational efficiency, which requires supply chain players to adapt to online inventory management and fast order fulfillment requirements. Factories need to accelerate digital transformation to meet the channel’s efficiency requirements in order to win more orders.

This article shares industry trends, client pain points and business opportunities for service providers serving the instant retail sector. Key takeaways are as follows:

1. Industry development trends: The instant retail industry has ended its early stage of rapid expansion for scale, and has entered a new phase focused on optimizing core operations. Many brands with existing front warehouse networks are seeking to cut costs, boost efficiency and upgrade their models, driving sustained growth in demand for related services.

2. Core client pain points: Early pure front warehouse models have clear drawbacks: single functionality, full reliance on online for customer acquisition, high rent and labor costs, and poor unit economics. Many brands are looking to transform their existing front warehouses to improve profitability through model optimization.

3. Business solution direction: Service providers can develop new offerings tailored for store-warehouse transformation, such as customized store circulation and display design, inventory management systems for dual-channel operation, and supply chain efficiency optimization services. These offerings meet brands’ demand for adding offline functions to existing front warehouses and open up new growth avenues for service providers.

This article provides industry trend insights, model references and operational inspiration for platform operators in the instant retail space. Key takeaways are as follows:

1. Current competitive landscape: Competition in the instant retail track has intensified among leading players. Alibaba has consolidated resources to bet big on instant retail, while JD.com continues to ramp up investment. The industry has entered a phase of focusing on core operations, with competition returning to supply chain, product quality and user service. Platforms need to optimize existing models to improve competitiveness.

2. Merchant and user demand: The existing pure front warehouse model suffers from weak profitability. Merchants want to expand revenue streams and spread costs through multi-scenario overlay, while users have demand for offline experience and instant in-store pickup. The integrated store-warehouse model perfectly matches these demands.

3. Operational optimization reference: Songshu Convenience’s pilot transforms existing warehouse sites instead of building large-scale new networks, keeping capital investment low while leveraging existing advantages in online supply chains and SKUs. Platforms can reference this model by launching supportive policies for transformation, encouraging merchants with existing front warehouse resources to join the pilot, enriching instant retail service scenarios on the platform and boosting overall competitiveness.

This article provides the latest industry developments and a new business model innovation sample for retail industry researchers. Key takeaways are as follows:

1. New industry developments: After early-stage expansion to gain scale, the instant retail industry has entered a deep cultivation phase. Leading players are all ramping up investments, and competition has shifted from scale growth to operational optimization. The industry’s focus has returned to the fundamentals of retail: building a robust supply chain, improving product quality, and serving users well.

2. Research value of the new model: Songshu Convenience’s integrated store-warehouse model is a significant innovation on the original front warehouse model. It addresses the pain points of pure front warehouses, including single functionality, high customer acquisition costs and weak profitability, gives front warehouse nodes the ability to generate self-sustaining profits, and leverages the advantages of existing online supply chains and SKU systems to achieve online-offline synergy.

3. Implications for industry research: The model is a new attempt at format upgrade after a brand reached 1,000 stores, and it validates the feasibility of extending online advantages to offline scenarios. It provides a new research sample for instant retail format innovation, and reflects the current direction of retail innovation: upgrading existing formats through efficiency optimization and cost control.

Disclaimer: The "Quick Summary" content is entirely generated by AI. Please exercise discretion when interpreting the information. For issues or corrections, please email run@ebrun.com .

I am a Brand Seller Factory Service Provider Marketplace Seller Researcher Read it again.

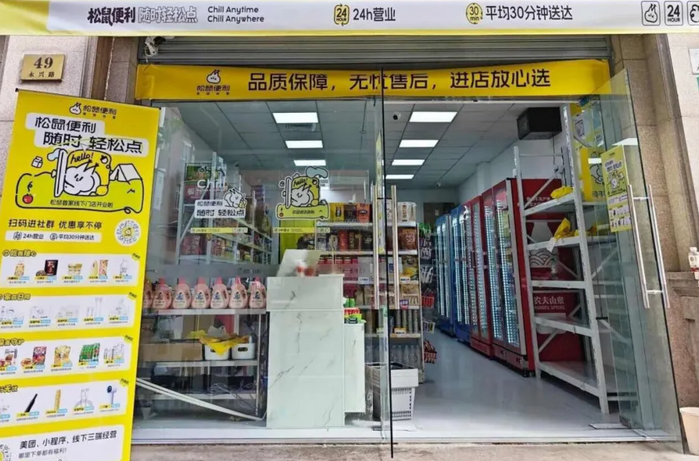
【亿邦原创】据《商业观察家》报道,继小象超市开出线下实体店后,美团旗下松鼠便利近期于上海启动首家“店仓一体”试点。该店在原有线上前置仓履约服务的基础上,首次向线下开放营业。

亿邦动力了解到,松鼠便利此举是在原有仓的基础上叠加功能,以此拓宽门店的增收渠道。对自建供应链、强管控加盟模式的松鼠便利而言,订单规模越大,供应链效率越能兑现。线上线下双渠道的叠加,恰好能撬动这个正向循环。截至2026年7月31日,松鼠便利门店数已达1000家,覆盖百余座城市。

从现场看,其货架、动线和陈列均按便利店标准设计,但“仓”的属性依然明显——货架较高、通道紧凑,未设休闲区,且暂未引入传统便利店的鲜食品类。

商品层面,该店在保留水饮、零食等品类的同时,强化了小家电、家清等社区长尾需求品,整体仍基于其线上5000余支SKU的标品盘进行延伸。这显示出松鼠便利的线下尝试,并非简单复制传统便利店,而是将线上“标品+效率”优势向线下场景的一次投射。

对比来看,纯前置仓是单纯的履约节点,功能单一,获客完全依赖线上。而“店仓一体”让每个仓都具备了自我造血能力,它既是服务线上订单的仓库,也是吸引自然流量的门店,以及品牌展示和体验的中心。 这种模式通过叠加线下销售,能有效平摊租金和人力成本,改善前置仓单一模型的经济性。

随着阿里通过淘宝闪购整合盒马、天猫等资源全力押注即时零售,以及京东等对手的持续加码,即时零售的竞争已进入“拼内功”阶段。零售业的竞争最终要回到做好供应链、提升商品质量、服务好用户的本质,松鼠便利等品牌的“店仓”试点,亦是拼内功的一种投射。

亿邦持续追踪报道该情报,如想了解更多与本文相关信息,请扫码关注作者微信。

文章来源:亿邦动力

广告
微信
朋友圈

FAQ回顾

松鼠便利属于哪个公司旗下的品牌?

松鼠便利是美团旗下的零售品牌,采用自建供应链、强管控加盟模式,截至2026年7月31日,其门店数量已达1000家,覆盖国内百余座城市。

店仓一体模式相比纯前置仓有哪些优势?

纯前置仓仅为单一履约节点,获客完全依赖线上,而店仓一体同时具备线上订单履约仓库、线下获客门店、品牌展示体验中心属性,可叠加线下销售平摊租金人力成本,改善前置仓模型的经济性。

美团松鼠便利的店仓一体试点有什么特点?

美团松鼠便利首家店仓一体试点落地上海,按便利店标准设计货架动线,保留水饮零食等品类,强化小家电、家清等社区长尾需求品,未设休闲区和传统鲜食品类,依托线上5000余支标品SKU延伸供给。

当前即时零售行业的竞争趋势是什么?

当前阿里、京东等平台均在加码布局即时零售赛道,行业竞争已进入“拼内功”阶段,最终将回归做好供应链、提升商品质量、优化用户服务的零售本质。

这么好看,分享一下?

朋友圈 分享

APP内打开

+1
+1
微信好友 朋友圈 新浪微博 QQ空间
关闭
收藏成功
发送
/140 0